California CDTFA discusses draft Regulation 1600 on digital products; these are proposals, not adopted rules
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in United States as they stand today, see the United States guide →
- Jurisdiction
- United States (California)
- Tax
- Sales and use tax
- Change type
- Digital services
- Status
- Proposed
- Impact
- Watch
- Announced
- 10 September 2026
- Authority
- California Department of Tax and Fee Administration (CDTFA)
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Sellers and purchasers of digital products and prewritten software, including SaaS, in California.
Monitor CDTFA draft Regulation 1600 series; no rule is final.
Tax engineReporting
CDTFA held an Interested Parties meeting on 10 September 2026 on the application of sales and use tax to digital products. The agenda lists proposed Regulation 1600 (Application of Sales and Use Tax to Digital Products), proposed Regulation 1600.1 (Tax Liability Threshold for Digital Products, including a use tax direct payment permit or Department waiver once the threshold is exceeded), proposed Regulation 1600.2 (Digital Products Purchased for Multiple Points of Use), proposed new Regulation 1502.2 (Custom Computer Software), and amendments to Regulations 1502 and 1507. These are draft regulation proposals, not adopted rules.
What changed in detail
These are draft proposals for discussion, not adopted regulations. The CDTFA held an Interested Parties meeting on 10 September 2026 on how sales and use tax applies to digital products.
The agenda lists proposed Regulation 1600 (Application of Sales and Use Tax to Digital Products), proposed Regulation 1600.1 (Tax Liability Threshold for Digital Products, including a use tax direct payment permit or Department waiver once the threshold is exceeded) and proposed Regulation 1600.2 (Digital Products Purchased for Multiple Points of Use). It also lists proposed new Regulation 1502.2 (Custom Computer Software) and amendments to Regulations 1502 and 1507.
What it means
Nothing here changes what a seller must do today. The statute that takes effect on 1 January 2027 is the operative rule; the draft regulations show how the CDTFA may interpret it, particularly on the purchaser-liability threshold and multiple points of use. Monitor the series for formal rulemaking before treating any draft wording as settled.
Proof
Item D – Proposed Regulation 1600, Application of Sales and Use Tax to Digital Products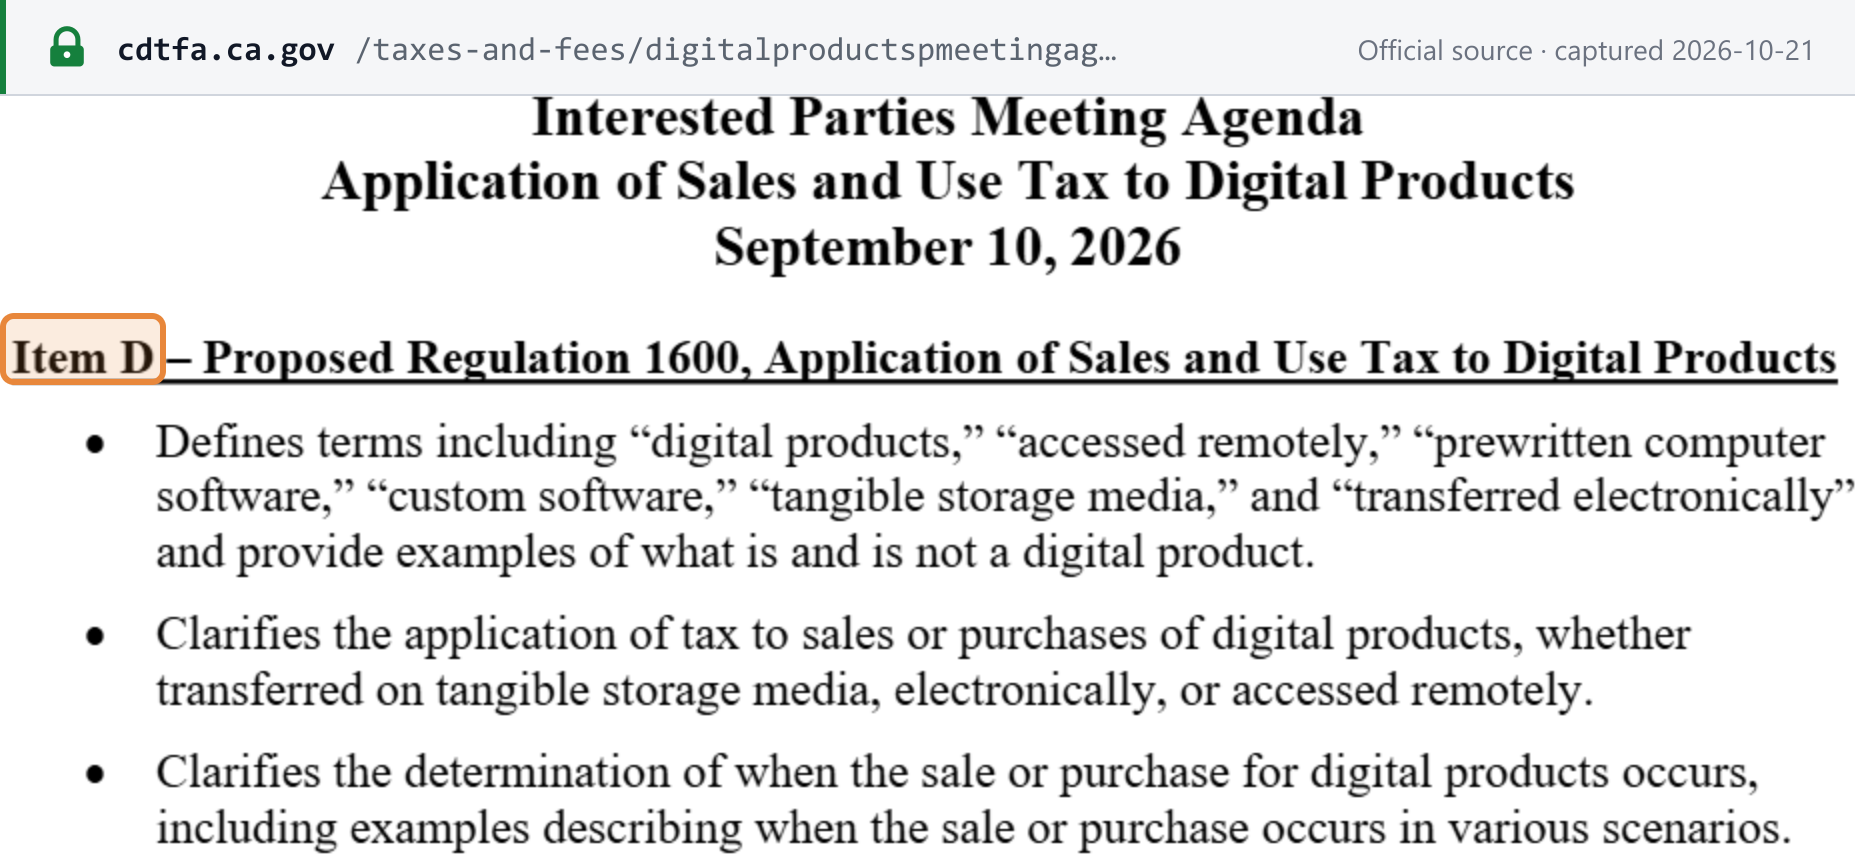 Source snapshot of the official page. Open full size ↗