Colorado extends sales tax to electronically delivered software from 1 January 2027
This page records one dated change. For the rules in United States as they stand today, see the United States guide →
- Jurisdiction
- United States
- Tax
- Sales Tax
- Change type
- Digital services
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 4 June 2026
- Effective
- 1 January 2027
- Authority
- Colorado General Assembly
- Systems
- Tax engine, Invoicing, E-commerce
- Verified
- Fetched from official source · high confidence
Sellers of software, SaaS and mobile applications delivered electronically to Colorado customers, unless a negotiated-license or particular-user exemption applies.
Assess Colorado sales/use tax exposure on SaaS, downloaded software and mobile-app sales delivered electronically and prepare to charge/remit tax from 1 January 2027 unless a negotiated-license or particular-user exemption applies.
Tax engineInvoicingE-commerce
Colorado House Bill 26-1223 (signed by the Governor 4 June 2026, Session Laws of Colorado 2026, Chapter 379) amends C.R.S. 39-26-102(15)(c) to remove the requirement that computer software be prepackaged, shrink-wrapped and delivered in a tangible medium to count as taxable tangible personal property, and adds a new C.R.S. 39-26-713(3) exemption limited to computer software governed by a negotiated (non-standard-form) license agreement or developed for a particular user. The effect is that electronically delivered software, including SaaS and mobile applications, becomes subject to Colorado sales and use tax. Sections 2 and 3 of the act apply to the sale, storage, use, and consumption of tangible personal property on or after 1 January 2027.
What changed in detail
Colorado House Bill 26-1223, signed by the Governor on 4 June 2026 (Session Laws of Colorado 2026, Chapter 379), amends C.R.S. 39-26-102(15)(c) to remove the requirement that computer software be prepackaged, shrink-wrapped and delivered in a tangible medium to count as taxable tangible personal property, and adds a new C.R.S. 39-26-713(3) exemption limited to computer software governed by a negotiated, non-standard-form license agreement or developed for a particular user. The effect is that electronically delivered software — including SaaS and mobile applications — becomes subject to Colorado sales and use tax. Sections 2 and 3 of the act apply to the sale, storage, use and consumption of tangible personal property on or after 1 January 2027.
What it means
The prior rule turned on delivery method: shrink-wrapped software in a box was taxable, the same software downloaded was not. That distinction is gone. Sellers of SaaS, downloaded software and mobile apps into Colorado should assess exposure now — the negotiated-license and particular-user exemptions are narrow carve-outs, not a general escape route for standard subscription products, and the 1 January 2027 date is the point tax must actually be charged and remitted, not merely tracked.
Proof
SECTION 9. Applicability. Sections 2 and 3 of this act apply to the sale, storage, use, and consumption of tangible personal property on or after January 1, 2027.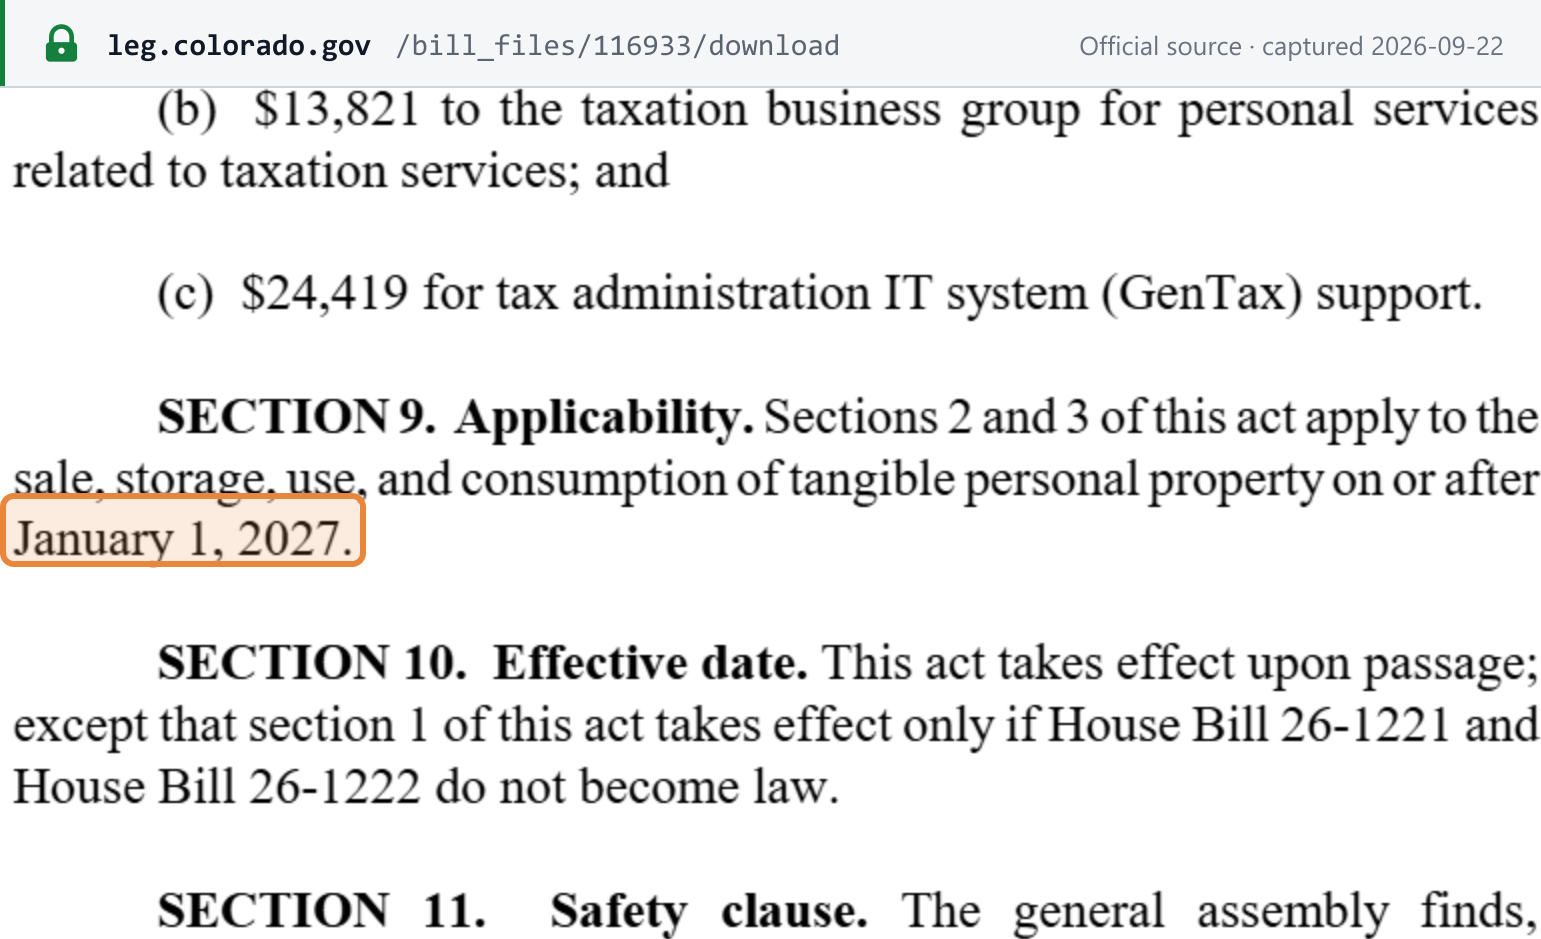 Source snapshot of the official page. Open full size ↗