South Dakota lets counties impose a gross receipts tax of up to 0.5%, with the earliest start in January 2027
This page records one dated change. For the rules in United States as they stand today, see the United States guide →
- Jurisdiction
- United States (South Dakota)
- Tax
- Sales and use tax
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Effective
- 1 January 2027
- Authority
- South Dakota Legislature
- Systems
- Tax engine, POS, E-commerce
- Verified
- Fetched from official source · medium confidence
Retailers and sellers in South Dakota counties that adopt the tax, and anyone maintaining South Dakota rate tables.
Monitor South Dakota county ordinances and add county gross receipts tax rates to the tax engine when a county notifies the Department of Revenue.
Tax enginePOSE-commerce
South Dakota Senate Bill 96 (2026), as enrolled, authorizes a county to impose a gross receipts tax not exceeding one-half percent on the same base as the state sales and use tax (tangible personal property, products transferred electronically and services taxable under SDCL chapters 10-45 and 10-46), with proceeds credited against county property taxes on owner-occupied property. A county ordinance or amendment takes effect only on 1 January or 1 July, following at least ninety days' notification to the Secretary of Revenue; the Department of Revenue states the earliest a county tax can take effect is January 2027. No county adoption was confirmed in the sources read.
What changed in detail
South Dakota Senate Bill 96 (2026), as enrolled, authorises a county to impose a gross receipts tax not exceeding one-half percent. The base is the same as the state sales and use tax: tangible personal property, products transferred electronically and services taxable under SDCL chapters 10-45 and 10-46. Proceeds are credited against county property taxes on owner-occupied property.
A county ordinance or amendment takes effect only on 1 January or 1 July, following at least ninety days’ notification to the Secretary of Revenue. The Department of Revenue states that the earliest a county tax can take effect is January 2027. No county has adopted the tax as of 21 October 2026.
What it means
This is an enabling law: no county rate exists yet. Sellers and rate-table maintainers should watch for county ordinances and Department of Revenue notices, and add a county rate only once a county has notified the Secretary of Revenue and a start date is published.
Proof
A county may impose a gross receipts tax not to exceed one-half percent on the gross receipts of all sales of tangible personal property, any product transferred electronically, and services, that are taxable pursuant to chapters 10-45 and 10-46 in the county.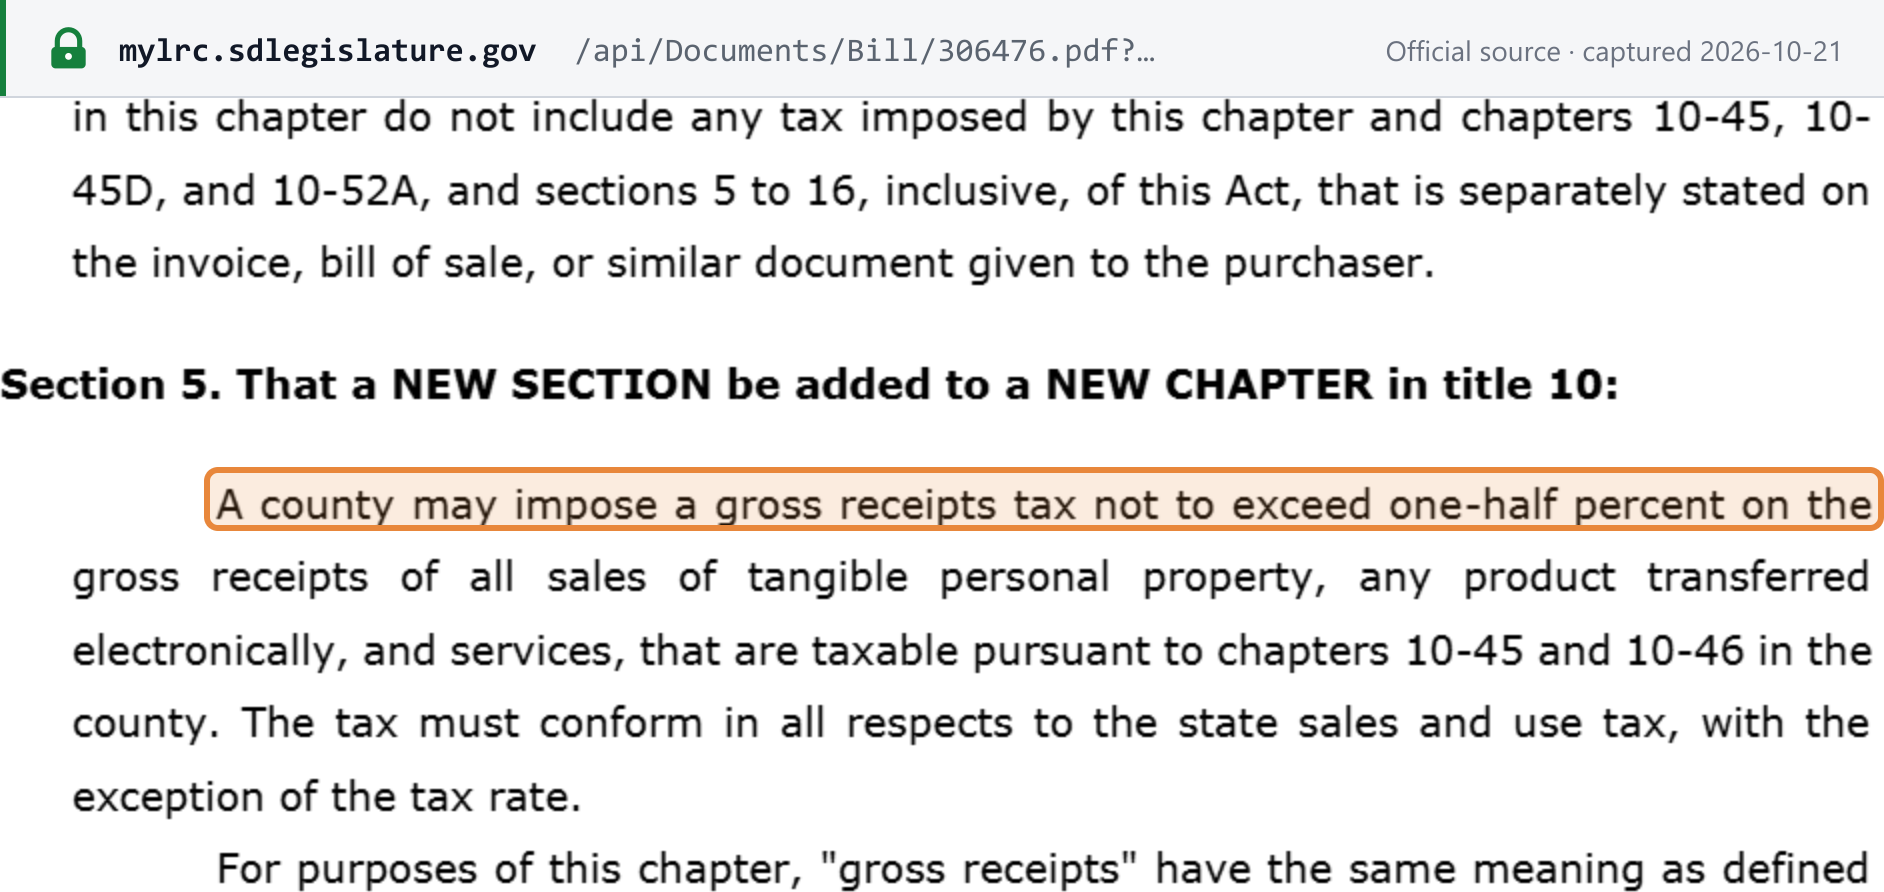 Source snapshot of the official page. Open full size ↗