Uzbekistan to refund VAT within three days for low-risk taxpayers from 1 January 2027 under Decree UP-95
- Jurisdiction
- Uzbekistan
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 19 May 2026
- Effective
- 1 January 2027
- Authority
- National Database of Legislation of the Republic of Uzbekistan (lex.uz)
- Systems
- Reporting, ERP
- Verified
- Fetched from official source · high confidence
Taxpayers classed as low tax risk with VAT negative differences from zero-rated supplies (exporters) or from acquiring real estate.
Exporters and real-estate purchasers should confirm risk-category status ahead of 1 January 2027 refund claims.
ReportingERP
Presidential Decree No. UP-95 of 19 May 2026 provides that from 1 January 2027 taxpayers classed as low tax risk have VAT negative differences arising from zero-rated supplies and from acquisition of real estate covered (refunded) within three days in an automated procedure; for certain categories of taxpayers the existing refund procedure is retained. The decree also lists a one-day VAT refund period as an administration target.
What changed in detail
Presidential Decree No. UP-95 of 19 May 2026 provides that from 1 January 2027 taxpayers classed as low tax risk have VAT negative differences arising from zero-rated supplies and from the acquisition of real estate covered (refunded) within three days, in an automated procedure. For certain categories of taxpayers the existing refund procedure is retained.
The decree also lists a one-day VAT refund period as an administration target.
What it means
The decree was issued in May 2026 but its refund rule starts on 1 January 2027, which is why it matters now. The three-day refund depends on the taxpayer’s tax-risk classification, so the benefit is not automatic for every exporter or real-estate buyer.
Exporters and real-estate purchasers should confirm their risk-category status with the tax authority before filing refund claims in 2027. The one-day period is a target in the decree, not a legal deadline; plan cash flow around the three-day rule.
Proof
начиная с 1 января 2027 года налогоплательщикам, отнесенным к низкому уровню налогового риска, покрытие (возврат) суммы отрицательной разницы по налогу на добавленную стоимость, образовавшейся в результате применения нулевой налоговой ставки и за счет приобретения недвижимого имущества, осуществляется в трехдневный срок в автоматизированном порядке.starting from 1 January 2027, for taxpayers classed as low tax risk, the coverage (refund) of the negative VAT difference arising from the application of the zero rate and from the acquisition of real estate is carried out within three days in an automated procedure.
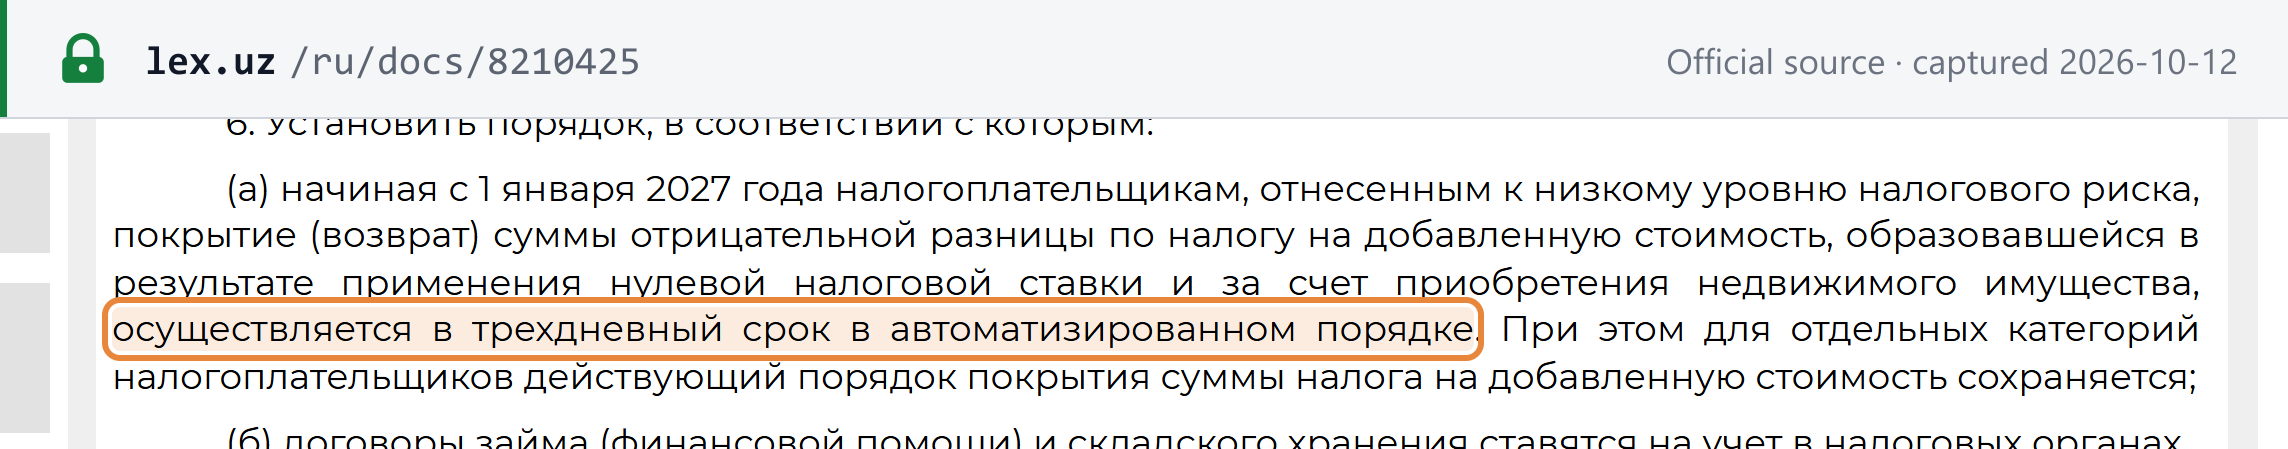 Source snapshot of the official page. Open full size ↗