Bulgaria compliance calendar

14 recurring Данък върху добавената стойност (VAT) and Данъчно-осигурителен процесуален кодекс obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Bulgaria rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Bulgaria applies one — 4 of 14 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Справка-декларация по ЗДДС with purchase and sales ledgers — monthly

Данък върху добавената стойност (VAT) · Monthly · return filing

14th of the month after the month ends Verified 2026-10-07
Who files
Every person registered for VAT in Bulgaria (registrations under arts. 96, 97а, 99 and 100); mandatory registration for established businesses whose calendar-year taxable turnover passes EUR 51,130
Notes
Every VAT-registered business in Bulgaria files monthly; there is no quarterly or annual option. The return goes in electronically together with the purchase and sales ledgers by the 14th of the following month, and is required even for a month with no supplies and nothing to pay. The VAT due is payable by the same day and counts as paid only once it reaches the revenue agency's account, so a transfer sent on the 14th can arrive late. When the 14th is a Saturday, Sunday or public holiday you have until the next working day: the October 2026 return is due on Monday 16 November.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 125, ал. 1–5 (деклариране) и чл. 87, ал. 2 (данъчен период) Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“Декларациите по ал. 1 и 2 и отчетните регистри по ал. 3 се подават до 14-о число включително на месеца, следващ данъчния период, за който се отнасят.”
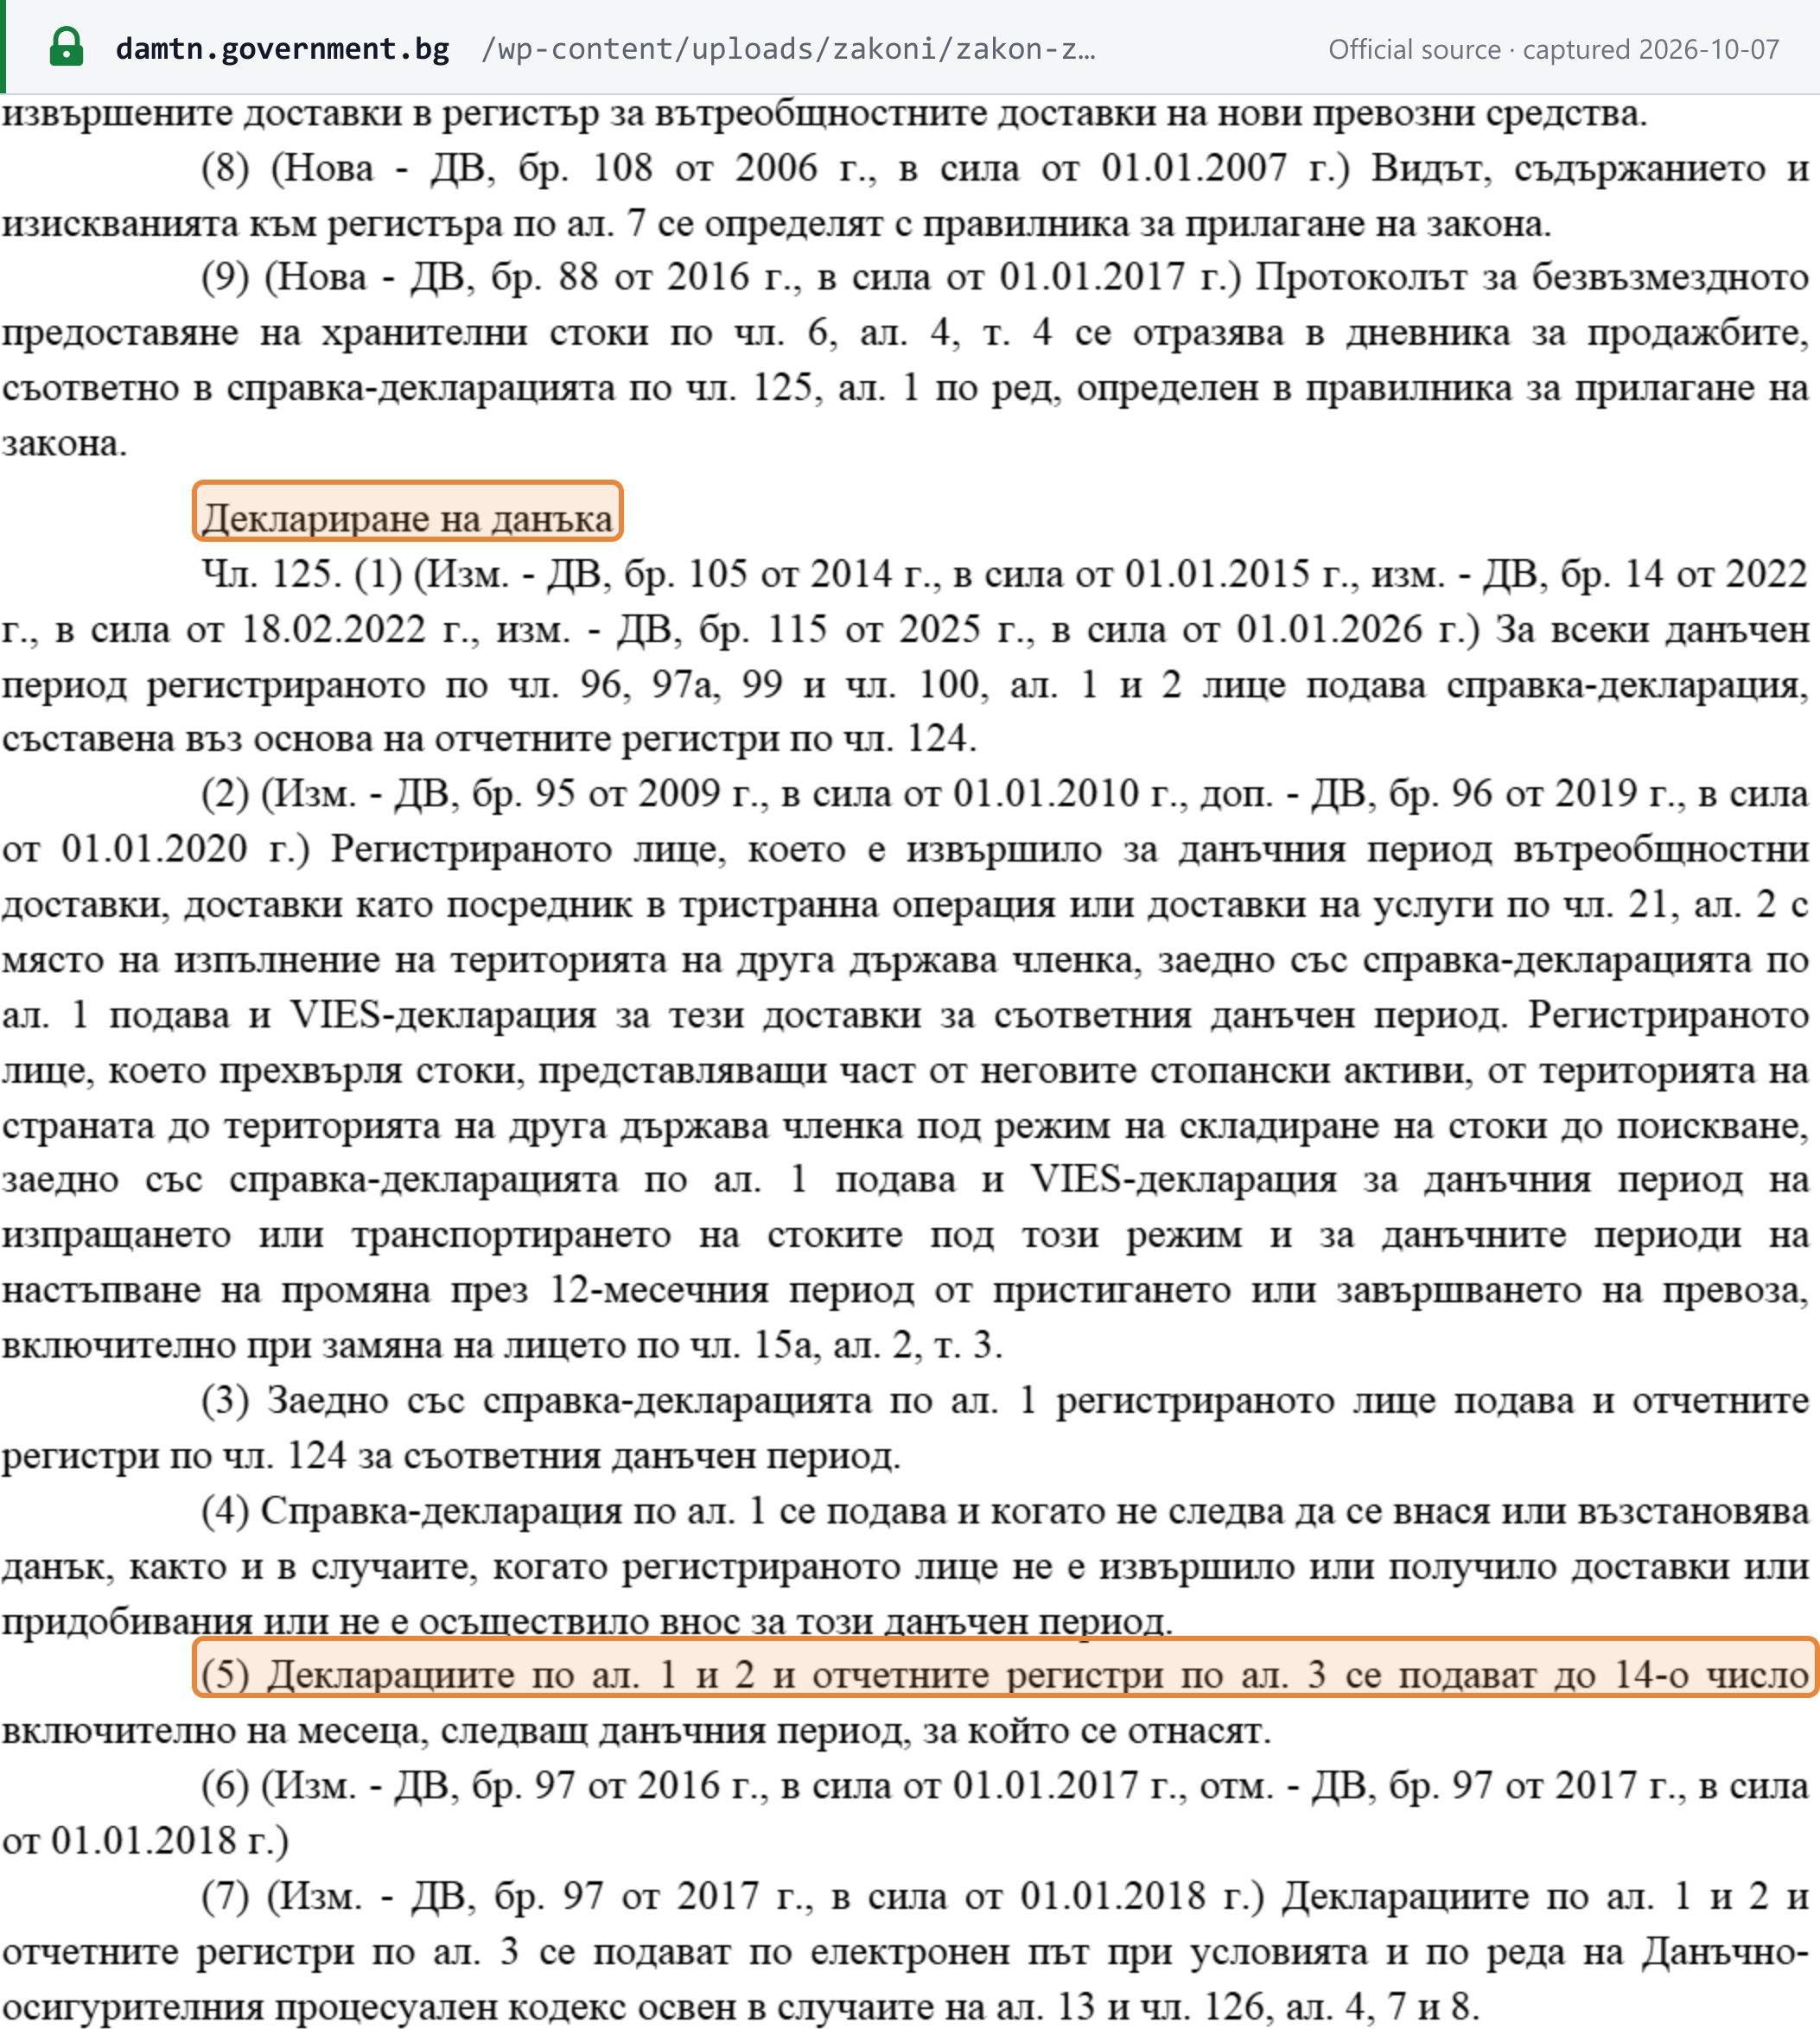
Screenshot of Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) showing the Справка-декларация по ЗДДС with purchase and sales ledgers — monthly deadline Open full size Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07
VIES-декларация (EC Sales List) — monthly

Данък върху добавената стойност (VAT) · Monthly · report / listing

14th of the month after the month ends Verified 2026-10-07
Who files
VAT-registered persons that in the month made intra-EU supplies of goods, acted as intermediary in a triangular operation, supplied B2B services taxed in another member state under art. 21(2), or moved goods under call-off stock arrangements
Notes
Owed only for a month in which you sold goods to a business in another EU country, acted as the middle party in a triangular deal, supplied B2B services taxed in another member state, or moved goods under a call-off stock arrangement. It goes in with that month's VAT return, so it shares the 14th and rolls forward with it off a weekend: the declaration for January 2027 is due on Monday 15 February. Bulgaria offers no quarterly option for this listing.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 125, ал. 2 и 5 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“Регистрираното лице, което е извършило за данъчния период вътреобщностни доставки, доставки като посредник в тристранна операция или доставки на услуги по чл. 21, ал. 2 с място на изпълнение на територията на друга държава членка, заедно със справка-декларацията по ал. 1 подава и VIES-декларация за тези доставки за съответния данъчен период.”
Screenshot of Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) showing the VIES-декларация (EC Sales List) — monthly deadline Open full size Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07
Регистър по чл. 124, ал. 7 — intra-EU supplies of new means of transport, quarterly

Данък върху добавената стойност (VAT) · Quarterly · report / listing

14th of the month after the quarter ends Verified 2026-10-07
Who files
VAT-registered persons that in the calendar quarter supplied new means of transport to buyers in other member states who are not registered for VAT
Notes
A niche duty for dealers who sell new cars, boats or aircraft to private buyers or other unregistered customers elsewhere in the EU. The register runs by calendar quarter, is filed electronically, and is due by the 14th of the month after the quarter ends; a 14th landing on a non-working day carries over to the next working day.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 125, ал. 9 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
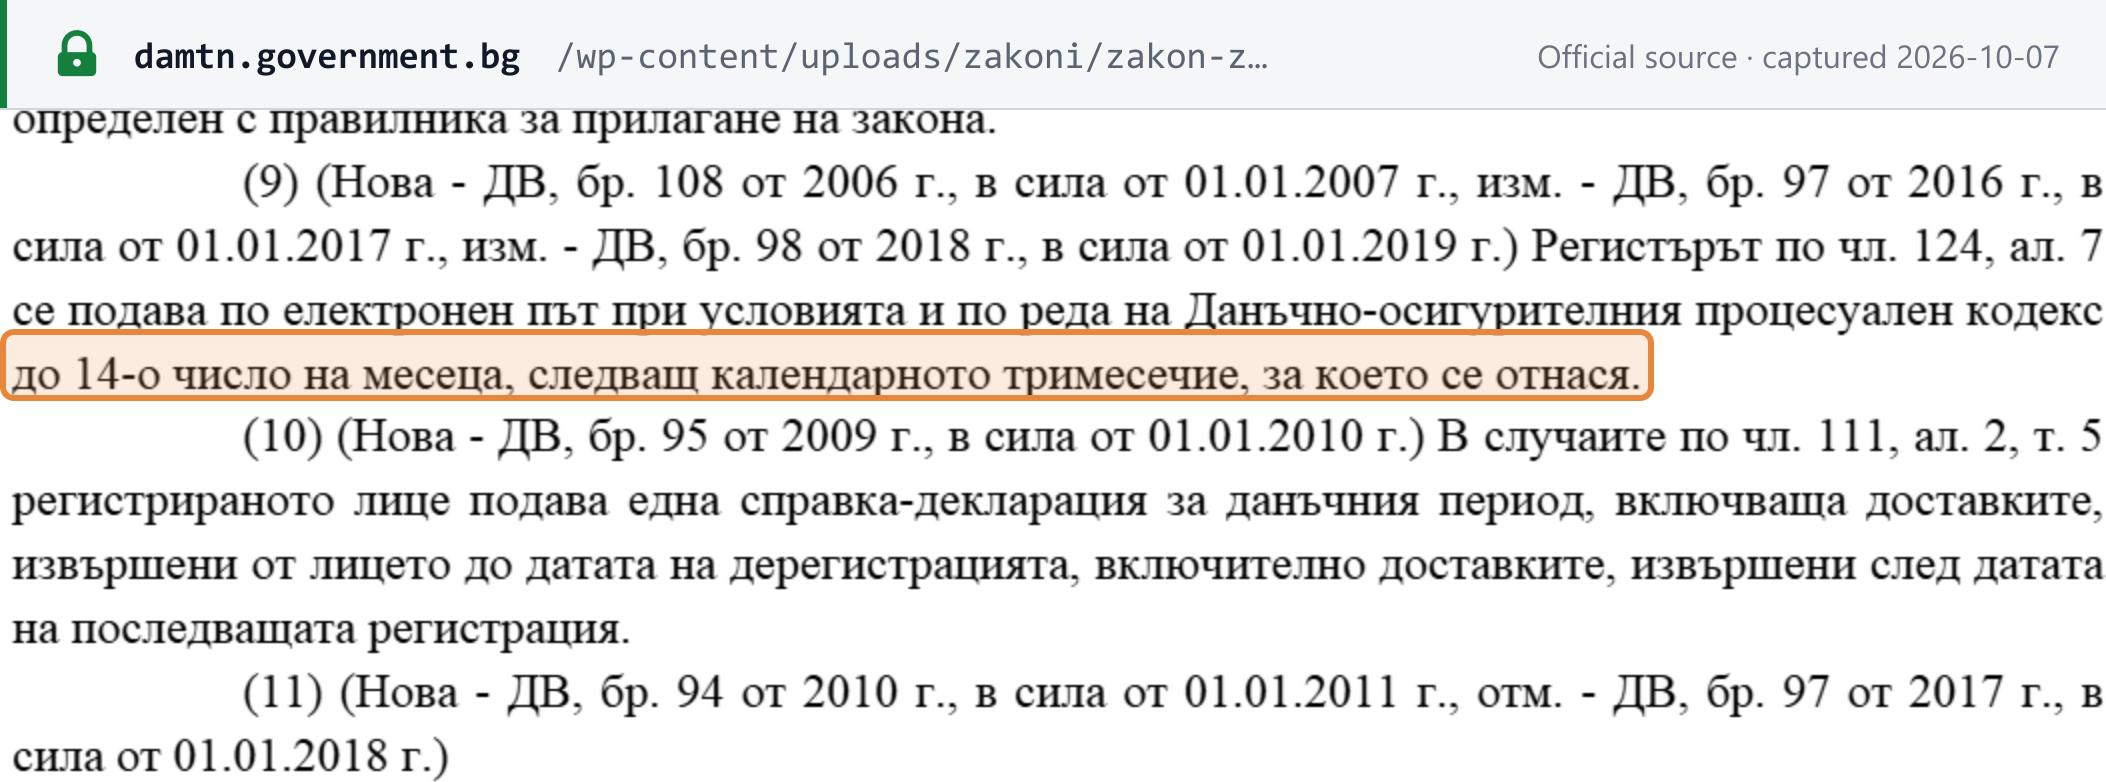
“Регистърът по чл. 124, ал. 7 се подава по електронен път при условията и по реда на Данъчно-осигурителния процесуален кодекс до 14-о число на месеца, следващ календарното тримесечие, за което се отнася.”
Screenshot of Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) showing the Регистър по чл. 124, ал. 7 — intra-EU supplies of new means of transport, quarterly deadline Open full size Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07
Справка-декларация за прилагане на специален режим — OSS Union and non-Union schemes, quarterly

Данък върху добавената стойност (VAT) — OSS · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-07
Who files
Businesses registered in Bulgaria for the Union scheme (art. 156: intra-EU distance sales of goods and B2C services taxed in other member states) or the non-Union scheme (art. 154: non-EU businesses supplying B2C services); EU-wide distance-sales threshold EUR 10,000
Notes
The Union scheme and the non-Union scheme are separate registrations, each with its own quarterly return, and the same deadline applies to both. Each return is due by the last day of the month after the quarter, together with payment of the tax in euro, and must be filed even for a quarter with no sales. Unlike Bulgaria's domestic deadlines, this one does not move off a weekend or holiday: the return for the third quarter of 2026 is due on Saturday 31 October, and the one for the fourth quarter on Sunday 31 January 2027.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 159, ал. 1, 4 и 11 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
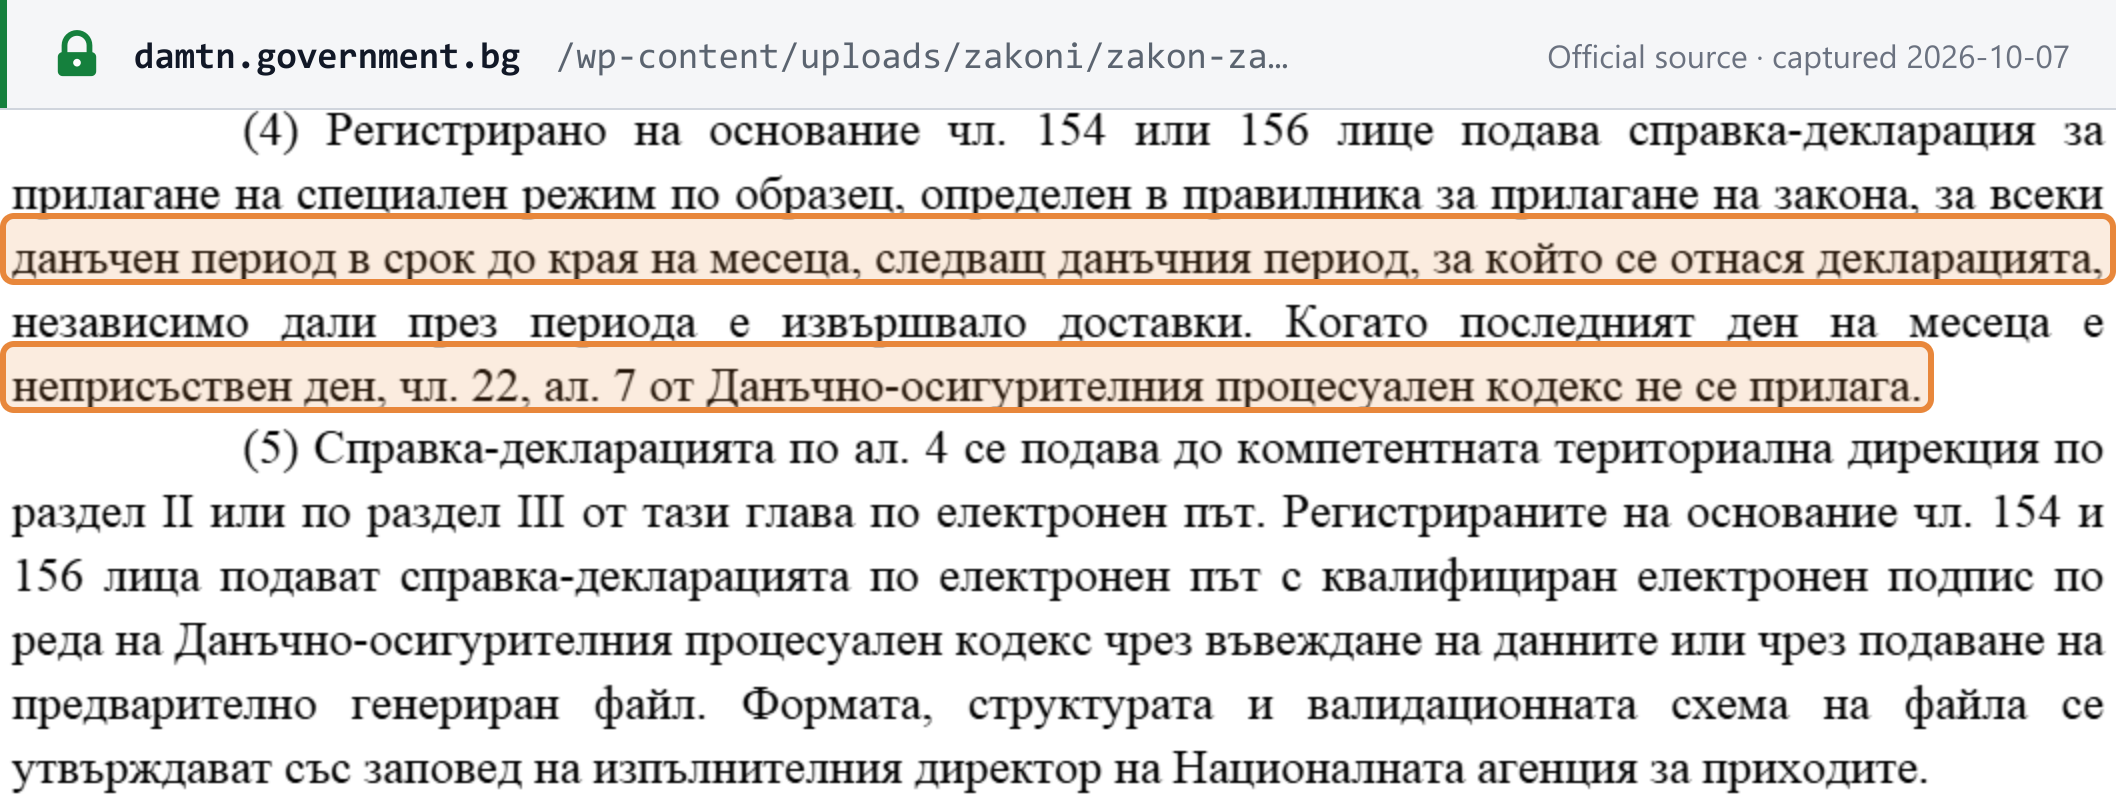
“Регистрирано на основание чл. 154 или 156 лице подава справка-декларация за прилагане на специален режим по образец, определен в правилника за прилагане на закона, за всеки данъчен период в срок до края на месеца, следващ данъчния период, за който се отнася декларацията, независимо дали през периода е извършвало доставки. Когато последният ден на месеца е неприсъствен ден, чл. 22, ал. 7 от Данъчно-осигурителния процесуален кодекс не се прилага.”
Screenshot of Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) showing the Справка-декларация за прилагане на специален режим — OSS Union and non-Union schemes, quarterly deadline Open full size Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07
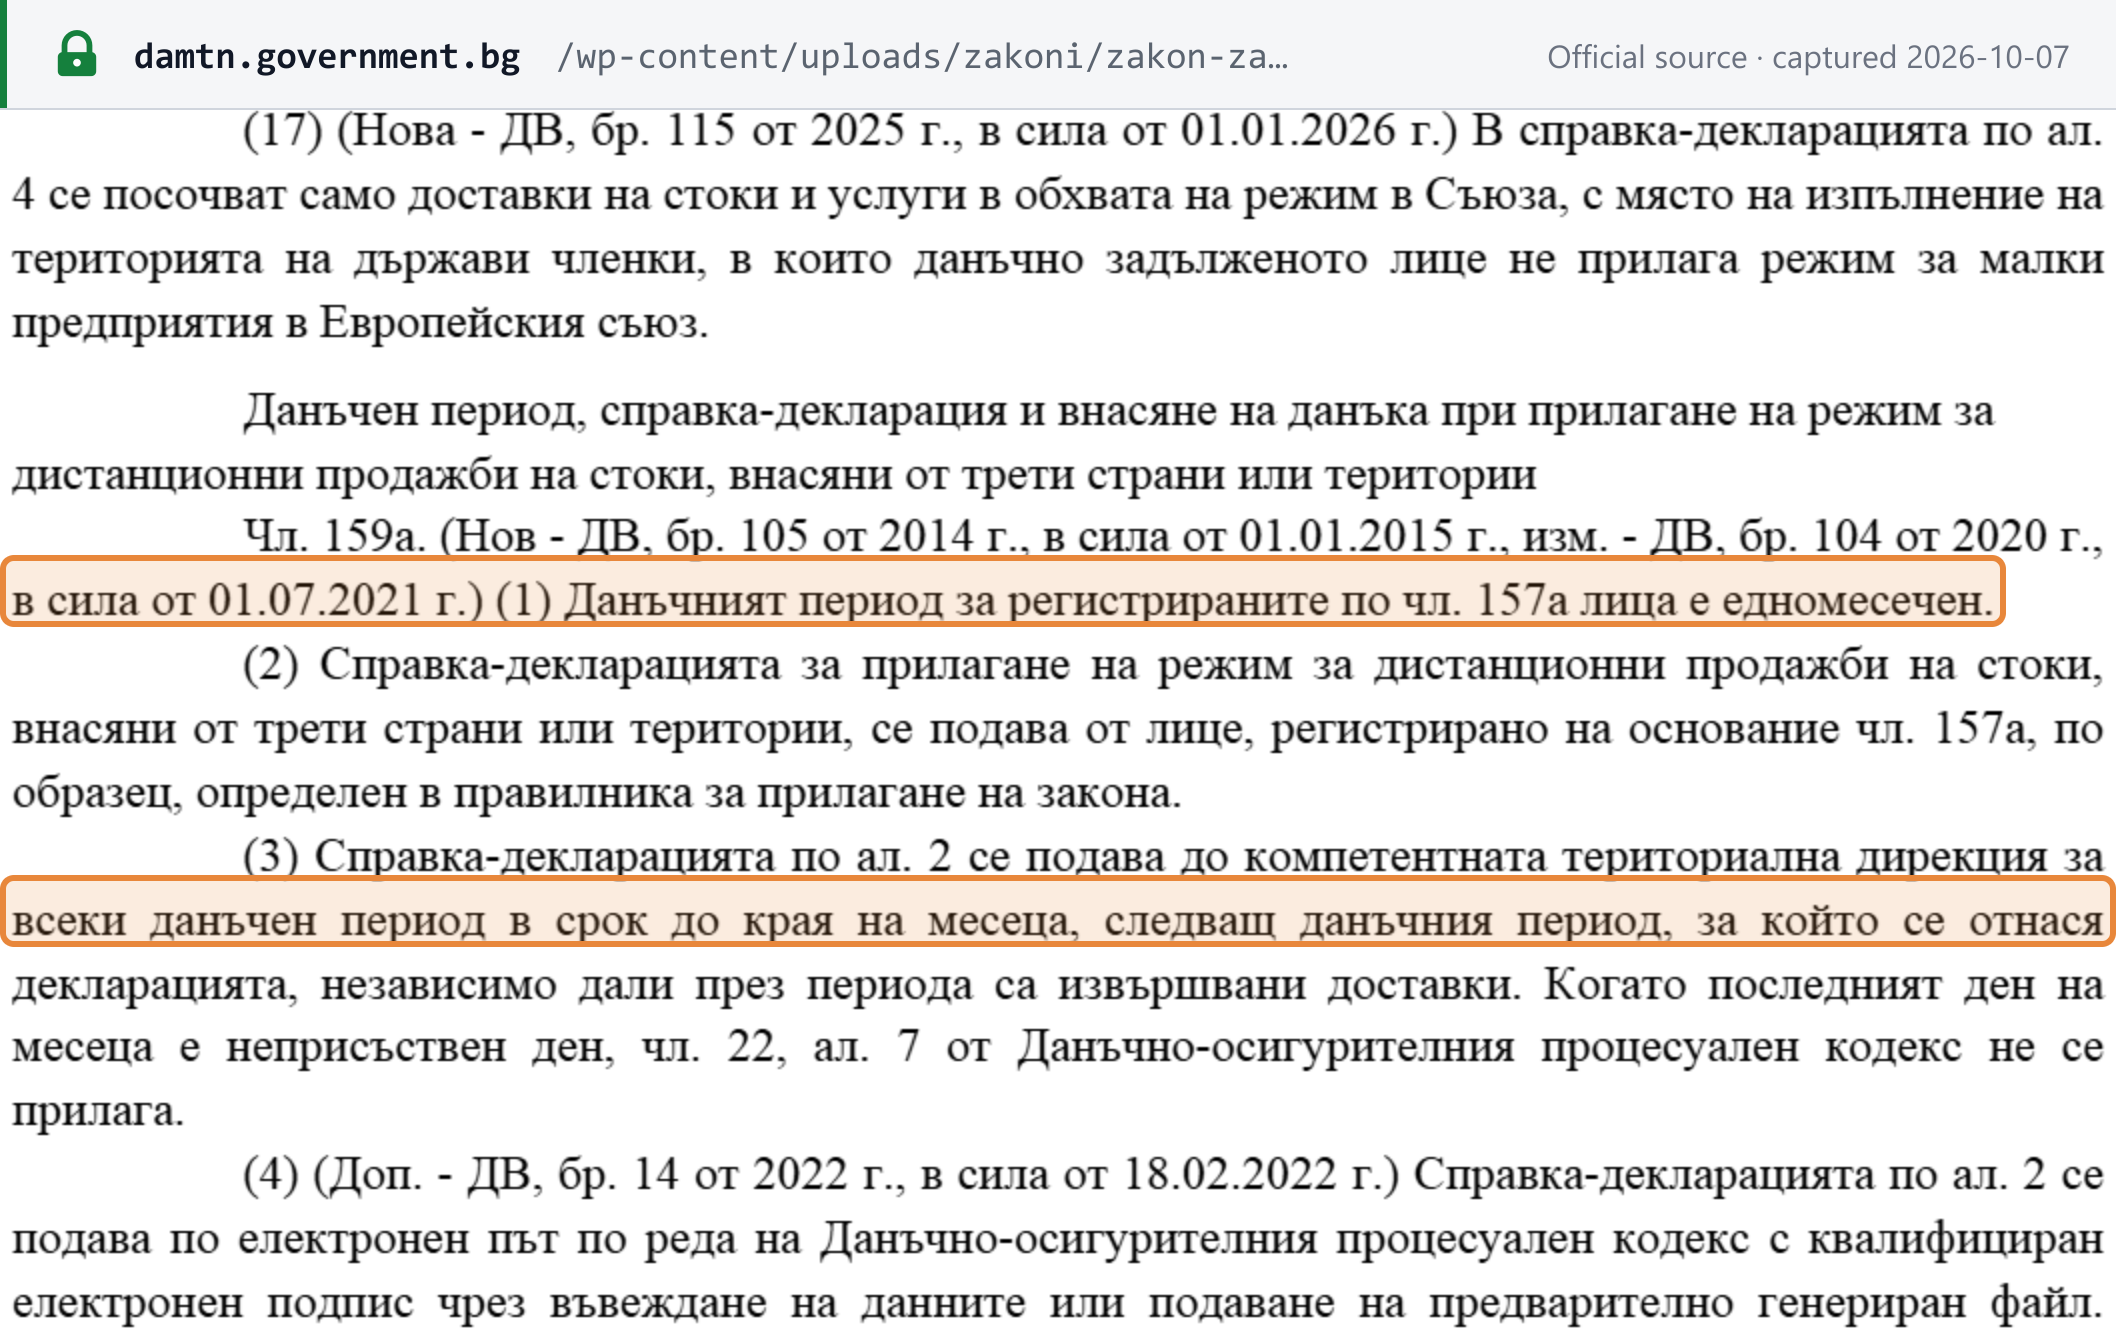
Справка-декларация — import scheme (IOSS), monthly

Данък върху добавената стойност (VAT) — IOSS · Monthly · return filing

last day of the month after the month ends Verified 2026-10-07
Who files
Sellers and electronic interfaces registered in Bulgaria under art. 157а for distance sales of goods imported from outside the EU in consignments of up to EUR 150, or their intermediaries
Notes
For sellers and marketplaces using the import scheme on low-value consignments. Each calendar month has its own return, due by the last day of the next month with the tax paid in euro by then; a nil return is required for a month with no sales. The Act says in terms that this date does not roll forward, so the return for January 2027 is due on Sunday 28 February 2027.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 159а, ал. 1, 3 и 11 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“Справка-декларацията по ал. 2 се подава до компетентната териториална дирекция за всеки данъчен период в срок до края на месеца, следващ данъчния период, за който се отнася декларацията, независимо дали през периода са извършвани доставки. Когато последният ден на месеца е неприсъствен ден, чл. 22, ал. 7 от Данъчно-осигурителния процесуален кодекс не се прилага.”
Screenshot of Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) showing the Справка-декларация — import scheme (IOSS), monthly deadline Open full size Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07
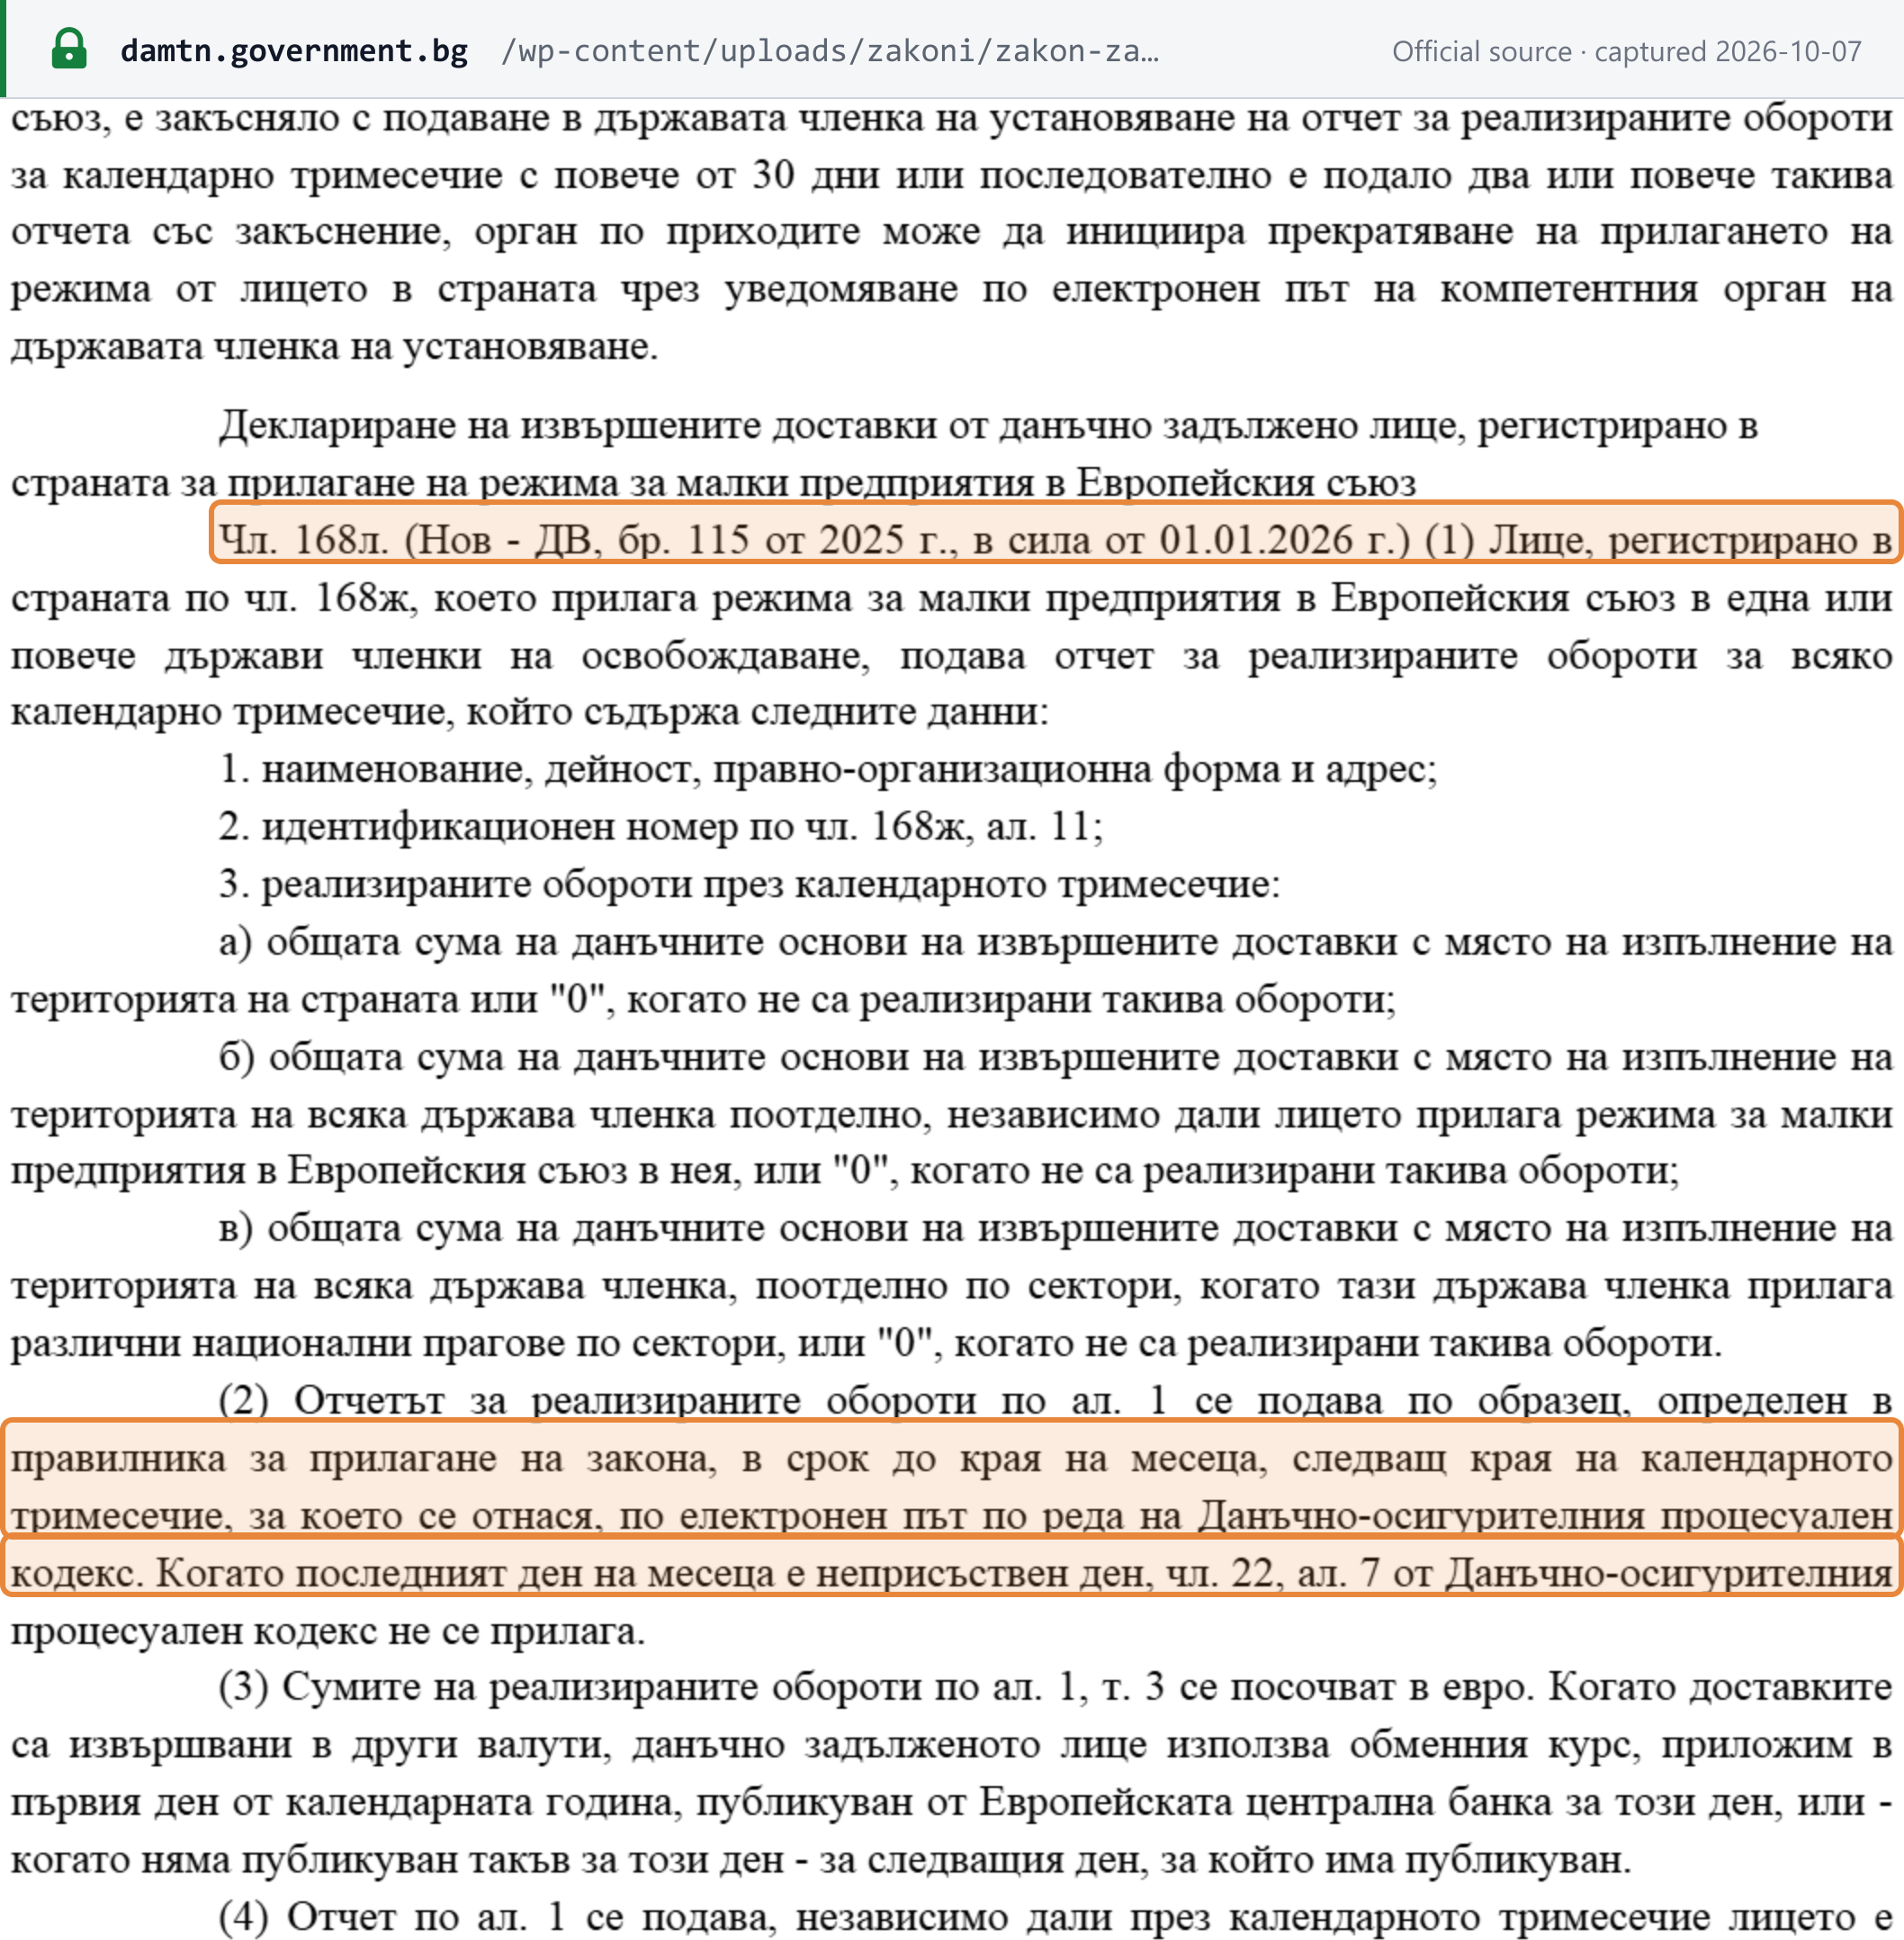
Отчет за реализираните обороти — EU SME scheme, quarterly

Данък върху добавената стойност (VAT) — режим за малки предприятия в ЕС · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-07
Who files
Businesses established in Bulgaria and registered under art. 168ж to use the EU small-enterprise exemption in one or more other member states (in force from 1 January 2026)
Notes
A Bulgarian business using the EU-wide small-enterprise exemption in other member states reports its turnover every calendar quarter, split by country and entered in euro, by the end of the following month. A report is still due for a quarter with no sales, with zeros entered. As with the One-Stop-Shop, a weekend does not buy extra time: the report for July to September 2027 is due on Sunday 31 October 2027.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 168л, ал. 1–4 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“Отчетът за реализираните обороти по ал. 1 се подава по образец, определен в правилника за прилагане на закона, в срок до края на месеца, следващ края на календарното тримесечие, за което се отнася, по електронен път по реда на Данъчно-осигурителния процесуален кодекс. Когато последният ден на месеца е неприсъствен ден, чл. 22, ал. 7 от Данъчно-осигурителния процесуален кодекс не се прилага.”
Screenshot of Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) showing the Отчет за реализираните обороти — EU SME scheme, quarterly deadline Open full size Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07
Стандартен одитен файл за данъчни цели (SAF-T) — monthly

Данъчно-осигурителен процесуален кодекс — SAF-T (all taxes) · Monthly · report / listing

last day of the month after the month ends Verified 2026-10-07
Who files
From 1 January 2026, large enterprises whose 2023 net sales exceeded BGN 300 million or whose 2023 net payments to the National Revenue Agency exceeded BGN 3.5 million; from 1 January 2027, large, medium and small enterprises meeting the same tests on 2024 figures; further cohorts in 2028, 2029 and 2030
Notes
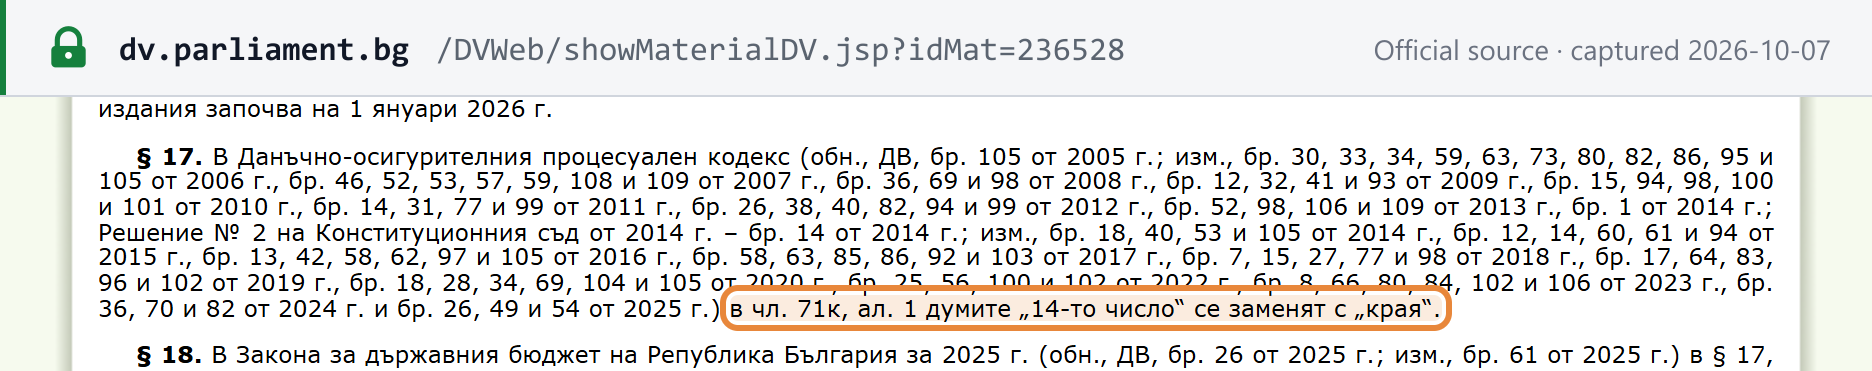
A monthly accounting-data file under the tax procedure code, covering all taxes, so it binds companies in scope whether or not they are VAT-registered. Each month's file is due by the end of the following month, moving to the next working day off a weekend or holiday: the March 2027 file is due on Wednesday 5 May, after the Easter and Labour Day holidays. Companies joining under the phase-in file from their first month, with no six-month grace period, but may correct files during their first 12 months. Data on fixed assets goes in with the annual corporate tax return instead.
Source
Закон за изменение и допълнение на Закона за въвеждане на еврото в Република България, ДВ бр. 65 от 08.08.2025 г. — § 17 (чл. 71к, ал. 1 от Данъчно-осигурителния процесуален кодекс) Държавен вестник — Народно събрание на Република България
See the source text
“в чл. 71к, ал. 1 думите „14-то число“ се заменят с „края“.”
Screenshot of Държавен вестник — Народно събрание на Република България showing the Стандартен одитен файл за данъчни цели (SAF-T) — monthly deadline Open full size Captured from Държавен вестник — Народно събрание на Република България on 2026-10-07

Заявление за регистрация по ЗДДС — on exceeding the EUR 51,130 threshold

Данък върху добавената стойност (VAT) · One-off · registration

within 7 days of the date taxable turnover in the calendar year exceeds the national threshold of EUR 51,130, or the Union threshold (art. 96(1)–(2)) Verified 2026-10-07
Who files
Taxable persons established in Bulgaria whose taxable turnover in the calendar year exceeds EUR 51,130, and EU-established users of the SME scheme in Bulgaria once they pass that figure or EUR 100,000 of EU-wide turnover
Notes
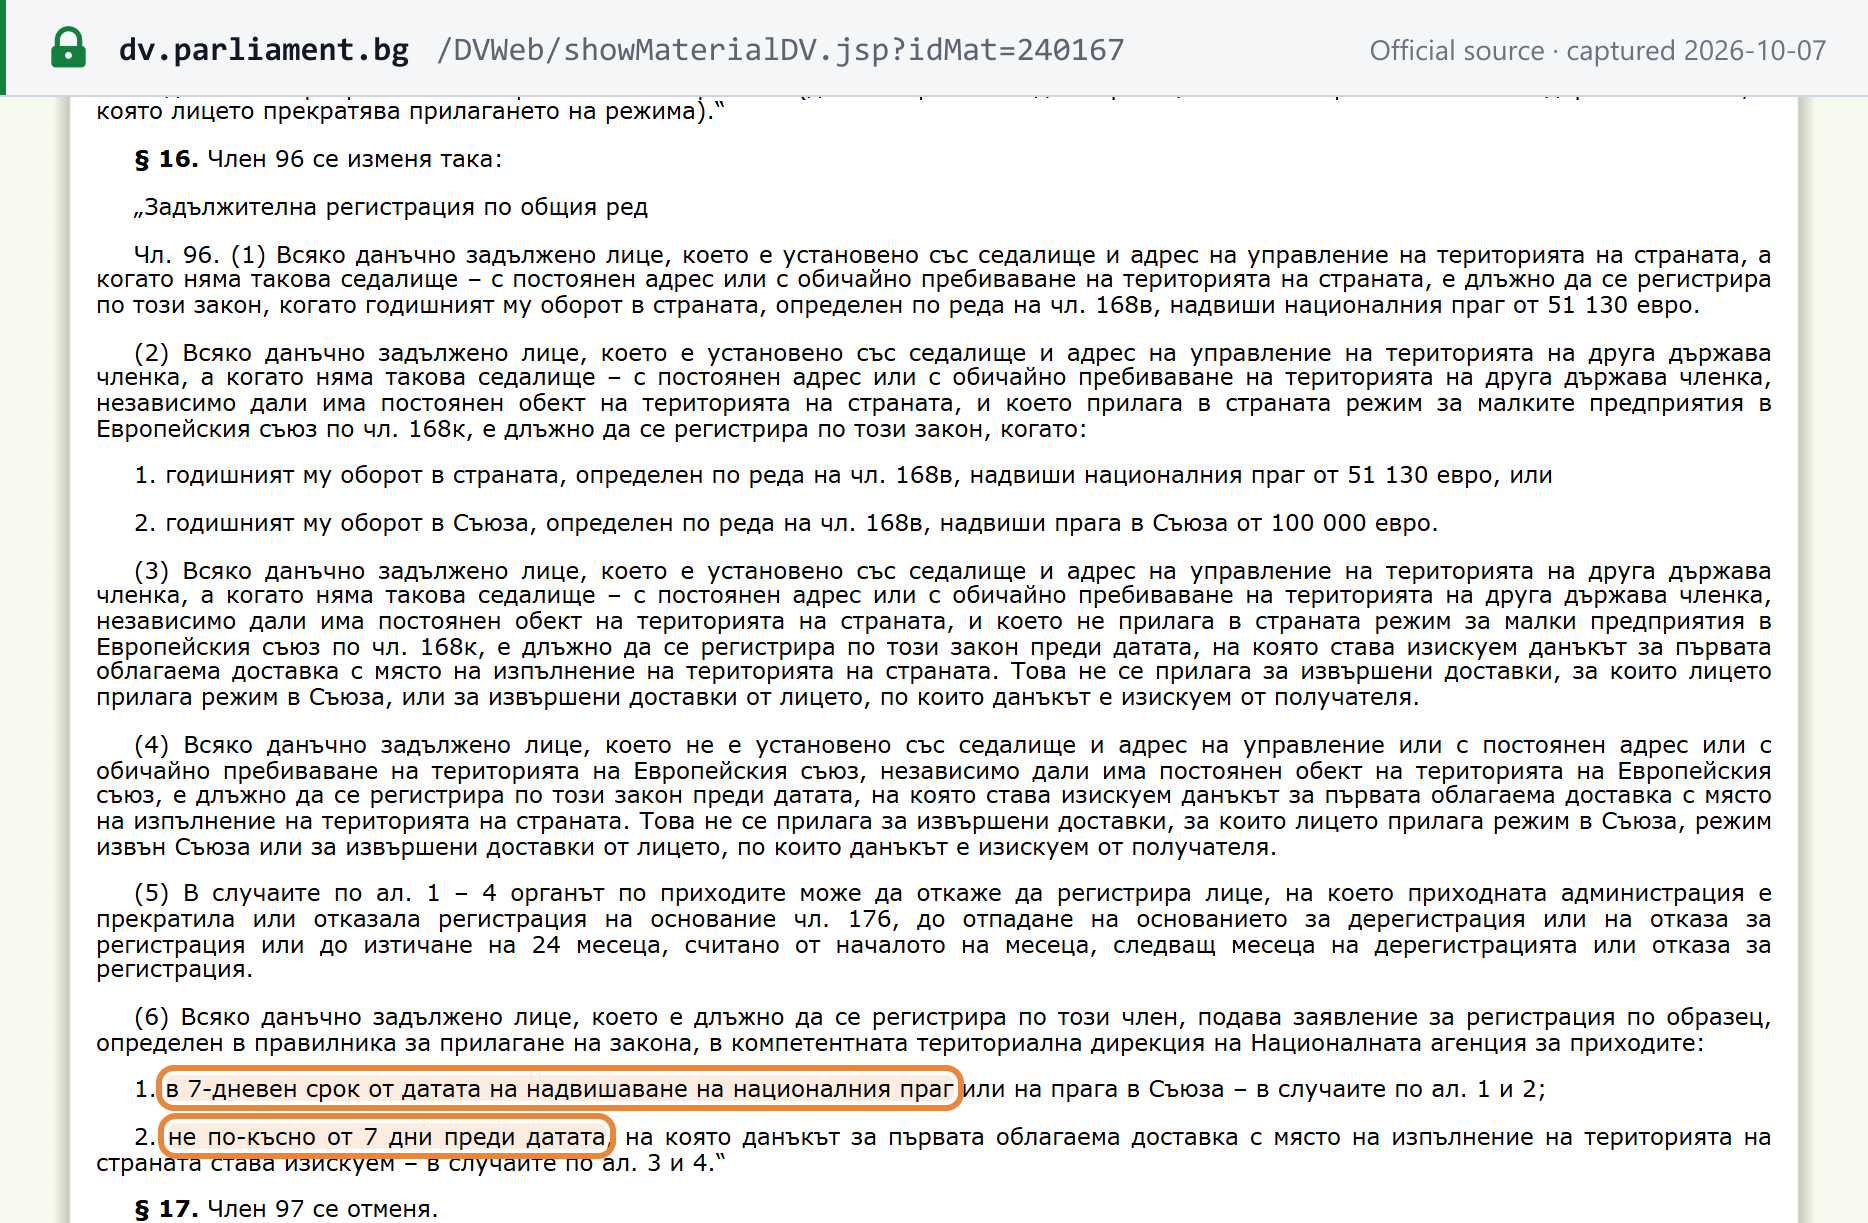
Seven calendar days from the date your taxable turnover for the calendar year passes EUR 51,130 — not working days, and not the end of the month. Registration counts from the day after the threshold is crossed, so VAT is chargeable on your sales from then on even though the registration decision has not yet been issued. An EU business using the small-enterprise exemption in Bulgaria has the same 7 days once it passes the Bulgarian figure or EUR 100,000 of EU-wide turnover. The threshold has been set in euro since Bulgaria adopted the euro on 1 January 2026.
Source
Закон за изменение и допълнение на Закона за данък върху добавената стойност, ДВ бр. 115 от 30.12.2025 г. — § 16 (нов чл. 96, ал. 6) Държавен вестник — Народно събрание на Република България
See the source text
“1. в 7-дневен срок от датата на надвишаване на националния праг или на прага в Съюза – в случаите по ал. 1 и 2;”
Screenshot of Държавен вестник — Народно събрание на Република България showing the Заявление за регистрация по ЗДДС — on exceeding the EUR 51,130 threshold deadline Open full size Captured from Държавен вестник — Народно събрание на Република България on 2026-10-07

Заявление за регистрация по ЗДДС — businesses not established in Bulgaria

Данък върху добавената стойност (VAT) · One-off · registration

at least 7 days before the date VAT on the first taxable supply with place of supply in Bulgaria becomes chargeable (art. 96(3)–(4)) Verified 2026-10-07
Who files
Taxable persons not established in Bulgaria (EU businesses outside the SME scheme, and non-EU businesses) making taxable supplies with place of supply in Bulgaria, whatever their turnover
Notes
A foreign business has no turnover threshold to wait for. It must apply at least 7 days before the VAT on its first taxable supply in Bulgaria becomes chargeable, which in practice means registering before trading starts. Sales declared under the Union One-Stop-Shop scheme (or, for a business established outside the EU, the non-Union scheme), and supplies on which the Bulgarian customer accounts for the VAT, do not trigger this duty; sales under the import scheme do.
Source
Закон за изменение и допълнение на Закона за данък върху добавената стойност, ДВ бр. 115 от 30.12.2025 г. — § 16 (нов чл. 96, ал. 6, т. 2) Държавен вестник — Народно събрание на Република България
See the source text
“2. не по-късно от 7 дни преди датата, на която данъкът за първата облагаема доставка с място на изпълнение на територията на страната става изискуем – в случаите по ал. 3 и 4.”
Screenshot of Държавен вестник — Народно събрание на Република България showing the Заявление за регистрация по ЗДДС — businesses not established in Bulgaria deadline Open full size Captured from Държавен вестник — Народно събрание на Република България on 2026-10-07

Заявление за регистрация по чл. 97а — services received from abroad or supplied into the EU

Данък върху добавената стойност (VAT) · One-off · registration

at least 7 days before the date VAT on the supply becomes chargeable, by advance payment or chargeable event (art. 97а(4)) Verified 2026-10-07
Who files
Taxable persons not otherwise VAT-registered in Bulgaria that receive services on which they owe Bulgarian VAT as recipient, or supply B2B services with place of supply in another member state (art. 97а(1)–(2))
Notes
A small business below the main threshold still needs a Bulgarian VAT number for cross-border services: when it buys services from a foreign supplier on which it must self-account for the VAT, or sells B2B services taxed in another EU country. The application is due at least 7 days before the VAT on that supply becomes chargeable, and an advance payment counts, so paying a deposit can bring the deadline forward.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 97а, ал. 4 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“За лицата по ал. 1 и 2 възниква задължение за подаване на заявление за регистрация по този закон не по-късно от 7 дни преди датата, на която данъкът за доставката става изискуем (авансово плащане или данъчно събитие)”
Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07
Заявление за регистрация по чл. 99 — intra-EU acquisitions above EUR 10,000

Данък върху добавената стойност (VAT) · One-off · registration

at least 7 days before the chargeable event of the intra-EU acquisition with which calendar-year acquisitions exceed EUR 10,000 (art. 99(3)) Verified 2026-10-07
Who files
Persons not registered for VAT (including non-taxable legal persons) whose taxable intra-EU acquisitions of goods in the calendar year will exceed EUR 10,000
Notes
An unregistered business or public body buying goods from other EU countries must apply no later than 7 days before the purchase that takes its yearly total of such acquisitions past EUR 10,000 — so the purchase has to be foreseen, not discovered afterwards. Goods moved into Bulgaria under a call-off stock arrangement carry their own 7-day advance duty.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 99, ал. 3 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“За лицата по ал. 1 възниква задължение за подаване на заявление за регистрация по този закон не по-късно от 7 дни преди датата на възникване на данъчното събитие за придобиването, с което общата стойност на облагаемите вътреобщностни придобивания надвиши 10 000 евро.”
Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07
Заявление за актуализиране — EU SME scheme, on exceeding a national threshold

Данък върху добавената стойност (VAT) — режим за малки предприятия в ЕС · One-off · registration

within 15 business days of the date turnover exceeds the national threshold in Bulgaria or in a member state of exemption (art. 168з(1)(1)) Verified 2026-10-07
Who files
Businesses established in Bulgaria using the EU small-enterprise exemption in other member states (art. 168ж) whose turnover passes the national threshold in Bulgaria or in a member state of exemption
Notes
Once your turnover passes the exemption threshold in Bulgaria or in a member state where you use the exemption, you have 15 working days, roughly three calendar weeks, to update your notification. Passing EUR 100,000 of EU-wide turnover triggers a separate notice on the same 15-working-day clock.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 168з, ал. 2 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“В случаите по ал. 1, т. 1 срокът за подаване на заявлението за актуализиране е до 15 работни дни от датата на надвишаване на националния праг в страната или на държавата членка на освобождаване.”
Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07

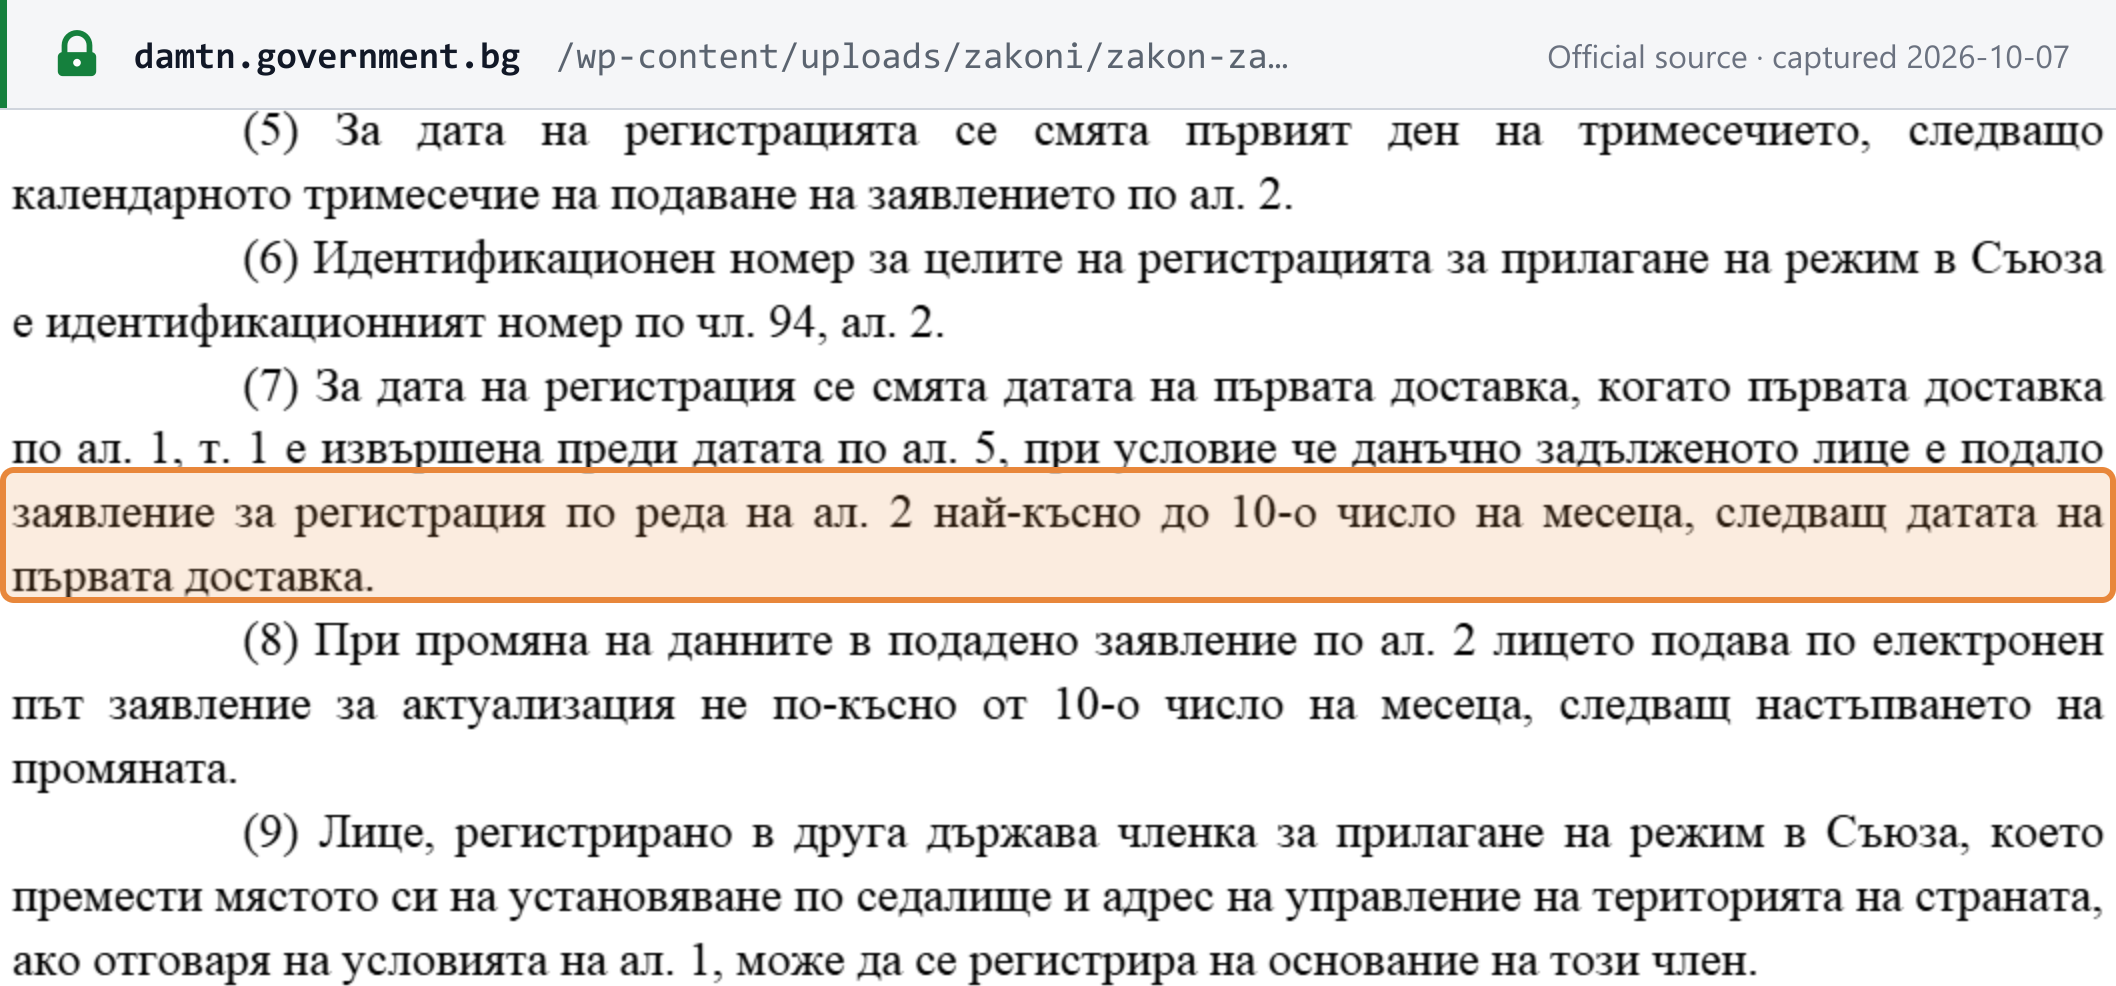
Заявление за регистрация за режим в Съюза / режим извън Съюза (OSS) — from the first supply

Данък върху добавената стойност (VAT) — OSS · One-off · registration

within 10 days of the end of the calendar month in which the first supply under the scheme was made (art. 156(7); art. 154(7) for the non-Union scheme) Verified 2026-10-07
Who files
Businesses joining the Union or non-Union One-Stop-Shop scheme with Bulgaria as member state of identification after already making their first supply under it — not the import scheme
Notes
A One-Stop-Shop registration normally takes effect from the first day of the quarter after you apply. If you have already made your first qualifying sale, the scheme can cover it from that sale, provided the application is in by the 10th of the month following it. The non-Union scheme works the same way; the import scheme is opt-in and has no such deadline.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 156, ал. 5 и 7 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“За дата на регистрация се смята датата на първата доставка, когато първата доставка по ал. 1, т. 1 е извършена преди датата по ал. 5, при условие че данъчно задълженото лице е подало заявление за регистрация по реда на ал. 2 най-късно до 10-о число на месеца, следващ датата на първата доставка.”
Screenshot of Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) showing the Заявление за регистрация за режим в Съюза / режим извън Съюза (OSS) — from the first supply deadline Open full size Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07

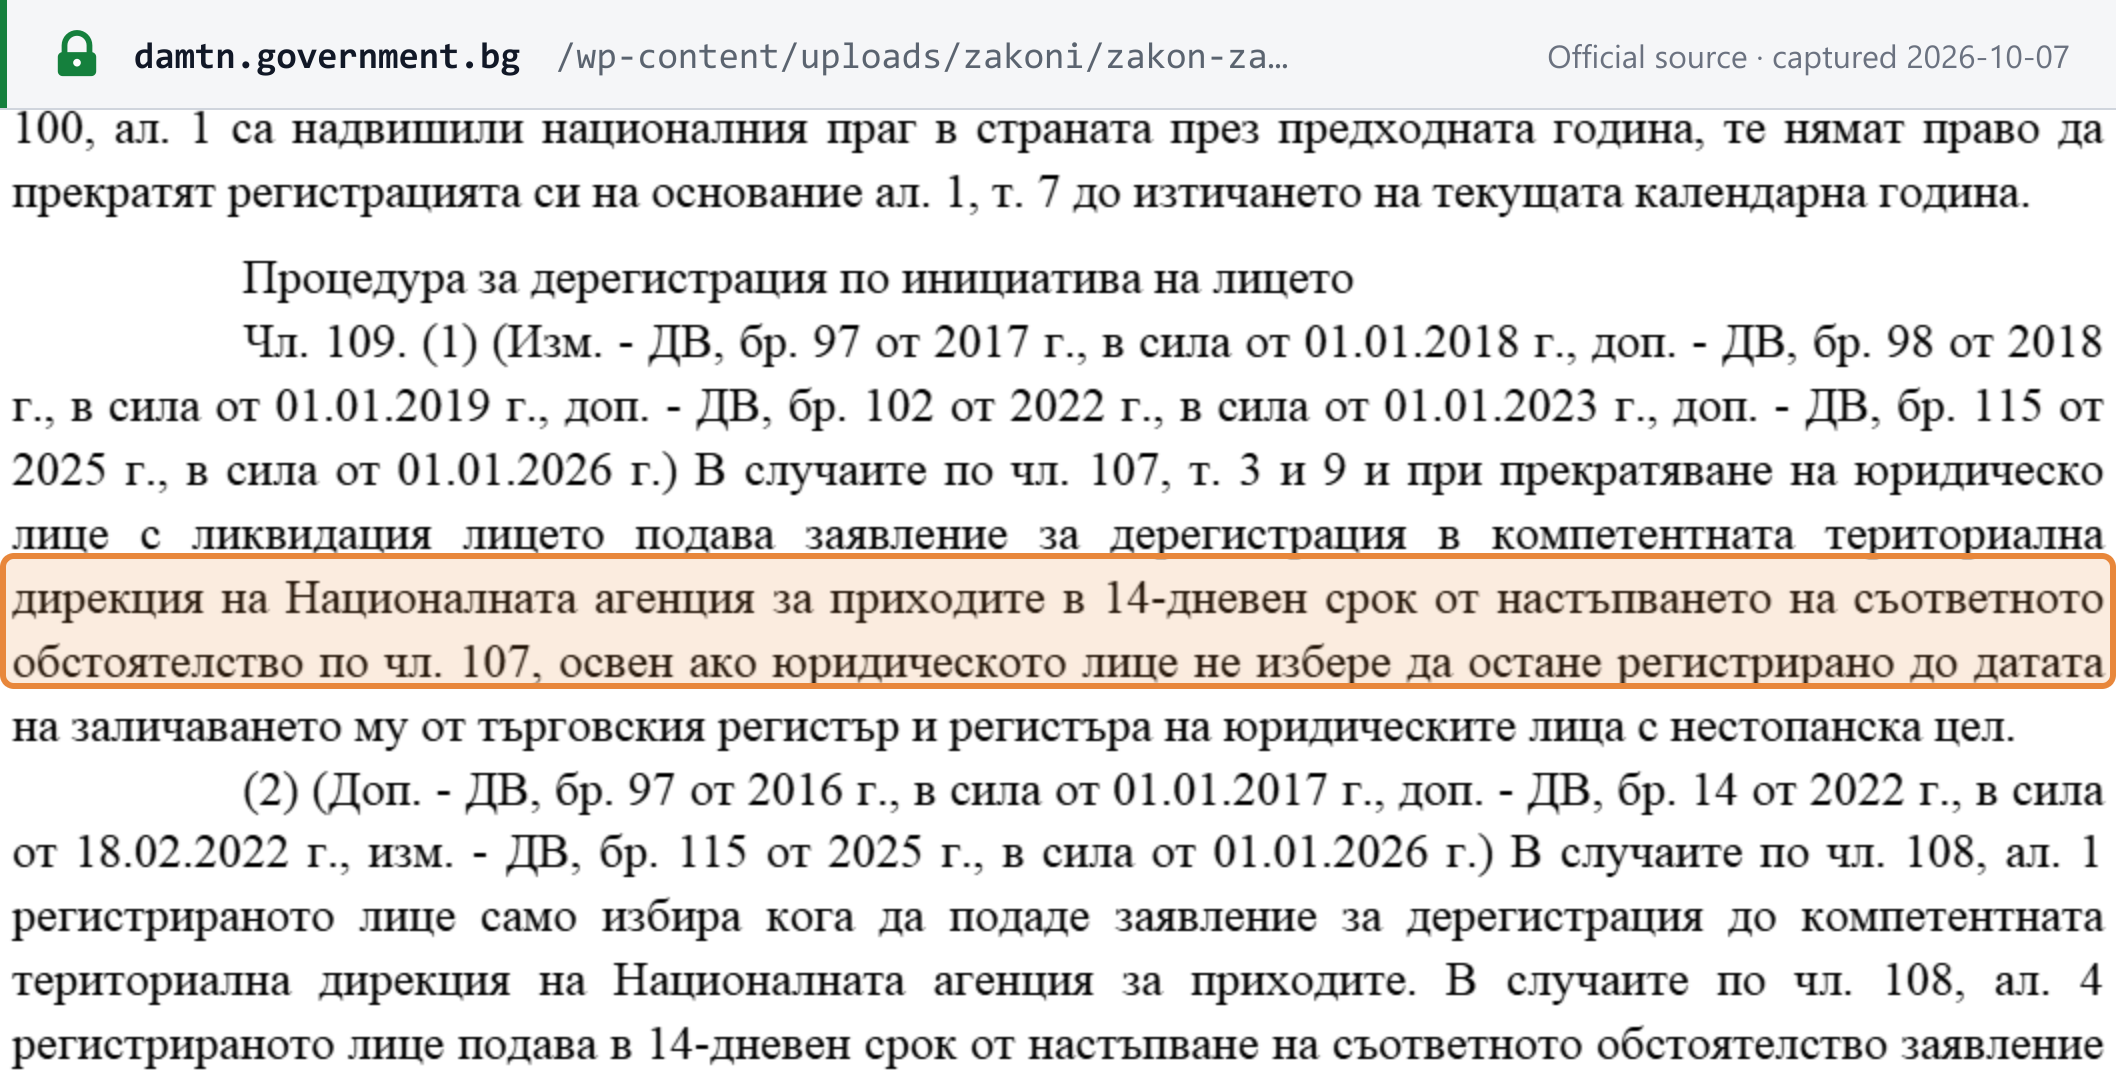
Заявление за дерегистрация — mandatory cases

Данък върху добавената стойност (VAT) · One-off · registration

within 14 days of the circumstance under art. 107 (striking-off, dissolution) or the start of liquidation Verified 2026-10-07
Who files
Registered sole traders struck off the register, foreign-established registrants that have been dissolved, and legal persons entering liquidation (art. 107, items 3 and 9; art. 109(1))
Notes
Fourteen days to apply for deregistration after a sole trader is struck off, a foreign-established registrant is dissolved, or a company goes into liquidation; a company in liquidation may instead choose to stay registered until it is removed from the register. Final-period tax may be paid by the end of the month after that return was due. A business registered here without being established in Bulgaria that moves to selling only under a One-Stop-Shop or import-scheme registration in another member state also has 14 days to apply. Other voluntary deregistrations have no deadline, but a business that passed the threshold last year cannot deregister before this year ends.
Source
Закон за данък върху добавената стойност (ЗДДС) — чл. 109, ал. 1 Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026)
See the source text
“В случаите по чл. 107, т. 3 и 9 и при прекратяване на юридическо лице с ликвидация лицето подава заявление за дерегистрация в компетентната териториална дирекция на Националната агенция за приходите в 14-дневен срок от настъпването на съответното обстоятелство по чл. 107, освен ако юридическото лице не избере да остане регистрирано до датата на заличаването му от търговския регистър и регистъра на юридическите лица с нестопанска цел.”
Screenshot of Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) showing the Заявление за дерегистрация — mandatory cases deadline Open full size Captured from Държавна агенция за метрологичен и технически надзор (consolidated text, Ciela, exported 09.07.2026) on 2026-10-07

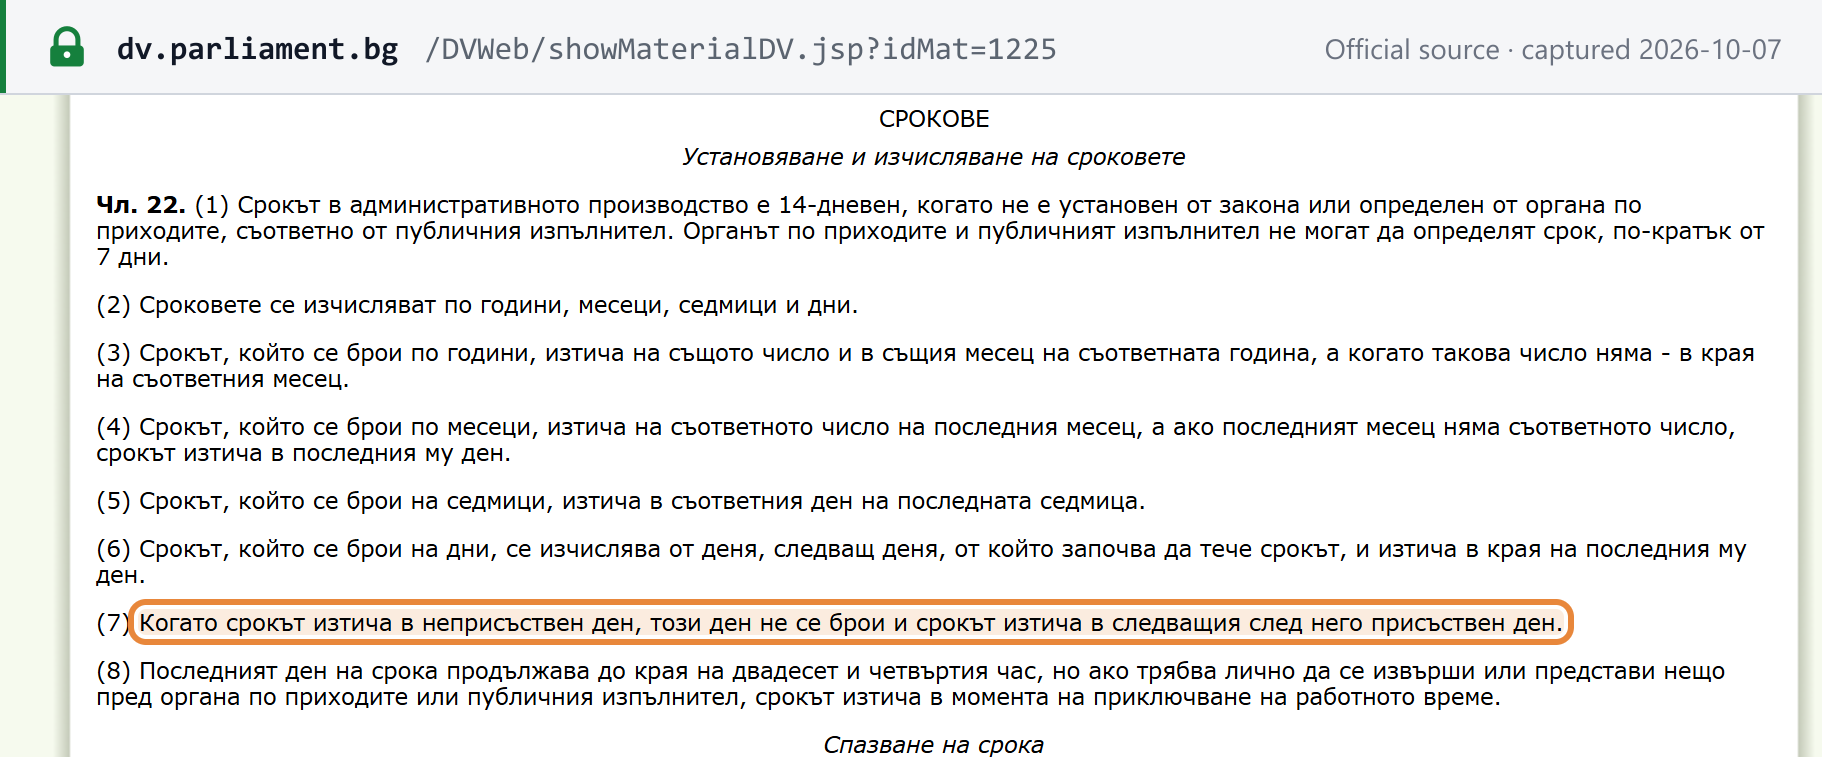
Deadlines that fall on a Saturday, Sunday or public holiday move to the next working day, payments included, except for the One-Stop-Shop, import-scheme and EU small-business returns, which stand on the day itself. Holidays follow the Labour Code, including the substitute working days it creates. VAT is paid by the return date and there is no annual return. A draft bill would raise the registration threshold and bring in e-invoicing from 2028; it is not law. Not shown: VAT owed by unregistered buyers of new vehicles within 14 days of the end of the period in which it became due, and notices to leave the One-Stop-Shop or import scheme. Excise and insurance premium tax are not yet covered.

“Когато срокът изтича в неприсъствен ден, този ден не се брои и срокът изтича в следващия след него присъствен ден.”
Screenshot of the official source stating the rule that governs Bulgaria's deadlines
Данъчно-осигурителен процесуален кодекс, ДВ бр. 105 от 29.12.2005 г. — чл. 22, ал. 7 — Държавен вестник — Народно събрание на Република България, captured 2026-10-07

What this calendar does not list

  • Not applicable Annual or reconciliation return — Bulgaria has no annual VAT return and no annual reconciliation return. The VAT Act sets a single domestic tax period, the calendar month, for every registered person (art. 87(2): "Данъчният период е едномесечен за всички регистрирани лица и съвпада с календарния месец освен в случаите по глава осемнадесета."), and art. 125 provides only the per-period return; the annual pro-rata adjustment of input tax is made inside a periodic return. Tested against the consolidated Act current to State Gazette No. 115 of 2025.
  • Not applicable E-invoicing / e-reporting cycle — No e-invoicing or e-reporting mandate is in force or enacted. An electronic invoice needs the recipient's consent (VAT Act art. 114(9)) and no provision requires invoices to be sent to the National Revenue Agency. A Ministry of Finance draft published for consultation in September 2026 would introduce clearance of structured invoices from 1 January 2028, invoice by invoice rather than on a periodic cycle; it is not law and has not been adopted by the Council of Ministers. Revisit if it is.

About this calendar

Which Bulgaria tax deadlines does this calendar cover?

14 recurring indirect-tax obligations — Данък върху добавената стойност (VAT) and Данъчно-осигурителен процесуален кодекс returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-07). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.