MWST-Abrechnung — quarterly VAT return and payment
Mehrwertsteuer (MWST / VAT) · Quarterly · return filing
29th of the 2nd month after the quarter ends — but the 28th in February, and the 30th in May Verified 2026-10-15- Who files
- Every VAT-registered business by default (effective method, and the flat-tax-rate method for public bodies and associations), unless it uses the net tax rate method or has been authorised to file monthly or annually; registration threshold CHF 100,000 of worldwide turnover a year
- Notes
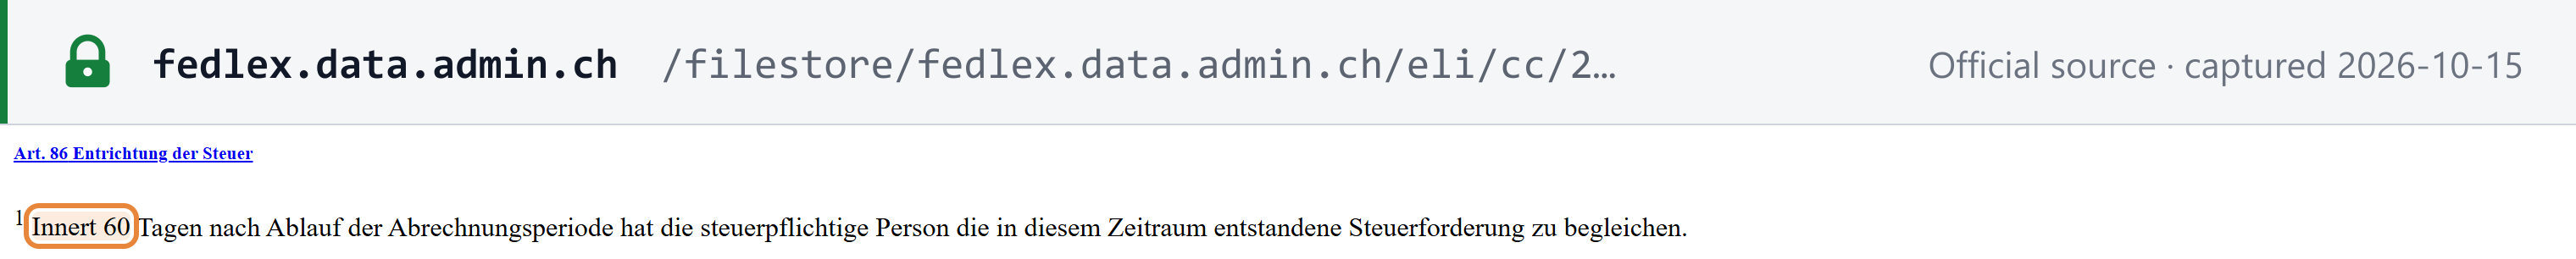
- File the return and pay the VAT within 60 days of each quarter: by 30 May, 29 August, 29 November and 28 February. Several of these fall on a Sunday in the coming year (29 November 2026, 28 February 2027, 30 May and 29 August 2027), so the Friday before is the safe day. An extension to file can be requested only through the ESTV portal, and interest still runs from the original date. Foreign businesses need a Swiss tax representative.
- Source
- ESTV — Jahresabstimmung / Finalisierung (rule: MWSTG Art. 71 Abs. 1, Art. 86 Abs. 1; period: Art. 35 Abs. 1) Eidgenössische Steuerverwaltung ESTV
See the source text
“Dieser berechnet sich nach dem Verfalldatum der betreffenden Steuerperiode (in der Regel 60 Tage nach Ablauf der Steuerperiode bzw. der 28. Februar des Folgejahres) bis zum Zeitpunkt der Zahlung nach der kaufmännischen Zinsmethode (30/360-Regel).”
 Open full size Captured from Eidgenössische Steuerverwaltung ESTV on 2026-10-14