Austria introduces a EUR 2 parcel delivery tax on large distance sellers
This page records one dated change. For the rules in Austria as they stand today, see the Austria guide →
- Jurisdiction
- Austria
- Tax
- Parcel Delivery Tax
- Change type
- Update
- Status
- In force
- Impact
- Action required
- Announced
- 29 July 2026
- Effective
- 1 October 2026
- Authority
- Bundesministerium für Finanzen (Austria)
- Systems
- E-commerce, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Distance sellers of goods whose Austrian distance-sales revenue exceeded EUR 100 million in the previous year, and online marketplaces liable under the deemed-supplier rule.
Large distance sellers and marketplaces: register for and account for the EUR 2 parcel tax on Austrian B2C deliveries from 1 October 2026.
E-commerceTax engineReporting
Austria's Paketsteuergesetz, enacted in BGBl. I Nr. 62/2026 (Budgetbegleitgesetz 2027–2028, published 29 July 2026), imposes a parcel delivery tax of EUR 2 per parcel on the domestic delivery of parcels in the course of distance sales of goods from 1 October 2026. It applies to distance sellers whose Austrian distance-sales revenue exceeded EUR 100 million in the previous year, with online marketplaces liable under a deemed-supplier rule.
What changed in detail
Austria’s Paketsteuergesetz, enacted as part of the Budgetbegleitgesetz 2027–2028 (BGBl. I Nr. 62/2026, published 29 July 2026), imposes a parcel delivery tax of EUR 2 per parcel on the domestic delivery of parcels in the course of distance sales of goods, effective 1 October 2026. It applies to distance sellers whose Austrian distance-sales revenue exceeded EUR 100 million in the previous year. Online marketplaces are liable under a deemed-supplier rule, mirroring the VAT deemed-supplier mechanism for e-commerce platforms.
What it means
The EUR 100 million threshold means this lands on large distance sellers and the marketplaces facilitating them, not the typical mid-size EU seller registered for Austrian VAT — but marketplace operators need to check the deemed-supplier trigger regardless of their own revenue, since it turns on the platform’s role rather than a per-seller threshold. Large sellers and marketplaces should have registration and per-parcel accounting in place before 1 October 2026; this is a new tax distinct from VAT, so it needs its own line in invoicing and reporting systems rather than a rate change to an existing one.
Proof
As from 1 October 2026, the domestic delivery of parcels in the course of distance sales of goods will be subject to a parcel delivery tax of EUR 2 per parcel.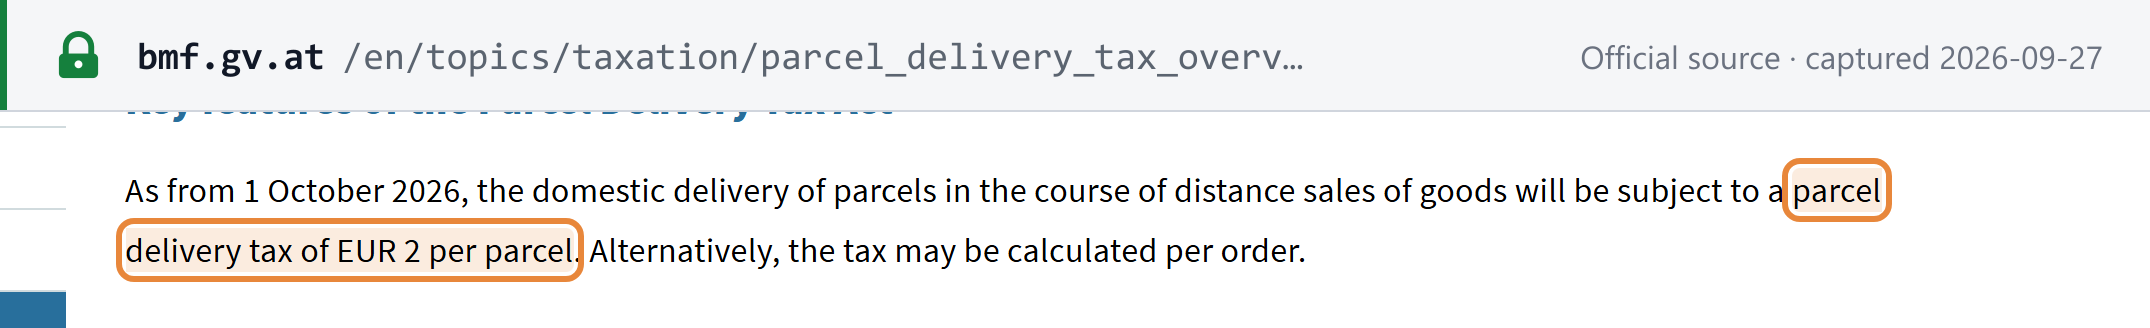 Source snapshot of the official page. Open full size ↗