Botswana replaces the remote-services VAT rules with the VAT Regulations, 2026 (S.I. 94 of 2026)
This page records one dated change. For the rules in Botswana as they stand today, see the Botswana guide →
- Jurisdiction
- Botswana
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- Plan ahead
- Announced
- 30 June 2026
- Effective
- 1 July 2026
- Authority
- Botswana Unified Revenue Service
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Non-resident suppliers of remote (digital) services to Botswana customers, whose obligations now rest on the VAT Act, 2026 and regulations 14-16 of S.I. 94 of 2026 (definition, registration and invoicing of remote services) rather than the revoked S.I. 74 of 2026.
Re-point non-resident digital-services VAT procedures and citations from S.I. 74 of 2026 to the VAT Act, 2026 and S.I. 94 of 2026.
Tax engine
Botswana's Value Added Tax Regulations, 2026 (Statutory Instrument No. 94 of 2026), made on 30 June 2026 under the Value Added Tax Act, 2026 (Act No. 15 of 2026), revoke at regulation 20(d) the Value Added Tax (Remote Services) Regulations (S.I. No. 74 of 2026), together with the Value Added Tax (Exemption), (Tax Period) and (Government Entities and Large Unregistered Persons) Regulations. The revocation came into operation on 1 July 2026 under the Value Added Tax Act (Part Commencement Date) Order, 2026 (S.I. No. 95 of 2026). This supersedes bw-remote-services-vat-si-74-2026 (2026-W30), which described S.I. 74 of 2026 as the operative instrument for non-resident remote-services VAT; those obligations now rest on the VAT Act, 2026 and its regulations.
What changed in detail
This corrects the record of S.I. 74 of 2026, which described those regulations as the rules in force for non-resident remote-services VAT. They no longer are.
The Value Added Tax Regulations, 2026 (Statutory Instrument No. 94 of 2026), made by the Minister of Finance on 30 June 2026 under the VAT Act, 2026 (Act No. 15 of 2026), revoke at regulation 20(d) the VAT (Remote Services) Regulations (S.I. No. 74 of 2026), together with the VAT (Exemption), (Tax Period) and (Government Entities and Large Unregistered Persons) Regulations. The revocation took effect 1 July 2026 under the VAT Act (Part Commencement Date) Order, 2026 (S.I. No. 95 of 2026).
Non-resident suppliers of remote services now register and account under S.I. No. 94’s own regulations 14 to 16 (the definition of remote services, registration of the remote service supplier, and its invoice or receipt), made under the VAT Act, 2026 — not the repealed Act that S.I. 74 was made under. The remote-services registration threshold is P500,000 in any 12 months (VAT Act, 2026, s.13(2) and Schedule 5, paragraph 3).
What it means
A revocation is not automatically a re-enactment on identical terms. Anything built against S.I. 74’s specific machinery — its 25th-of-the-month filing deadline, its four-month registration-to-charging runway, its penalty amounts — needs re-checking against S.I. 94’s own text rather than assumed to carry over unchanged. Re-point citations and internal documentation from S.I. 74 to S.I. 94 and the VAT Act, 2026.
Proof
(d) Value Added Tax (Remote Services) Regulations.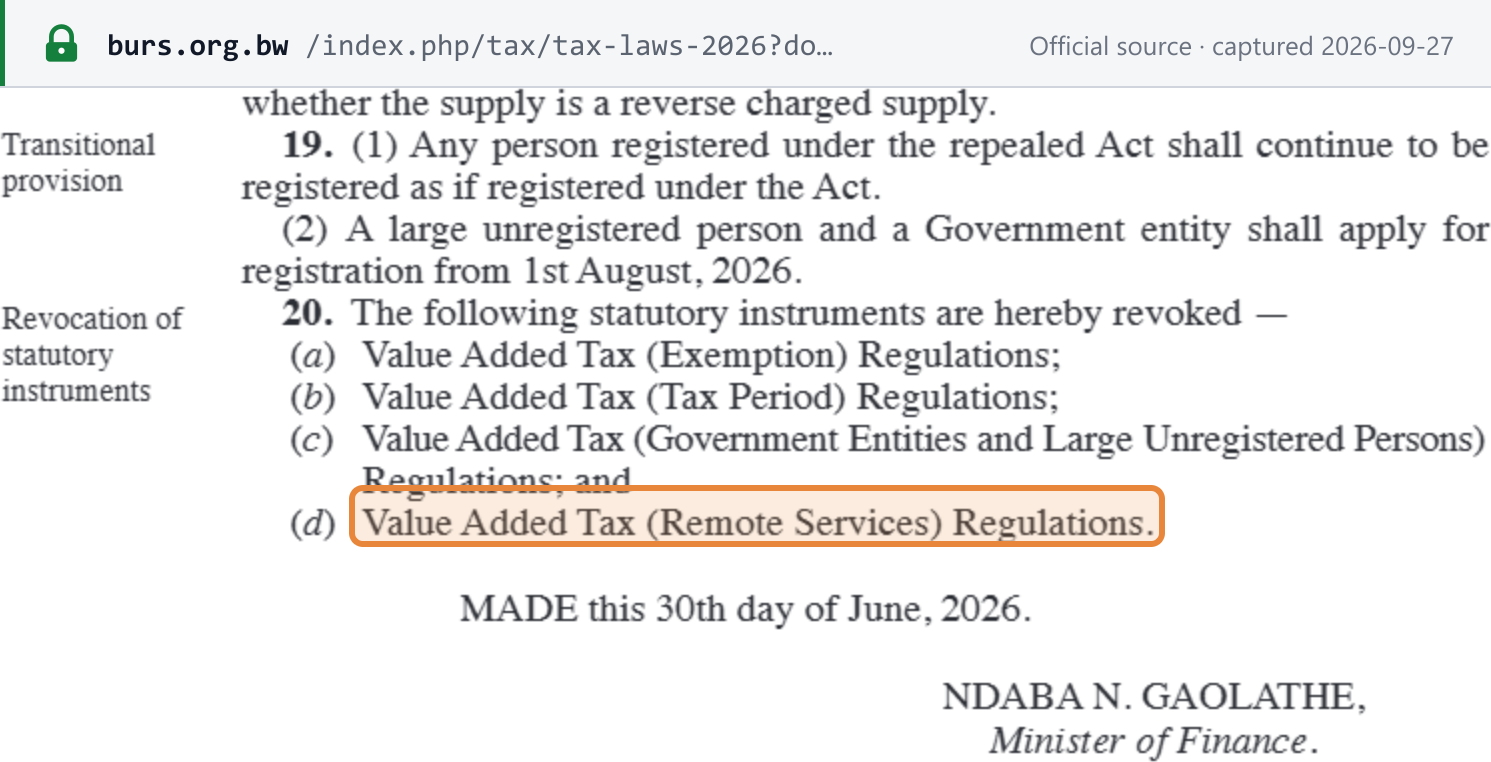 Source snapshot of the official page. Open full size ↗