Brazil's 1% CBS/IBS figure is a test rate, not a penalty for missing invoice fields
This page records one dated change. For the rules in Brazil as they stand today, see the Brazil guide →
- Jurisdiction
- Brazil
- Tax
- VAT (IBS/CBS)
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 15 June 2026
- Authority
- Comitê Gestor do IBS (CGIBS) and Receita Federal do Brasil
- Verified
- Fetched from official source · high confidence
Regular-regime Brazilian issuers of electronic fiscal documents (NF-e, NFC-e, CT-e and related documents) in the CBS/IBS transition.
Do not plan against a 1% penalty for omitting IBS/CBS fields. Establish the applicable limb of LC 214/2025 art. 341-G for the specific failure, and note that during the adaptive period neither fines nor document rejection apply.
CORRECTION to br-dual-vat-pilot-test-rate-2026 (issue 2026-W27), which recorded that penalties of up to 1% of transaction value per tax would apply from 1 August 2026 for omitting the IBS and CBS fields from electronic fiscal documents. The cited source does not support a penalty of that size or kind: the 1% it describes is the pilot TEST RATE (0.1% IBS plus 0.9% CBS) that documents must carry, and the same page states that during the adaptive period under Ato Conjunto RFB/CGIBS no 1/2025 the absence of IBS and CBS data causes neither fines nor document rejection. The statutory penalty framework for fiscal-document deficiencies is in LC 214/2025 art. 341-G, whose relevant limbs run from 66 to 100 percent of the reference tax value; a 1 percent ceiling exists there only for 'outras hipoteses de infracao', not for IBS/CBS field omission.
What changed in detail
Brazilian electronic fiscal documents in the 2026 CBS/IBS pilot carry a 1% test rate: 0.9% CBS plus 0.1% IBS. That 1% is the rate the documents must show. It is not a penalty.
The CGIBS notice on the 3 August 2026 milestone says that, under the flexibility granted by Ato Conjunto RFB/CGIBS nº 1/2025, the validation rules were not being applied. In practice, a missing IBS or CBS field caused neither fines nor document rejection. The same notice said documents without the fields would be rejected automatically once the obligation became operational. Brazil later deferred those validation rules without changing the duty to report the fields.
The statutory penalties for fiscal-document defects are in LC 214/2025, article 341-G. Its relevant limbs run from 66% to 100% of the reference tax value. A 1% ceiling there applies only to “outras hipóteses de infração”, not to omitting the CBS/IBS fields. An earlier event (the pilot test-rate record) had described the 1% as a penalty of up to 1% per tax from 1 August 2026.
What it means
Do not budget for a 1% penalty on missing CBS/IBS fields. The real exposure is operational: once validation applies, an incomplete document is refused, not fined at 1%. Issuers should still populate the fields now, because the reporting duty and the schedule were not deferred.
Proof
a alíquota teste de 1% (0,1% de IBS e 0,9% de CBS)the 1% test rate (0.1% IBS and 0.9% CBS)
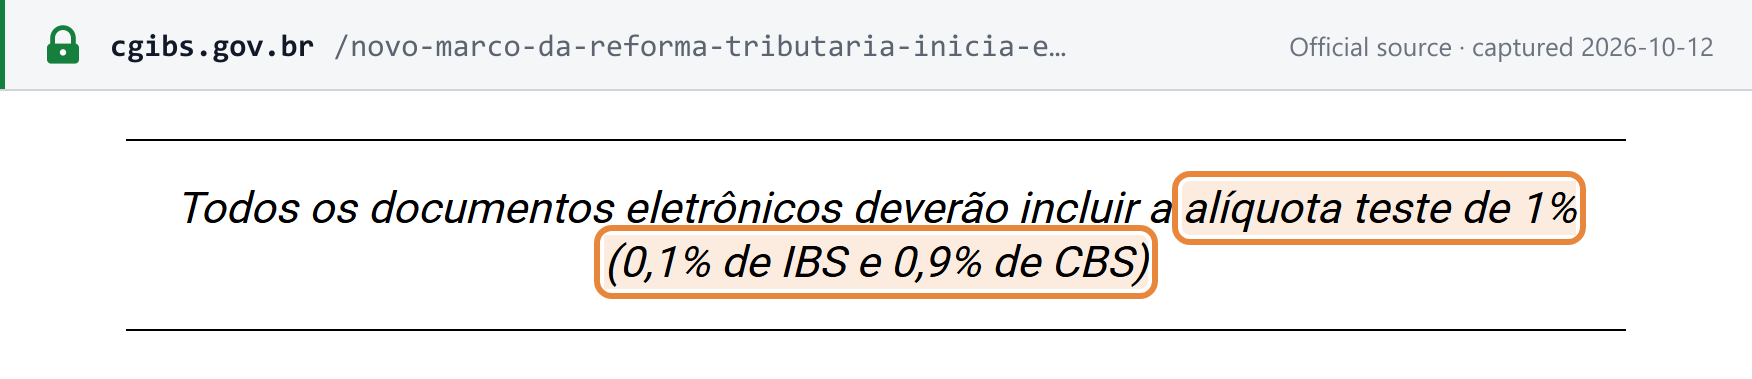 Source snapshot of the official page. Open full size ↗
Isso significa que, na prática, a ausência de preenchimento de IBS e CBS não causa multas nem rejeições de documentos.This means that, in practice, failing to fill in the IBS and CBS fields causes neither fines nor document rejections.
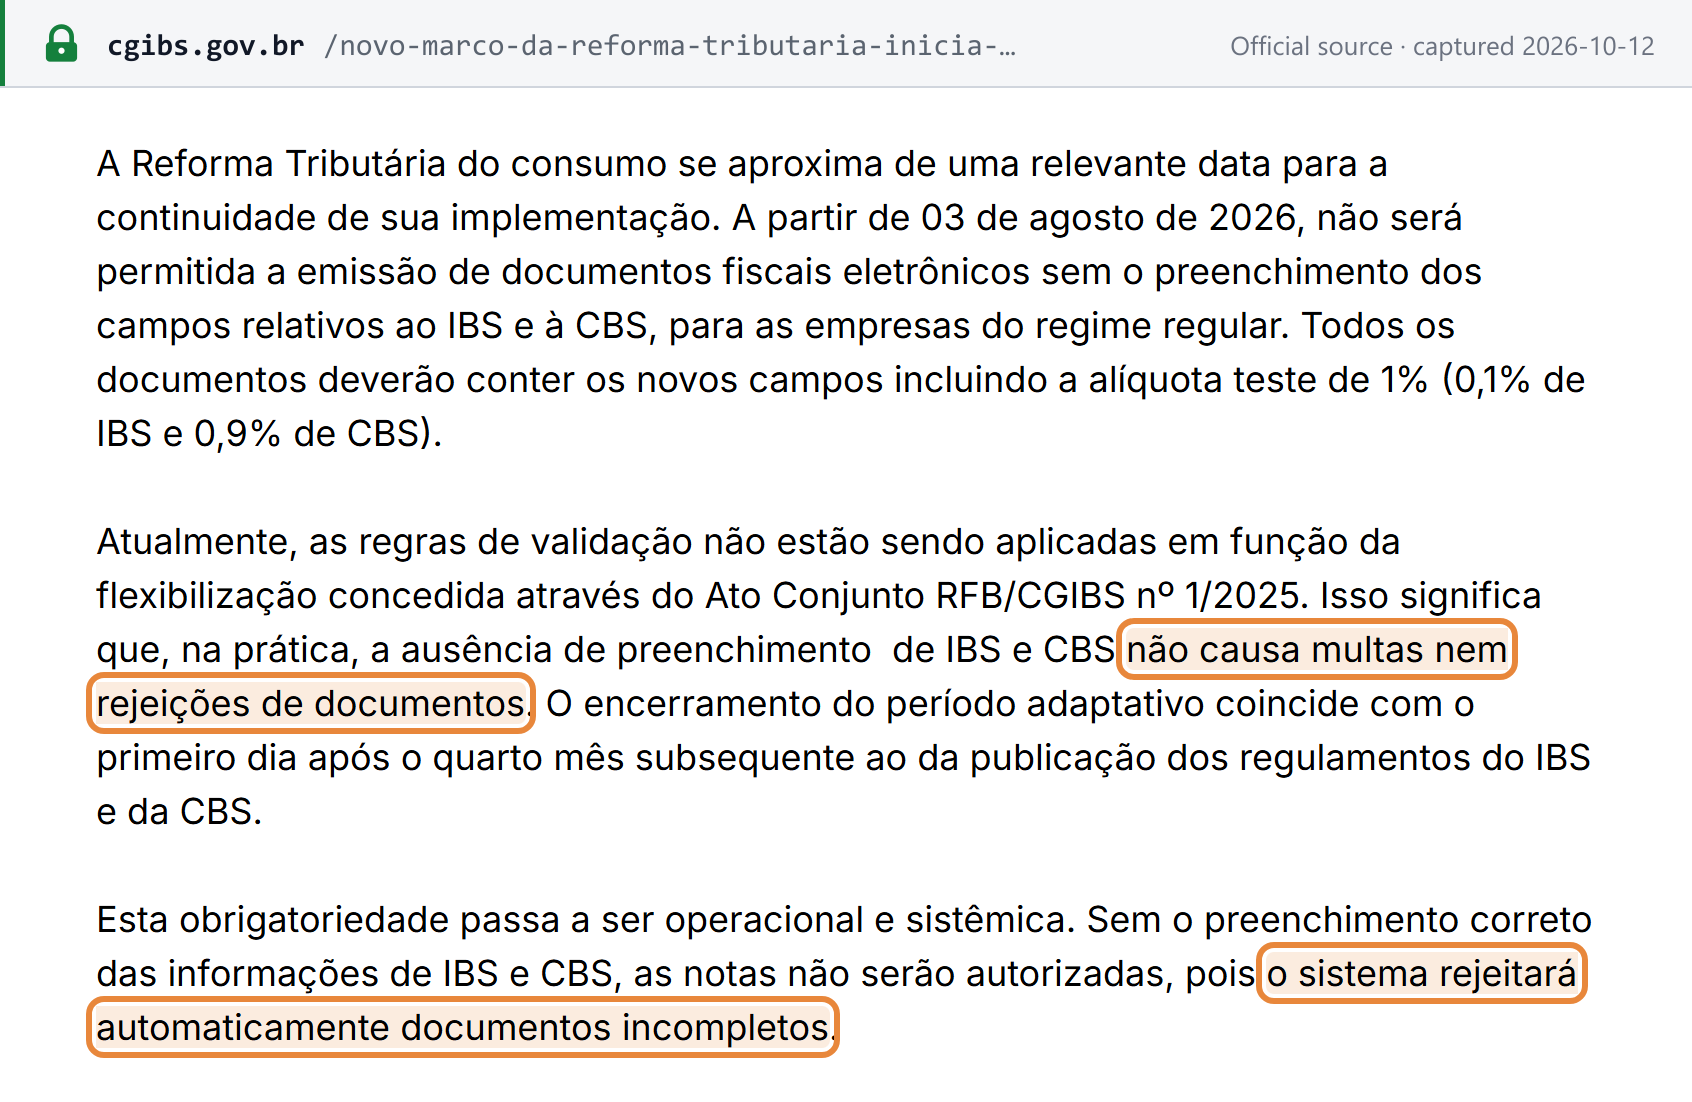 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Brazil's dual VAT pilot runs at a 1% test rate through 2026 effective 1 August 2026