Brazil's dual VAT pilot runs at a 1% test rate through 2026
This page records one dated change. For the rules in Brazil as they stand today, see the Brazil guide →
- Jurisdiction
- Brazil
- Tax
- CBS/IBS (VAT)
- Change type
- Compliance
- Status
- In force
- Effective
- 1 August 2026
- Authority
- Presidencia da Republica (Planalto)
- Verified
- Corroborated against official id · high confidence
Every issuer of Brazilian electronic fiscal documents. The 1% pilot rate (0.9% CBS + 0.1% IBS) must be carried on the document; it is a test rate, not a charge to collect.
Under Brazil's dual-VAT reform (Complementary Law 214/2025), the 2026 pilot runs at a combined 1% test rate (0.9% CBS + 0.1% IBS). Per Joint Act RFB/CGIBS No. 01/2025, penalties for omitting the new IBS and CBS fields from electronic fiscal documents (NF-e and others) begin on 1 August 2026 — up to 1% of the transaction value per tax.
What changed in detail
Under Brazil’s dual-VAT reform (Complementary Law 214/2025), the 2026 transition pilot runs at a combined 1% test rate — 0.9% CBS plus 0.1% IBS — which electronic fiscal documents must carry for informational purposes during the transition.
:::note Correction, 20 September 2026 This record previously stated that penalties of up to 1% of transaction value per tax applied from 1 August 2026 for omitting the IBS and CBS fields. That was wrong, and the figure was never a penalty. The 1% is the pilot test rate described above; the two were conflated.
The Comitê Gestor do IBS puts it in those words — “a alíquota teste de 1% (0,1% de IBS e 0,9% de CBS)” — and states on the same page that, during the adaptive period under Ato Conjunto RFB/CGIBS nº 1/2025, the absence of IBS and CBS data causes neither fines nor document rejection (“não causa multas nem rejeições de documentos”).
The statutory penalty framework for fiscal-document deficiencies is LC 214/2025 art. 341-G, whose relevant limbs run from 66% to 100% of the reference tax value. A 1% ceiling does appear there, but only for “outras hipóteses de infração” — other, unlisted infringements — not for IBS/CBS field omission.
Note also that the proof captured on this record quotes the Act’s rate-setting clause. It proves the 0.9% CBS rate and nothing about any penalty.
Source: CGIBS, Novo marco da Reforma Tributária inicia no dia 03/08 :::
What it means
Carrying the IBS and CBS fields is a real 2026 obligation and the schedule is unchanged — but plan against the actual consequences, not a 1% figure that does not exist. During the adaptive period the consequence of omission is validation behaviour rather than a fine; where a penalty does bite, it is art. 341-G that sets it, at a far higher severity than 1%.
Proof
Em relação aos fatos geradores ocorridos de 1º de janeiro a 31 de dezembro de 2026, a CBS será cobrada mediante aplicação da alíquota de 0,9% (nove décimos por cento).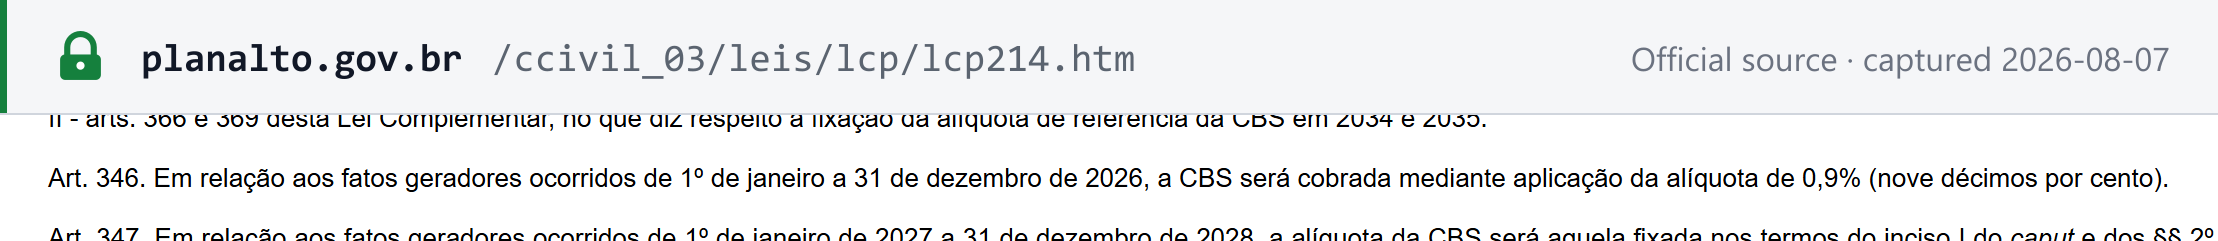 Source snapshot of the official page. Open full size ↗