EU: Commission guidance says the EUR 2 Union handling fee will form part of the VAT taxable amount, ahead of the delegated act appearing in the Official Journal
This change is proposed and is not law. The rules below describe what would change if it is adopted.
- Jurisdiction
- European Union
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- Watch
- Announced
- 21 September 2026
- Effective
- 1 November 2026
- Authority
- European Commission — Taxation and Customs Union
- Systems
- E-commerce, Tax engine, Customs, Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Sellers and platforms making distance sales of imported goods to EU consumers, including IOSS users, and the customs declarants and intermediaries who account for import VAT.
Update IOSS/import-VAT and checkout calculations so the EUR 2 per-item handling fee is inside the VAT base from the application date; confirm OJ publication date.
E-commerceTax engineCustomsInvoicingReporting
The Commission adopted (21 September 2026, C(2026) 6694 final) a delegated regulation setting the Union handling fee under Regulation (EU) 2026/2108 at EUR 2 per item for goods sold in distance sales, applying from the 10th day after the act's entry into force (Commission guidance expects 1 November 2026); the act is not yet seen in the Official Journal. The Commission's VAT e-Commerce addendum (revised 6 October 2026) states the fee is part of the VAT taxable amount as an incidental expense to the supply: included in the IOSS return where charged to the consumer at sale, and in the import VAT base under the special arrangements and the standard procedure (including supplies above EUR 150); under the special arrangements and the standard procedure, VAT on the fee is refunded when goods are returned.
What changed in detail
This is not yet in force. The European Commission adopted a delegated regulation on 21 September 2026 (C(2026) 6694 final) setting the Union handling fee under Regulation (EU) 2026/2108 at EUR 2 per item for goods sold in distance sales. It applies from the tenth day after its entry into force, which Commission guidance expects to be 1 November 2026. The act has not yet been seen in the Official Journal.
The Commission’s VAT e-Commerce addendum (revised 6 October 2026) states that the fee is part of the VAT taxable amount as an incidental expense to the supply. Where the fee is charged to the consumer at the time of sale it is included in the IOSS return. Under the special arrangements and the standard import procedure, including supplies above EUR 150, it forms part of the import VAT base. Under those two routes, VAT on the fee is refunded when the goods are returned.
What it means
The addendum is guidance, not the delegated act itself, so the dates depend on the act’s publication. Sellers pricing for 1 November 2026 should treat the fee as carrying VAT in their price and return-handling logic, and check the Official Journal for the actual entry-into-force date.
Proof
the handling fee should be part of the VAT taxable amount as it amounts to an incidental expense to the supply.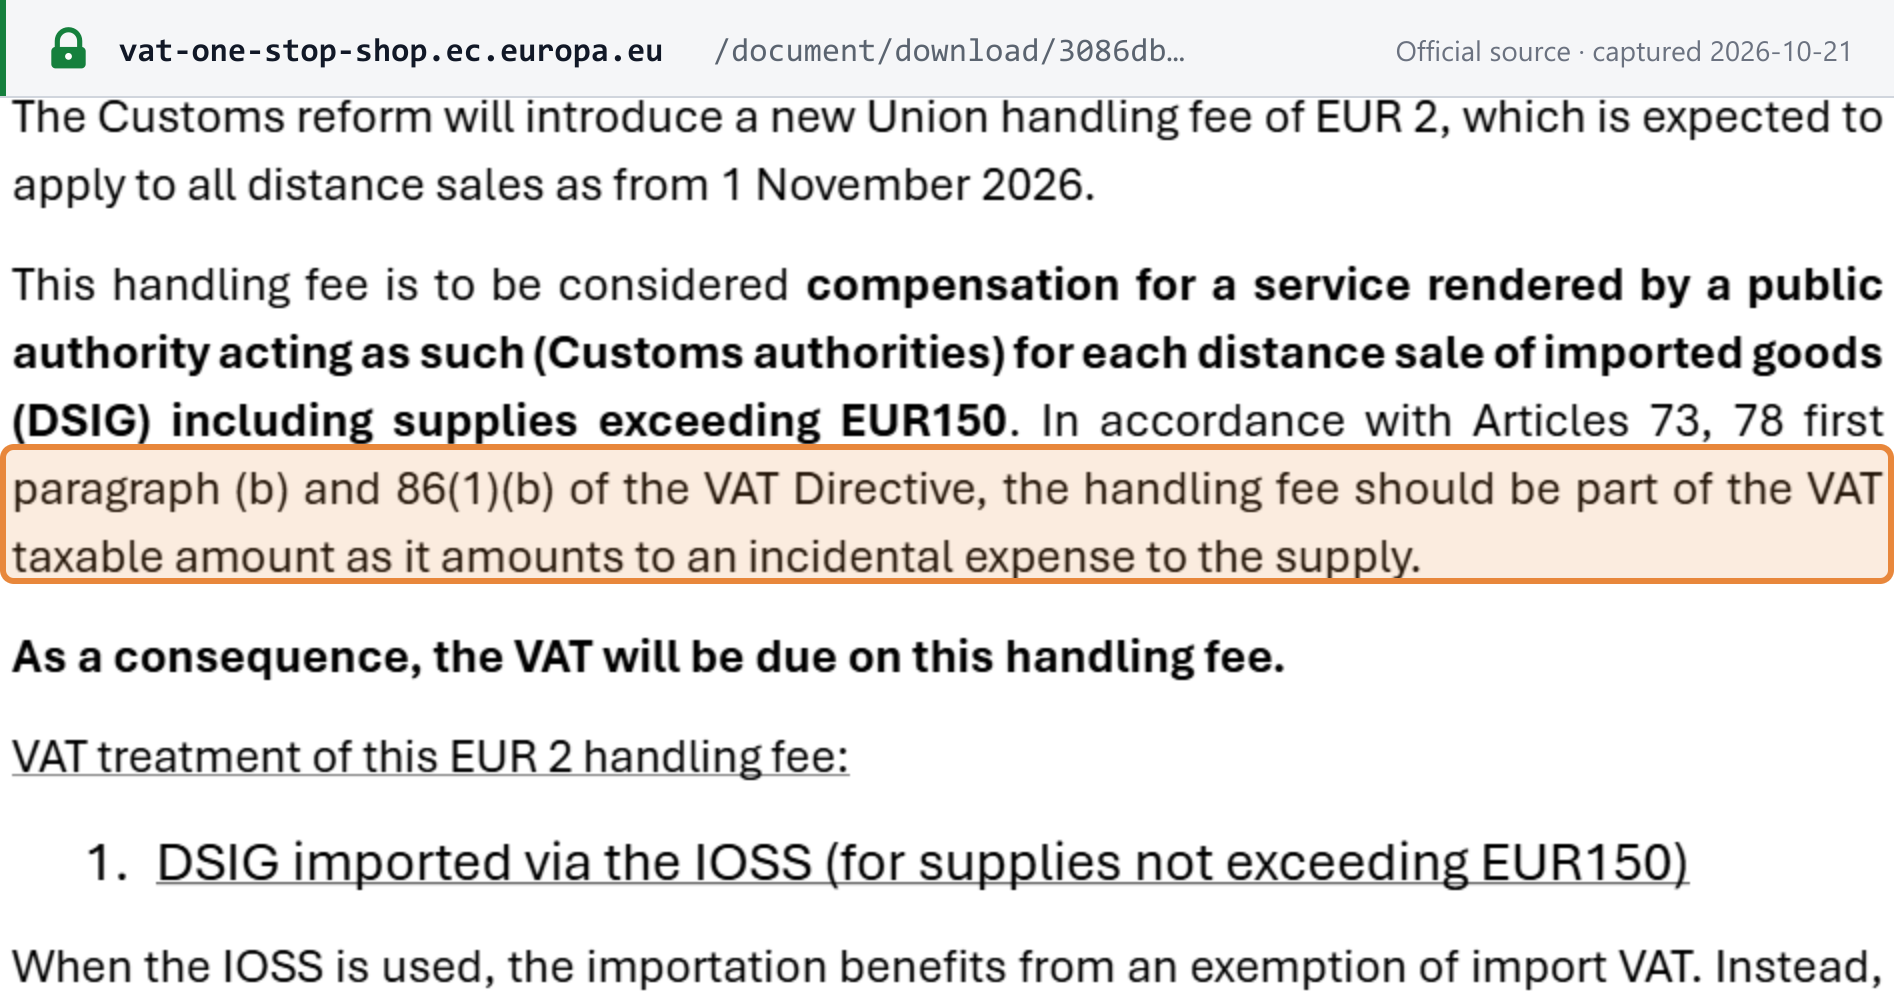 Source snapshot of the official page. Open full size ↗