Ireland's Finance (No. 2) Bill 2026 would exclude debt collection and factoring from the VAT financial-services exemption — a bill, not yet law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- Watch
- Announced
- 19 October 2026
- Authority
- Houses of the Oireachtas (Ireland)
- Systems
- ERP, Tax engine
- Verified
- Fetched from official source · high confidence
Providers of debt-collection and factoring services in Ireland, and their customers.
Review whether debt-collection and factoring services are currently treated as exempt; monitor Bill passage and commencement.
ERPTax engine
Section 54 of Ireland's Finance (No. 2) Bill 2026 would replace clause (c) of paragraph 6(1) of Part 2 of Schedule 1 to the VAT Consolidation Act 2010 (exempt financial services) so that the exemption for transactions concerning accounts, payments, transfers, debts, cheques and other negotiable instruments excludes debt collection and factoring. No commencement date is stated in the section. Bill as initiated.
What changed in detail
This is not law. Section 54 of the Finance (No. 2) Bill 2026 (Bill 98 of 2026), as initiated, has not been passed by the Oireachtas.
As initiated, section 54 amends Schedule 1 to the VAT Consolidation Act 2010, Part 2, paragraph 6(1), by substituting a new clause (c). The new clause exempts transactions concerning current, deposit or savings accounts, payments, transfers, debts, cheques and other negotiable instruments, but excluding debt collection and factoring. The section states no commencement date.
What it means
The new wording expressly carves debt collection and factoring out of the exemption, which suggests those services would no longer be exempt financial services. Businesses supplying or buying them should review how they are treated today and the VAT recovery position that would follow, and watch the Bill for a commencement provision.
Proof
transactions concerning current, deposit or savings accounts, payments, transfers, debts, cheques and other negotiable instruments, but excluding debt collection and factoring;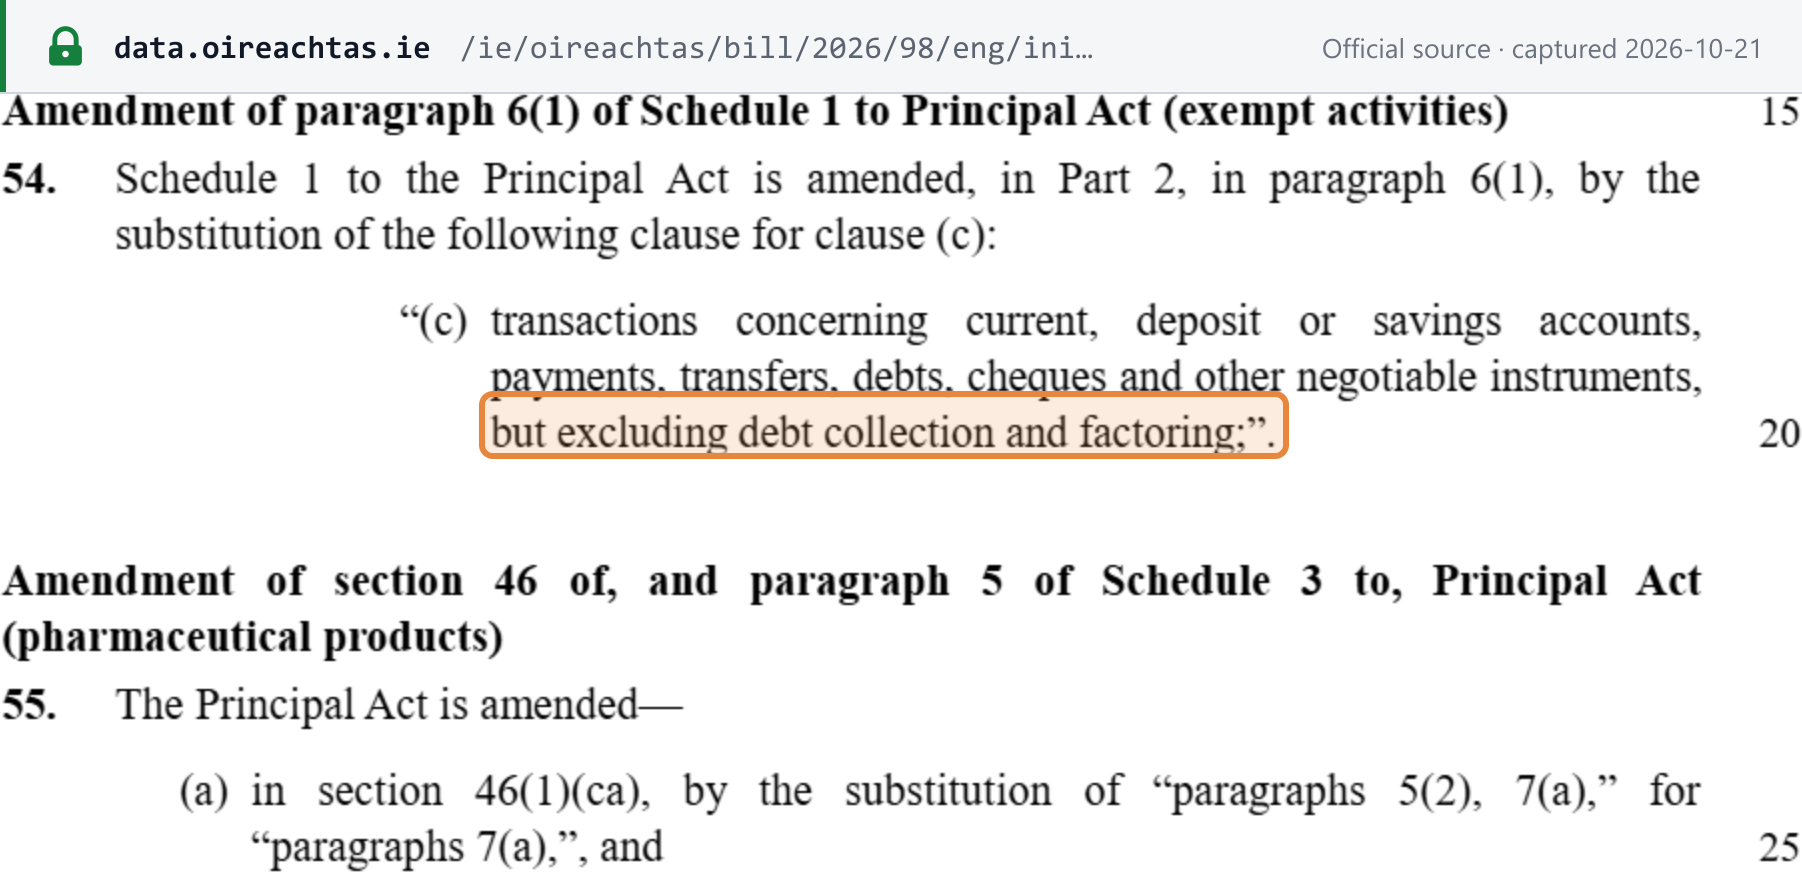 Source snapshot of the official page. Open full size ↗