Ireland's Finance (No. 2) Bill 2026 would raise the flat-rate farmer addition from 4.5% to 4.8% — a bill, not yet law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 19 October 2026
- Effective
- 1 January 2027
- Authority
- Houses of the Oireachtas (Ireland)
- Systems
- Invoicing, Tax engine
- Verified
- Fetched from official source · high confidence
Flat-rate farmers and the VAT-registered businesses that buy agricultural goods and services from them.
No action - monitoring only (flat-rate farmer invoicing: update the addition percentage if enacted).
InvoicingTax engine
Section 52 of Ireland's Finance (No. 2) Bill 2026 would amend section 86(1) of the VAT Consolidation Act 2010, with effect from 1 January 2027, to raise the flat-rate addition for flat-rate farmers from 4.5 per cent to 4.8 per cent. Bill as initiated.
What changed in detail
This is not law. Section 52 of the Finance (No. 2) Bill 2026 (Bill 98 of 2026), as initiated, has not been passed by the Oireachtas.
As initiated, section 52 amends section 86(1) of the VAT Consolidation Act 2010, with effect from 1 January 2027, by substituting ‘4.8 per cent’ for ‘4.5 per cent’. Section 86(1) governs the flat-rate addition that flat-rate farmers charge on supplies to VAT-registered customers. The earlier record on the 4.5 per cent addition covers the current figure.
What it means
If enacted unchanged, the addition rises by 0.3 percentage points. Flat-rate farmer invoicing and the self-billing templates of buyers would need the new percentage from 1 January 2027. Until the bill passes, keep using 4.5 per cent.
Proof
substitution of “4.8 per cent” for “4.5 per cent”.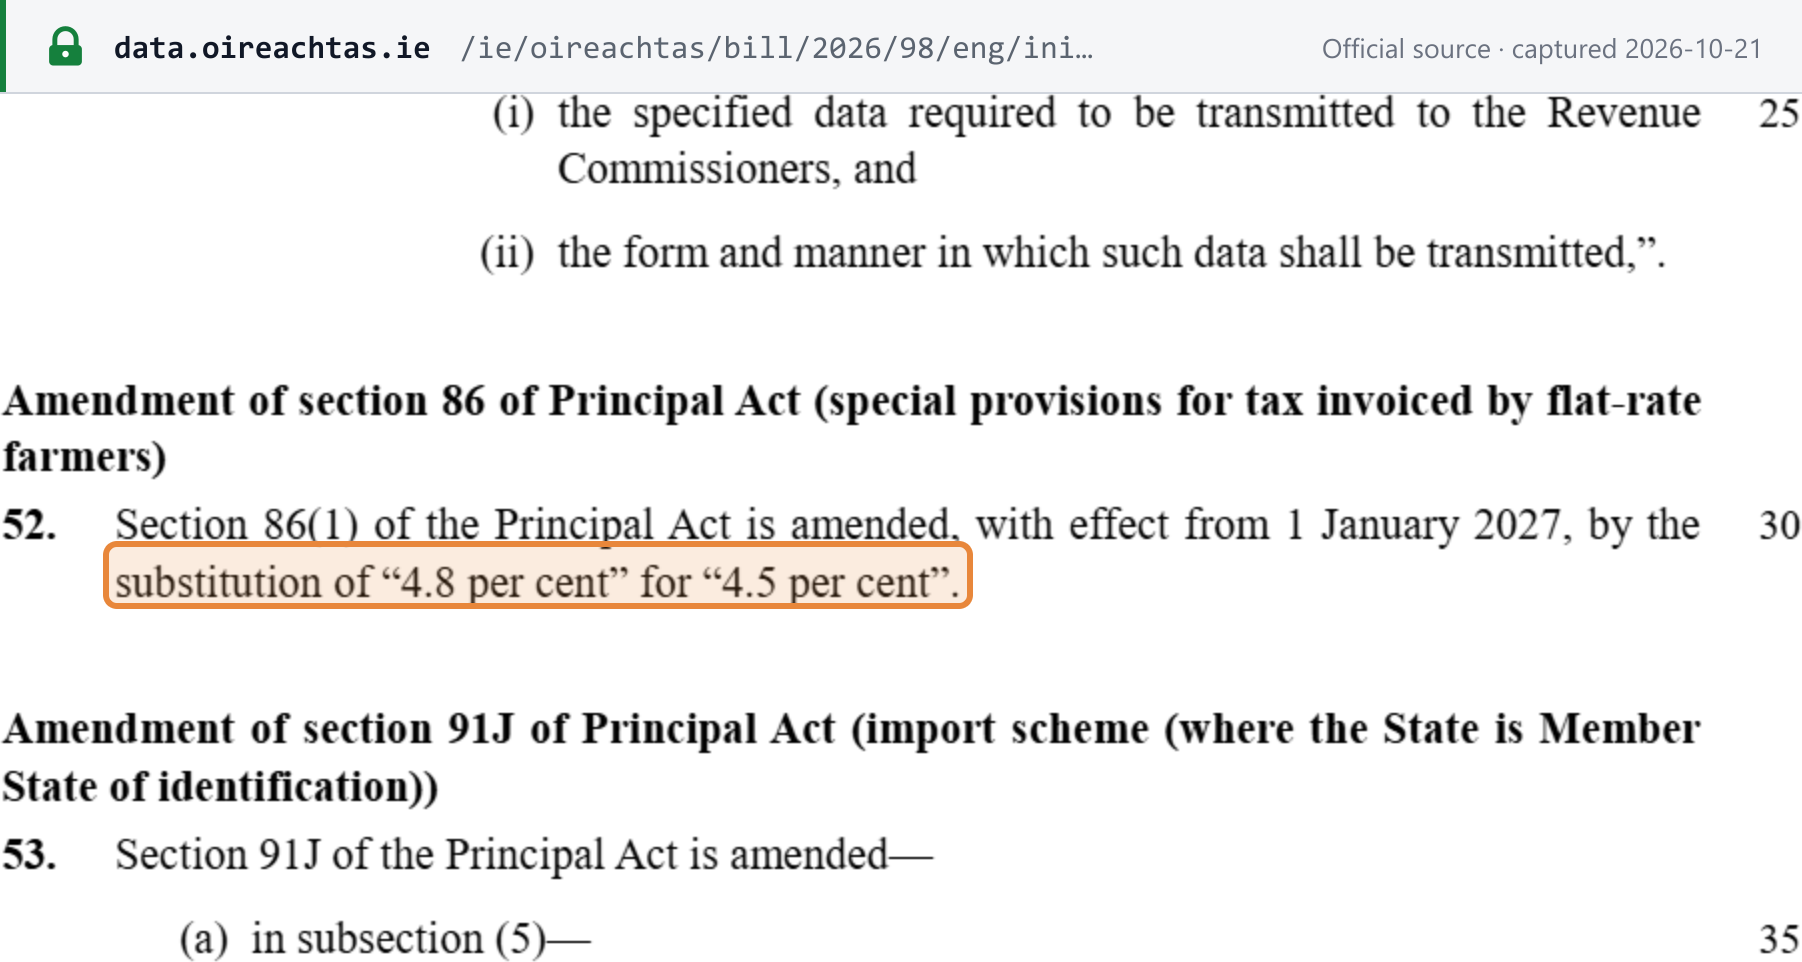 Source snapshot of the official page. Open full size ↗