Ireland's Finance (No. 2) Bill 2026 would require import-scheme intermediaries to hold tax clearance — a bill, not yet law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Compliance
- Status
- Proposed
- Impact
- Watch
- Announced
- 19 October 2026
- Authority
- Houses of the Oireachtas (Ireland)
- Systems
- Customs, E-commerce
- Verified
- Fetched from official source · high confidence
Intermediaries registered in Ireland for the VAT import scheme, and importers who appoint them.
No action - monitoring only (import-scheme intermediaries registered in Ireland should check tax clearance status if enacted).
CustomsE-commerce
Section 53 of Ireland's Finance (No. 2) Bill 2026 would amend section 91J of the VAT Consolidation Act 2010 (import scheme where the State is Member State of identification) so that an intermediary registered for the import scheme must hold a tax clearance certificate (section 1095 TCA 1997) for the duration of registration and must notify Revenue if it ceases to hold one. No commencement date is stated in the section. Bill as initiated.
What changed in detail
This is not law. Section 53 of the Finance (No. 2) Bill 2026 (Bill 98 of 2026), as initiated, has not been passed by the Oireachtas.
As initiated, section 53 amends section 91J of the VAT Consolidation Act 2010 (the import scheme where the State is the Member State of identification). An intermediary registered for the import scheme in the State would be required to hold a tax clearance certificate within the meaning of section 1095 of the Taxes Consolidation Act 1997 for the duration of its registration, and would have to notify Revenue if it ceases to hold one. The section states no separate commencement date.
What it means
The change turns tax clearance from a registration-time condition into a continuing one. Intermediaries should check how their clearance status is monitored internally, because losing it would need to be notified to Revenue. Commencement is not stated, so watch the Bill’s passage for any commencement provision.
Proof
an intermediary who is registered for use of the import scheme in the State shall be required to hold a tax clearance certificate within the meaning of section 1095 of the Taxes Consolidation Act 1997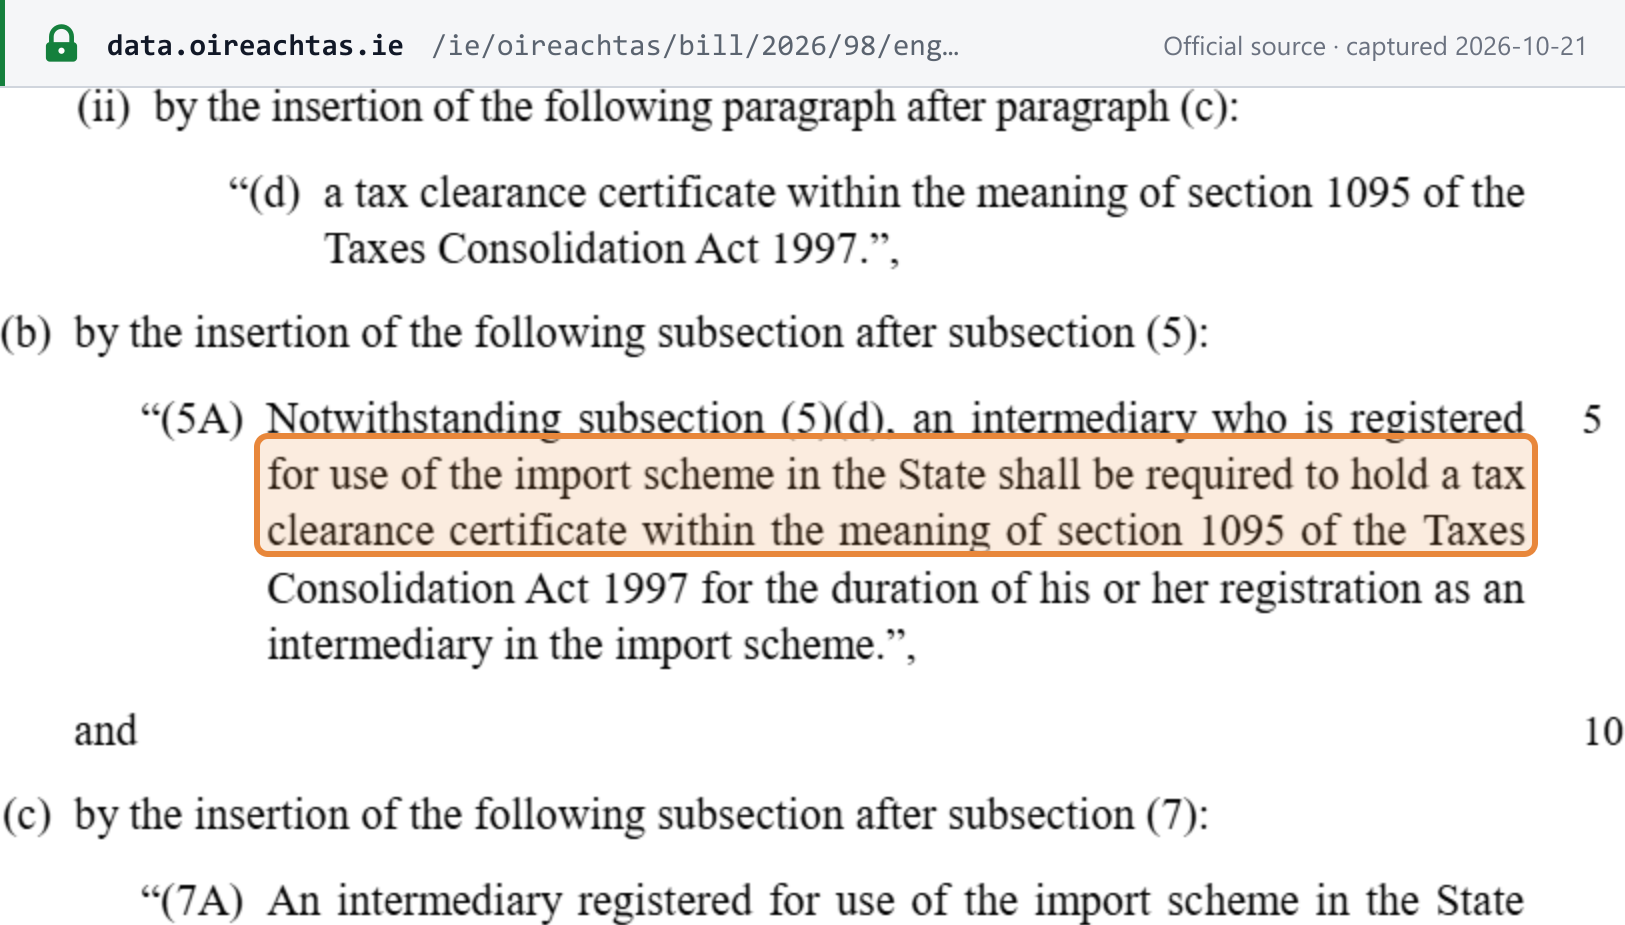 Source snapshot of the official page. Open full size ↗