Ireland's Finance (No. 2) Bill 2026 would put livestock respiratory vaccines at the reduced VAT rate — a bill, not yet law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 19 October 2026
- Authority
- Houses of the Oireachtas (Ireland)
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Suppliers of veterinary medicines and livestock farmers buying non-oral respiratory vaccines.
No action — monitoring only.
Tax engine
Section 55 of Ireland's Finance (No. 2) Bill 2026 (Bill 98 of 2026), initiated in the Dáil on 19 October 2026, would insert 'the supply of non-oral respiratory vaccines of a kind used for livestock' into paragraph 5(2) of Part 2 of Schedule 3 to the VAT Consolidation Act 2010, the reduced-rate schedule. As initiated, the bill gives section 55 no separate commencement date. The bill is subject to amendment during its passage through the Oireachtas.
What changed in detail
This is not law. Section 55 of the Finance (No. 2) Bill 2026 (Bill 98 of 2026), initiated in the Dáil on 19 October 2026, has not been passed by the Oireachtas and is subject to amendment.
As initiated, section 55 inserts ‘the supply of non-oral respiratory vaccines of a kind used for livestock’ into paragraph 5(2) of Part 2 of Schedule 3 to the VAT Consolidation Act 2010, the reduced-rate schedule. The bill gives section 55 no separate commencement date.
What it means
Moving these vaccines to the reduced-rate schedule would lower the VAT charged on the supply. Until the bill passes and commences, suppliers should keep charging the rate that applies today.
Proof
(2) The supply of non-oral respiratory vaccines of a kind used for livestock.”.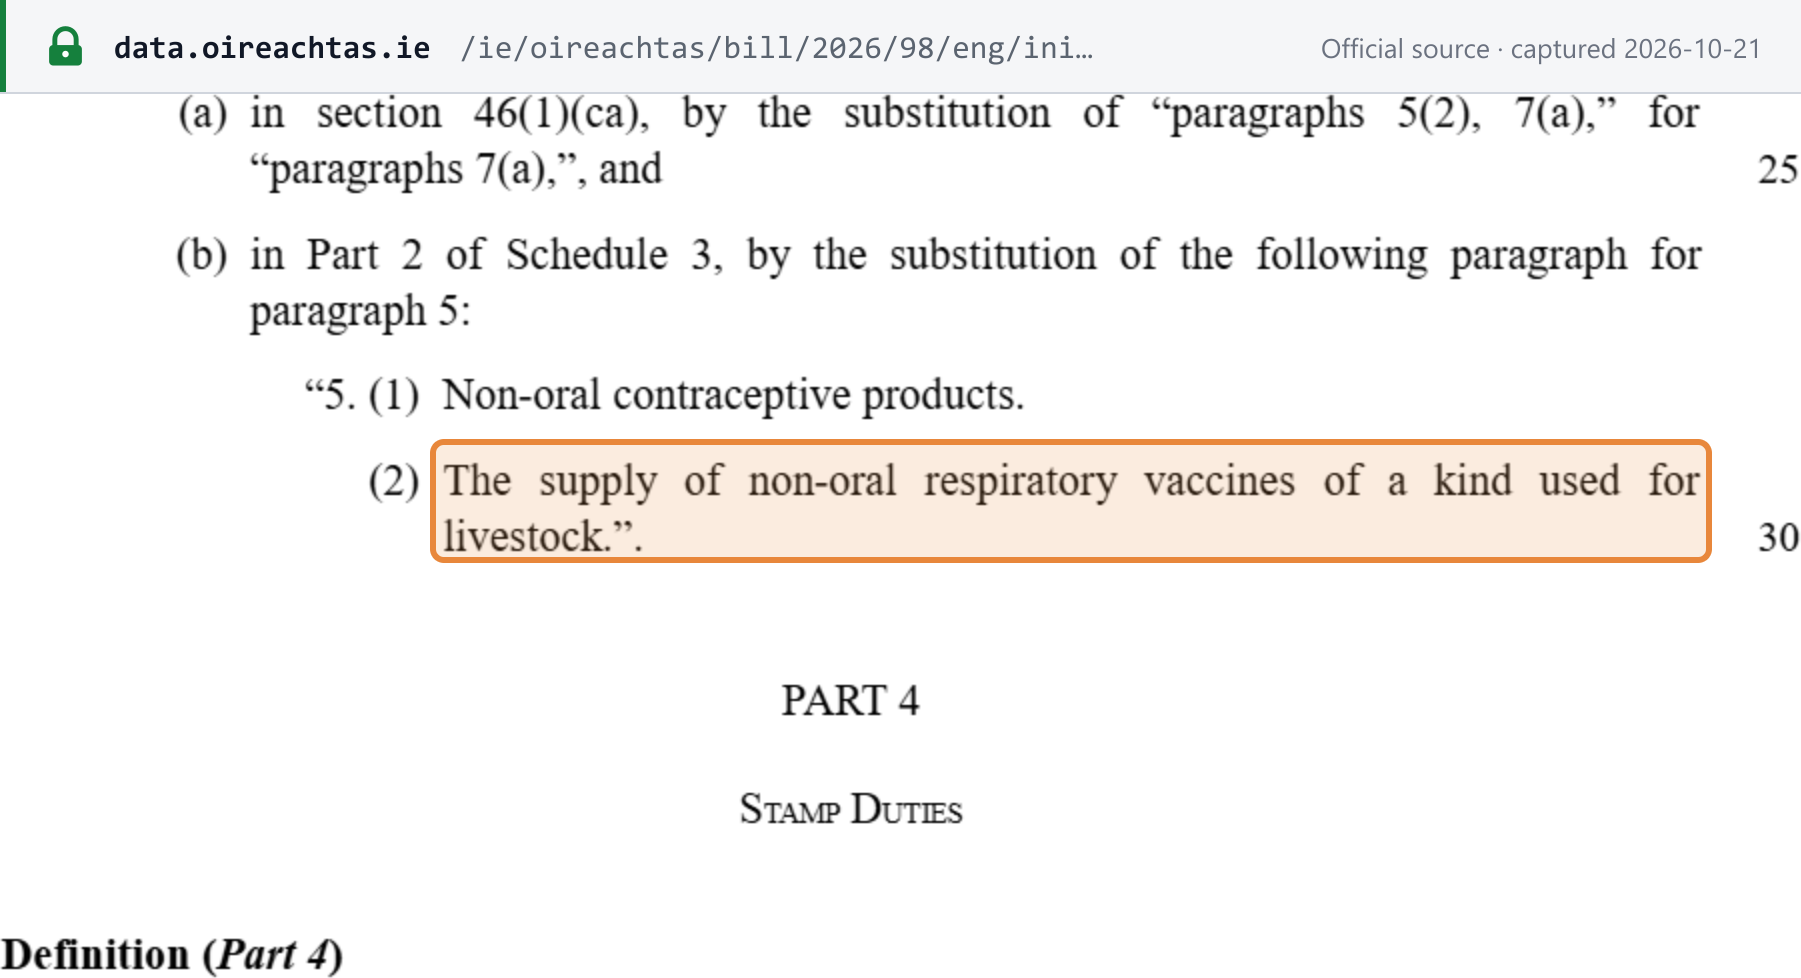 Source snapshot of the official page. Open full size ↗