Ireland's Budget 2027 proposes 9% VAT on non-oral livestock respiratory vaccines, a 4.8% farmer flat-rate addition and a EUR 15 million charities fund
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Plan ahead
- Announced
- 7 October 2026
- Authority
- Department of Finance (Ireland)
- Systems
- Tax engine, Invoicing
- Verified
- Fetched from official source · high confidence
Suppliers of non-oral respiratory vaccines for livestock, flat-rate farmers, and charities claiming under the VAT Compensation Scheme.
Prepare to apply 9% VAT to non-oral respiratory livestock vaccines once the Finance Act 2026 commences the measure, and update the farmer flat-rate addition to 4.8% from 1 January 2027.
Tax engineInvoicing
Ireland's Budget 2027 tax policy changes (Department of Finance, 7 October 2026) state that the VAT rate on non-oral respiratory vaccines for livestock will be reduced from the 23% standard rate to 9%, that the farmer's flat-rate addition will be 4.8% for 2027 (4.5% in 2025), and that the annual capped fund of the VAT Compensation Scheme for Charities will rise from EUR 10 million to EUR 15 million for 2027. The measures are announced budget measures to be legislated in the Finance Bill 2026.
What changed in detail
These are announced budget measures to be legislated in the Finance Bill 2026; they are not yet law. Ireland’s Budget 2027 tax policy changes (Department of Finance, 7 October 2026) state that:
- the VAT rate on non-oral respiratory vaccines for livestock will be reduced from the 23% standard rate to 9%;
- the farmer’s flat-rate addition will be 4.8% for 2027 (4.5% in 2025);
- the annual capped fund of the VAT Compensation Scheme for Charities will rise from EUR 10 million to EUR 15 million for 2027.
The document does not state a commencement date for the vaccine rate.
What it means
The vaccine rate change removes a gap in which oral medicines for livestock, including vaccines, are zero-rated while non-oral ones are charged at 23%. Suppliers should prepare to apply 9% once the Finance Act 2026 commences the measure, and should not apply it before then.
The flat-rate addition of 4.8% is the figure to build into farmer invoicing and accounting for 2027. It continues the annual revision of the rate; compare it with the 4.5% rate recorded earlier.
Proof
The intention is that the new VAT rate for non-oral respiratory vaccines for livestock will be 9%.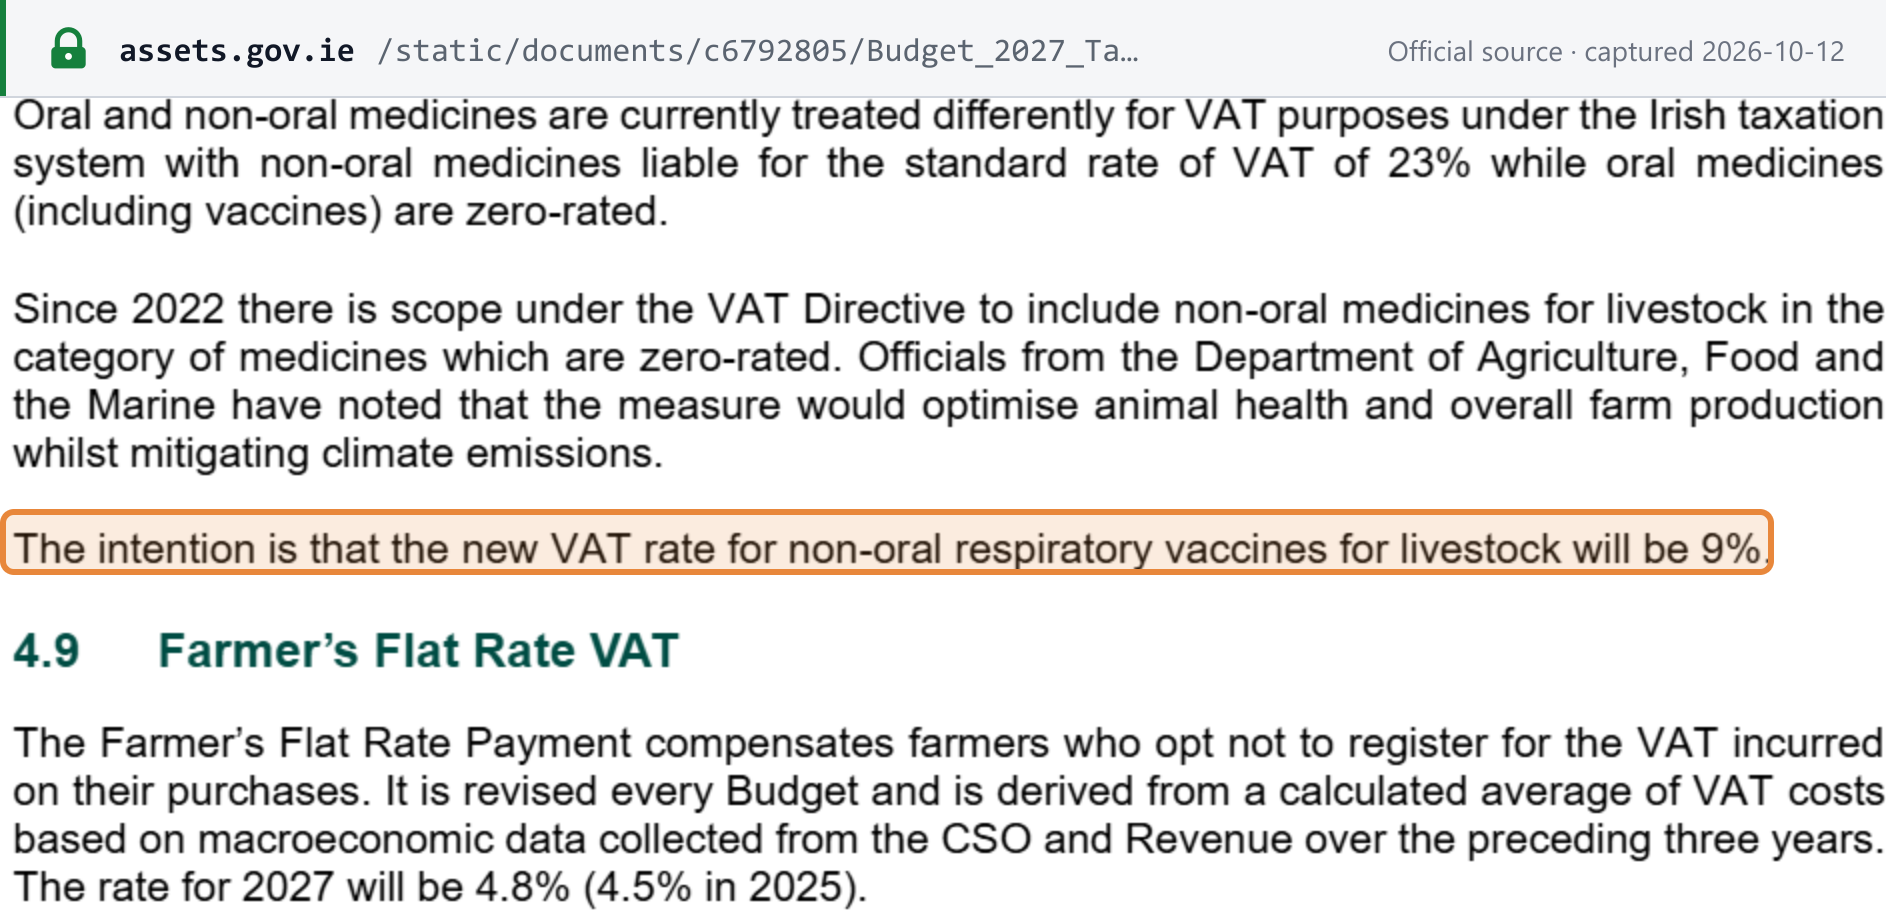 Source snapshot of the official page. Open full size ↗