Japan requires an import-permit equivalent for cash export sales and ends export exemption for Japanese real estate brokerage to non-residents from 1 October 2026
This page records one dated change. For the rules in Japan as they stand today, see the Japan guide →
- Jurisdiction
- Japan
- Tax
- Consumption tax
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Effective
- 1 October 2026
- Authority
- National Tax Agency of Japan (NTA)
- Systems
- ERP, Customs, Reporting
- Verified
- Fetched from official source · high confidence
Japanese exporters paid in cash or by methods where the payer is unclear, and agents or brokers of Japanese real estate supplying services to non-residents.
For cash or unclear-payer export sales from 1 October 2026, retain the destination-country import permit equivalent alongside the export permit.
ERPCustomsReporting
Two FY2026 consumption tax amendments in Japan apply to supplies made on or after 1 October 2026. For exports of goods paid for in cash or by a method in which it is not clear that payment came from the counterparty, the export exemption now also requires the exporter to keep a document equivalent to an import permit in the destination country (bank transfers and documentary-bill settlements are not treated as such payment methods). Agency, intermediary or brokerage services for the sale, exchange or lease of real property in Japan supplied to non-residents are no longer export-exempt; supplies under contracts concluded on or before 31 March 2026 remain export-exempt.
What changed in detail
Two FY2026 consumption tax amendments in Japan apply to supplies made on or after 1 October 2026.
Export proof for cash sales. For exports of goods paid for in cash, or by a method in which it is not clear that payment came from the counterparty, the export exemption now also requires the exporter to keep a document equivalent to an import permit in the destination country. Bank transfers and documentary-bill settlements are not treated as such payment methods.
Real estate brokerage. Agency, intermediary or brokerage services for the sale, exchange or lease of real property in Japan supplied to non-residents are no longer export-exempt. Supplies under contracts concluded on or before 31 March 2026 remain export-exempt.
What it means
The export change adds a document to retain, alongside the export permit, for cash or unclear-payer sales only. Exporters settled by bank transfer or documentary bill are outside it.
The brokerage change turns a previously exempt service into a taxable one for non-resident clients. Brokers should check the conclusion date of each contract: pre-April 2026 contracts keep the exemption, later ones do not.
Proof
【適用開始時期】令和8年10月1日以後に行われる資産の譲渡又は貸付けについて適用されます。[Start of application] Applies to transfers or leases of assets made on or after 1 October 2026 (Reiwa 8).
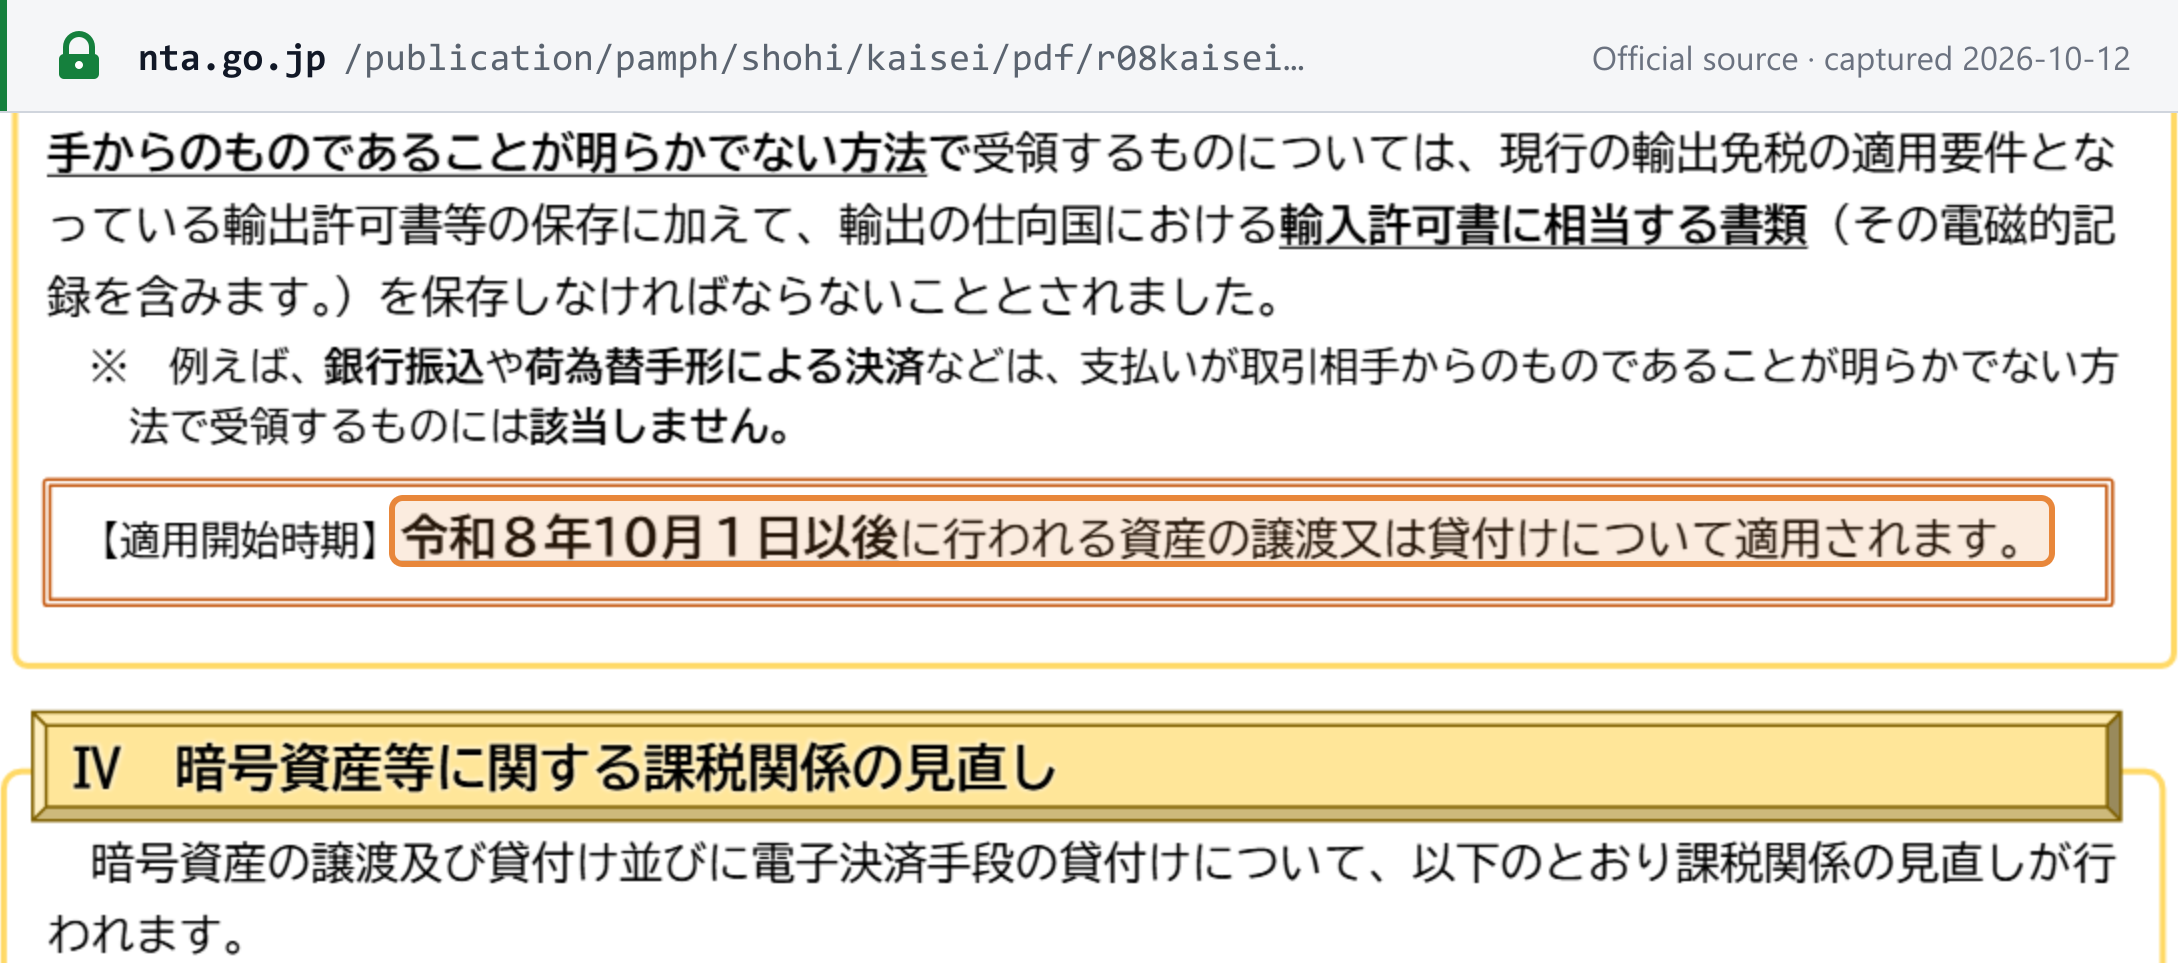 Source snapshot of the official page. Open full size ↗