Malaysia corrects P.U.(A) 303/2026: the Director General approves the manufacturer, not the goods
This page records one dated change. For the rules in Malaysia as they stand today, see the Malaysia guide →
- Jurisdiction
- Malaysia
- Tax
- Sales Tax
- Change type
- Update
- Status
- In force
- Impact
- Action required
- Announced
- 28 August 2026
- Effective
- 1 September 2026
- Authority
- Attorney General's Chambers, Malaysia (Warta Kerajaan Persekutuan / Federal Gazette)
- Systems
- ERP, Tax engine
- Verified
- Fetched from official source · high confidence
Manufacturers of animal feed, fertilizer or pesticide products seeking the Schedule B sales tax exemption on production inputs under P.U.(A) 303/2026.
Obtain Director General approval as the manufacturer and Minister of Finance approval for the goods before claiming the P.U.(A) 303/2026 exemption; the manufacturer signs the exemption certificate.
ERPTax engine
P.U.(A) 303/2026, the Sales Tax (Persons Exempted From Payment Of Tax) (Amendment) (No. 2) Order 2026 (gazetted 28 August 2026, in operation 1 September 2026), inserts items 5, 6 and 7 into Schedule B of P.U.(A) 210/2018 for the manufacture of animal feed, fertilizer and pesticide respectively. In each item the exempt person is 'Any manufacturer approved by the Director General', the exempted goods are 'The goods approved by the Minister of Finance' used solely in that manufacture, and the exemption certificate is signed by the manufacturer itself. This corrects my-sales-tax-exemption-pua-303-2026 (2026-W39), which described the manufacturers as Minister-approved and the certificate as signed by the Director General.
What changed in detail
This corrects an earlier record of P.U.(A) 303/2026, the Sales Tax (Persons Exempted From Payment Of Tax) (Amendment) (No. 2) Order 2026, which said the manufacturer was approved by the Minister of Finance and that the exemption certificate was signed by the Director General. Neither is right — the roles are reversed.
Schedule B items 5, 6 and 7 — inserted by this Order for animal feed, fertilizer and pesticide manufacture respectively — name the exempt person as “any manufacturer approved by the Director General” and the exempted goods as “the goods approved by the Minister of Finance” used solely in that manufacture. Column (5) of each item puts the exemption certificate signature with the manufacturer itself, not the Director General. The Order was gazetted 28 August 2026 and took effect 1 September 2026.
What it means
Two different officials approve two different things, and a manufacturer relying on the earlier record’s reversed roles would apply to the wrong office for the wrong approval. Confirm Director General approval as the manufacturer before claiming the exemption, and separately check that the specific input goods are on the Minister of Finance’s approved list — approval of one does not imply approval of the other, and the manufacturer, not an official, signs its own certificate.
Proof
Any manufacturer approved by the Director General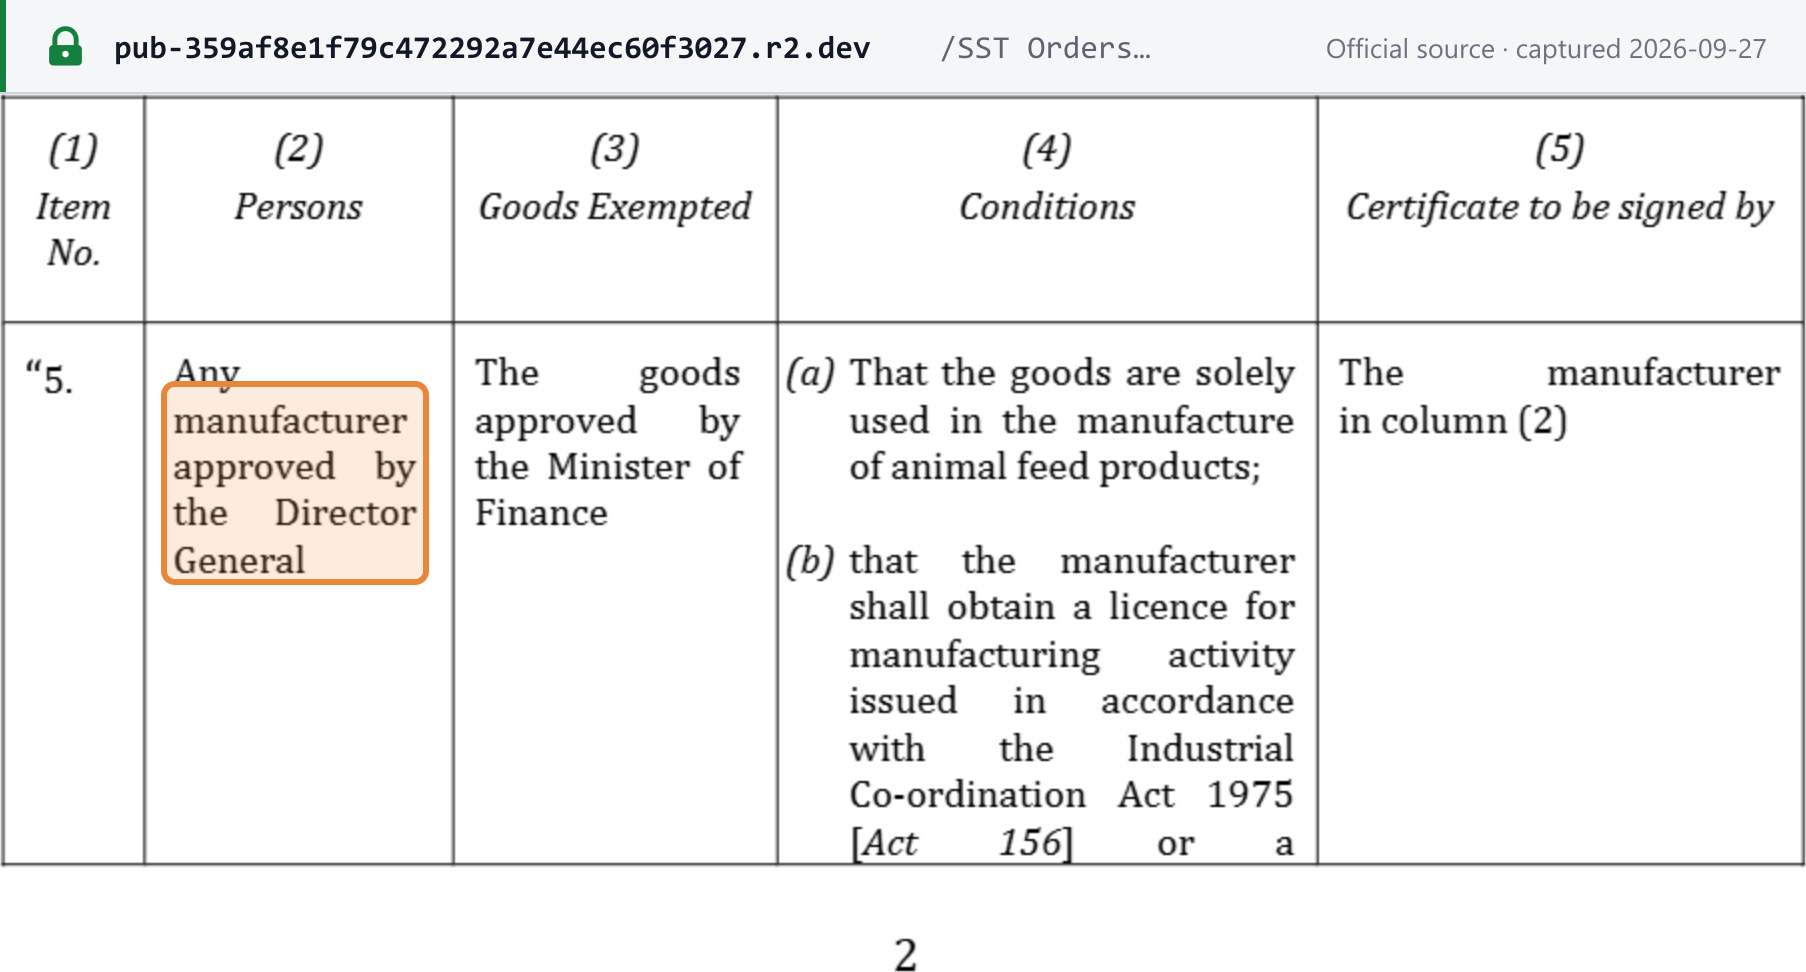 Source snapshot of the official page. Open full size ↗