Malaysia exempts approved animal feed, fertilizer and pesticide manufacturers from sales tax on production inputs
This page records one dated change. For the rules in Malaysia as they stand today, see the Malaysia guide →
- Jurisdiction
- Malaysia
- Tax
- SST
- Change type
- Rate change
- Status
- In force
- Impact
- Watch
- Effective
- 1 September 2026
- Authority
- Attorney General's Chambers, Malaysia (Warta Kerajaan Persekutuan / Federal Gazette)
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Manufacturers of animal feed, fertilizer or pesticide products approved by the Director General of Customs, for sales tax on goods approved by the Minister of Finance and used solely in that manufacture.
Manufacturers approved by the Minister of Finance for animal feed, fertilizer or pesticide production should confirm eligibility for the new Schedule B sales tax exemptions from 1 September 2026.
Tax engine
The Sales Tax (Persons Exempted From Payment Of Tax) (Amendment) (No. 2) Order 2026, P.U.(A) 303/2026, gazetted 28 August 2026, inserts three new items after item 4 of Schedule B to the Sales Tax (Persons Exempted From Payment Of Tax) Order 2018 [P.U.(A) 210/2018]: item 5 exempts Minister-approved manufacturers of animal feed products, item 6 Minister-approved manufacturers of fertilizer products and item 7 Minister-approved manufacturers of pesticide products, in each case from sales tax on goods solely used in that manufacture and subject to a certificate signed by the Director General. Effective 1 September 2026.
What changed in detail
The Sales Tax (Persons Exempted From Payment Of Tax) (Amendment) (No. 2) Order 2026, gazetted as P.U.(A) 303/2026 on 28 August 2026, inserts new items 5, 6 and 7 into Schedule B of the Sales Tax (Persons Exempted From Payment Of Tax) Order 2018. For each item the exempt person is “any manufacturer approved by the Director General”, the exempt goods are “the goods approved by the Minister of Finance” used solely in the manufacture of animal feed (item 5), fertilizer (item 6) or pesticide (item 7) products, and the exemption certificate is signed by the manufacturer itself. The manufacturer must also hold a manufacturing licence under the Industrial Co-ordination Act 1975 (or a MIDA exemption letter), and the goods must be imported, bought from a registered manufacturer, or moved from a licensed warehouse, licensed manufacturing warehouse or free zone. The Order took effect 1 September 2026.
What it means
Two approvals sit behind the exemption: the manufacturer must be approved by the Director General, and the goods must be ones the Minister of Finance has approved. It is not a blanket exemption for the three sectors. Manufacturers should confirm both before treating input purchases as exempt; claiming the Schedule B exemption without them would be a compliance error rather than a rate question.
Proof
Perintah ini mula berkuat kuasa pada 1 September 2026.This Order comes into force on 1 September 2026.
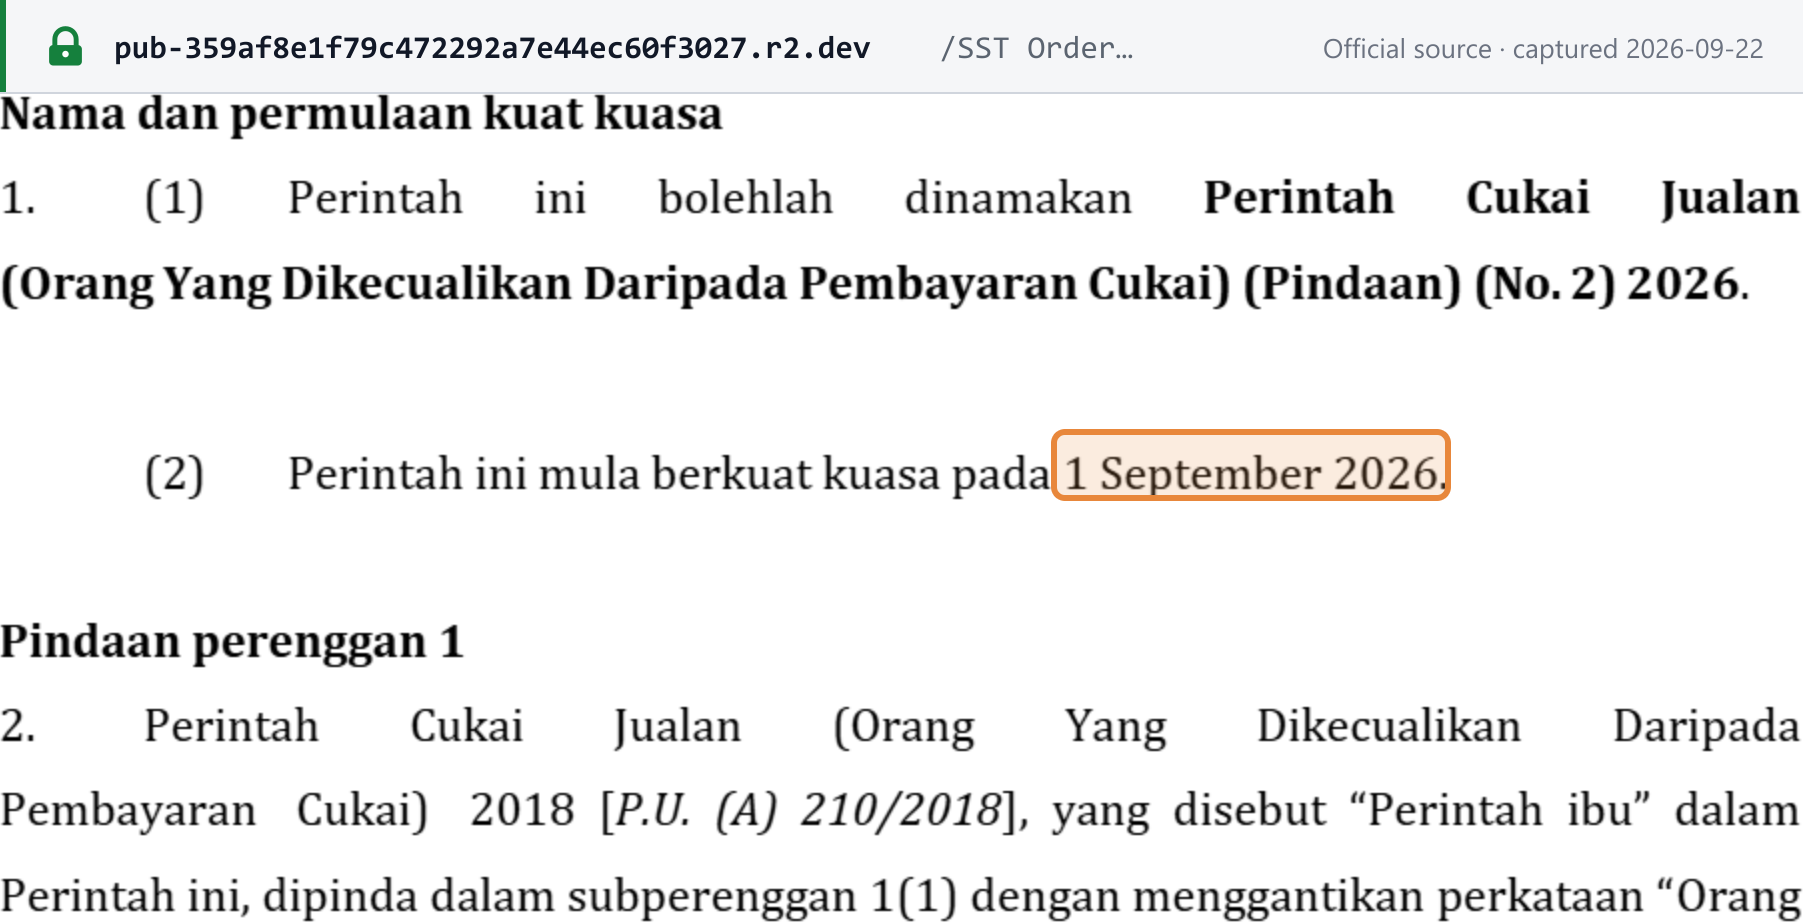 Source snapshot of the official page. Open full size ↗