Malaysia exempts employer-provided staff housing from service tax in special areas
This page records one dated change. For the rules in Malaysia as they stand today, see the Malaysia guide →
- Jurisdiction
- Malaysia
- Tax
- Service Tax
- Change type
- Update
- Status
- In force
- Impact
- Action required
- Announced
- 18 September 2026
- Effective
- 25 September 2026
- Authority
- Royal Malaysian Customs Department
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Providers of accommodation premises in Malaysia's special areas (Labuan, Langkawi, Tioman and the free zones) — employer-provided staff accommodation is now outside scope, so no service tax is due on it.
Stop charging service tax on employer-provided staff accommodation in special areas from 25 September 2026.
Tax engine
Malaysia's P.U.(A) 337/2026, made on 18 September 2026 and in operation from 25 September 2026, amends item 3 of the Schedule to P.U.(A) 212/2018 so that the taxable service in special areas is the provision of accommodation premises excluding accommodation premises provided by an employer as a facility to its employees.
What changed in detail
P.U.(A) 337/2026, made on 18 September 2026 and in operation from 25 September 2026, amends item 3 of the Schedule to P.U.(A) 212/2018 (the Service Tax Regulations for special areas). The taxable service — provision of accommodation premises in special areas — now expressly excludes accommodation premises provided by an employer as a facility to its employees. Before this amendment, the item covered accommodation premises in special areas without that carve-out.
What it means
Employers operating in Malaysia’s special areas (Labuan, Langkawi, Tioman and the free zones) that house staff on-site should stop charging service tax on that internal accommodation from 25 September 2026 — it is no longer a taxable supply under item 3. This does not touch commercial accommodation offered to paying guests in the same special areas, which remains taxable; the carve-out is narrowly for accommodation an employer provides to its own employees as a facility, not accommodation services sold to third parties.
Proof
Provision of accommodation premises in special areas excluding accommodation premises provided by an employer as a facility to his employees.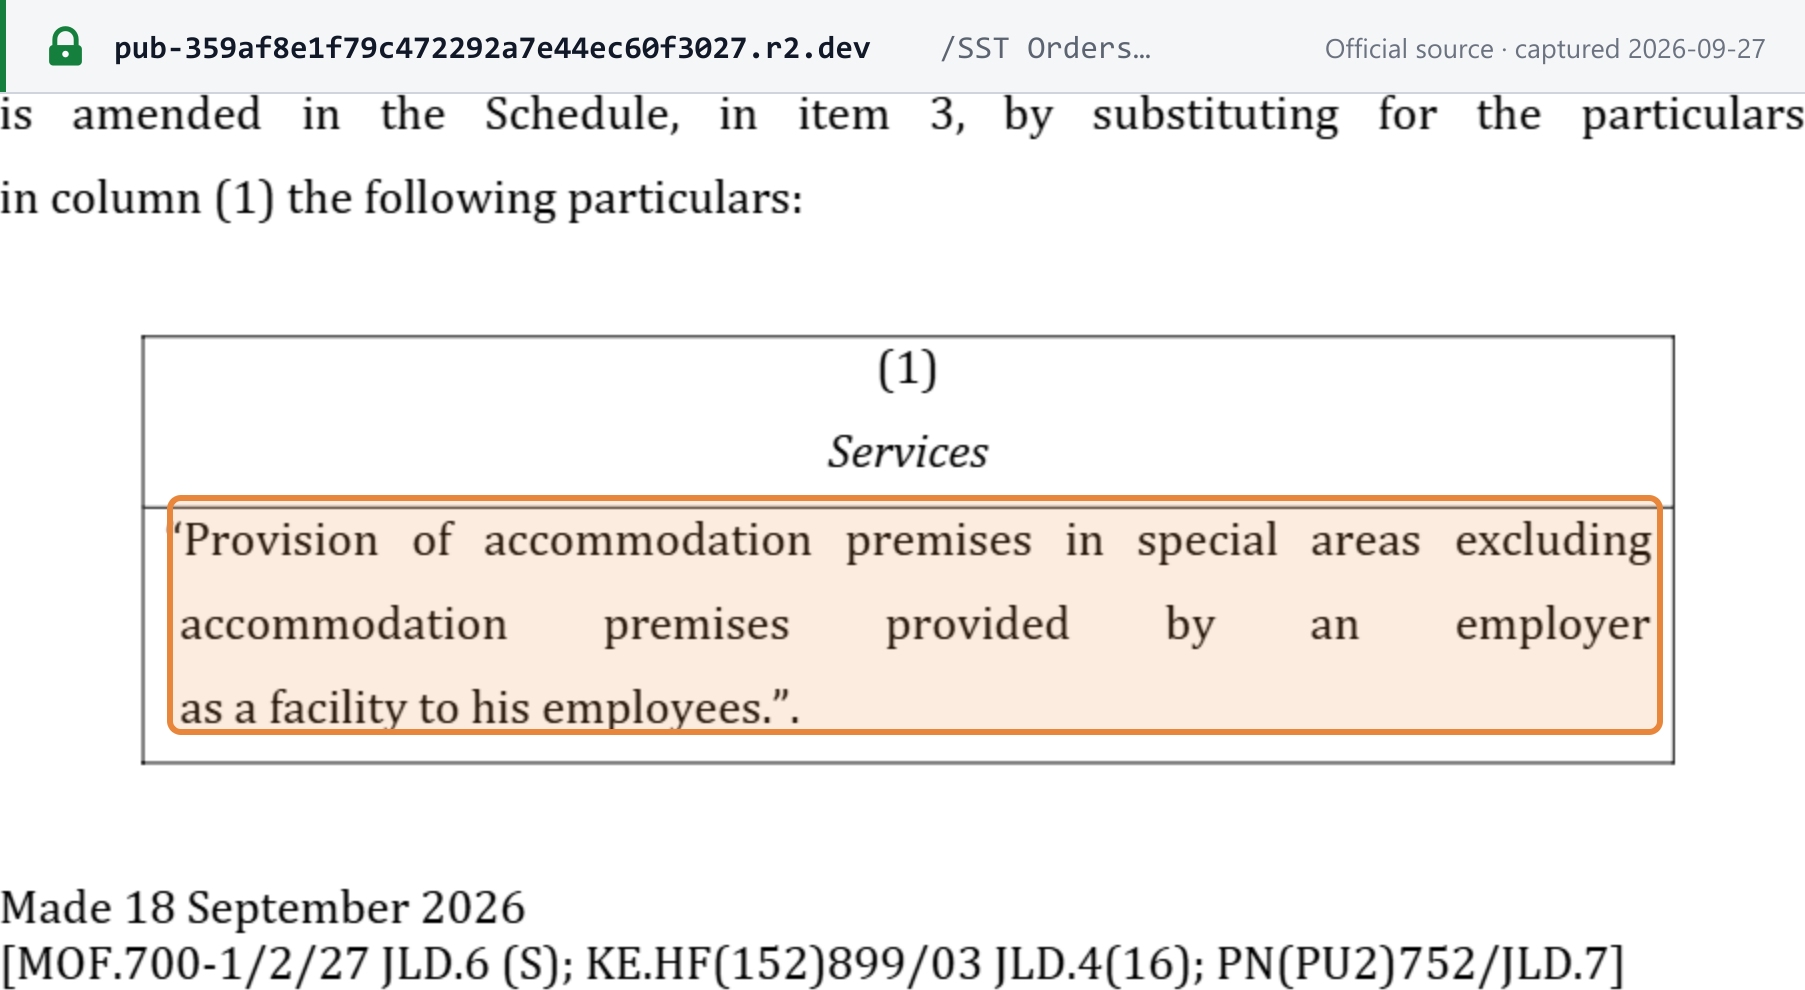 Source snapshot of the official page. Open full size ↗