Malaysia exempts Group L construction work for clients outside Malaysia from service tax, back to 1 July 2025
This page records one dated change. For the rules in Malaysia as they stand today, see the Malaysia guide →
- Jurisdiction
- Malaysia
- Tax
- Service Tax
- Change type
- Update
- Status
- In force
- Impact
- Plan ahead
- Announced
- 8 September 2026
- Effective
- 1 July 2025
- Authority
- Royal Malaysian Customs Department (RMCD)
- Systems
- Tax engine, Invoicing
- Verified
- Fetched from official source · high confidence
Malaysian service tax registrants under Group L (construction work) supplying offshore or onshore facility construction, or ship-to-floating-structure conversion, to clients outside Malaysia.
Group L (construction) service tax registrants exporting offshore/onshore facility construction or ship-to-floating-structure conversion services should confirm eligibility under STP 5/2026 (written, LHDN-stamped contract with an overseas client) and stop charging service tax on qualifying supplies from 1 July 2025 onward; no refund is available for tax already collected and remitted.
Tax engineInvoicing
Royal Malaysian Customs Department Service Tax Policy No. 5/2026, dated 8 September 2026, exempts Group L (construction work) service tax registered persons from charging and collecting service tax on construction work services for offshore and onshore facilities and on ship-to-floating-structure conversion services, where the service is provided to a client outside Malaysia under a written contract stamped by LHDN, with effect from 1 July 2025 until the project is completed or the contract expires. Recipients outside Malaysia are correspondingly exempt from paying the tax. No refund is given for service tax already paid.
What changed in detail
Service Tax Policy No. 5/2026, issued by the Royal Malaysian Customs Department and dated 8 September 2026, records a Ministry of Finance exemption granted under paragraph 34(3)(a) and subsection 34(4) of the Service Tax Act 2018, with effect from 1 July 2025.
It has two limbs. Recipients of the services from outside Malaysia are exempted from paying service tax on construction services for offshore and onshore facilities and structures, or the conversion of ships into floating structures, provided by construction service providers in Malaysia. Those Malaysian providers are correspondingly exempted from charging and collecting service tax on the same supplies to clients outside Malaysia.
Seven conditions attach. The provider must be a service tax registered person under Group L, First Schedule, Service Tax Regulations 2018. Each contract must be in writing, signed with the client outside Malaysia, and duly stamped for stamp duty by the Inland Revenue Board (LHDN). The exemption runs from 1 July 2025 until the project is completed or the contract expires. Every invoice must carry the statement “Service tax exemption under paragraph 34(3)(a) and subsection 34(4) of the Service Tax Act 2018 pursuant to Service Tax Policy No. 5/2026 dated 8 September 2026.” Any service tax collected from customers from 1 July 2025 onwards must still be paid to RMCD under section 26 of the Act, and no refund of it is granted to any party that paid it. Providers must retain the relevant documents for RMCD audit, and the recipient must be a client, entity or company not established in Malaysia.
What it means
The backdating is the sting. The exemption bites from 1 July 2025, but tax already collected is not refunded and must still be remitted — so a provider who charged service tax on qualifying work over the past fourteen months cannot recover it, and neither can the overseas client who bore it. That money is settled; only invoices from here are in play.
The condition that will decide most cases is the stamped contract. An exemption conditional on an LHDN-stamped written contract with an overseas client is one that fails on undocumented work orders, variation letters and open framework arrangements — which is how a good deal of offshore fabrication is actually papered. Check the stamping before relying on the policy, not after an audit asks.
The invoice wording is prescribed verbatim, policy number and date included. That is a billing template change, not a note in the file.
Proof
Service Tax Policy No. 5/2026 Source snapshot of the official page. Open full size ↗
Service Tax Policy No. 5/2026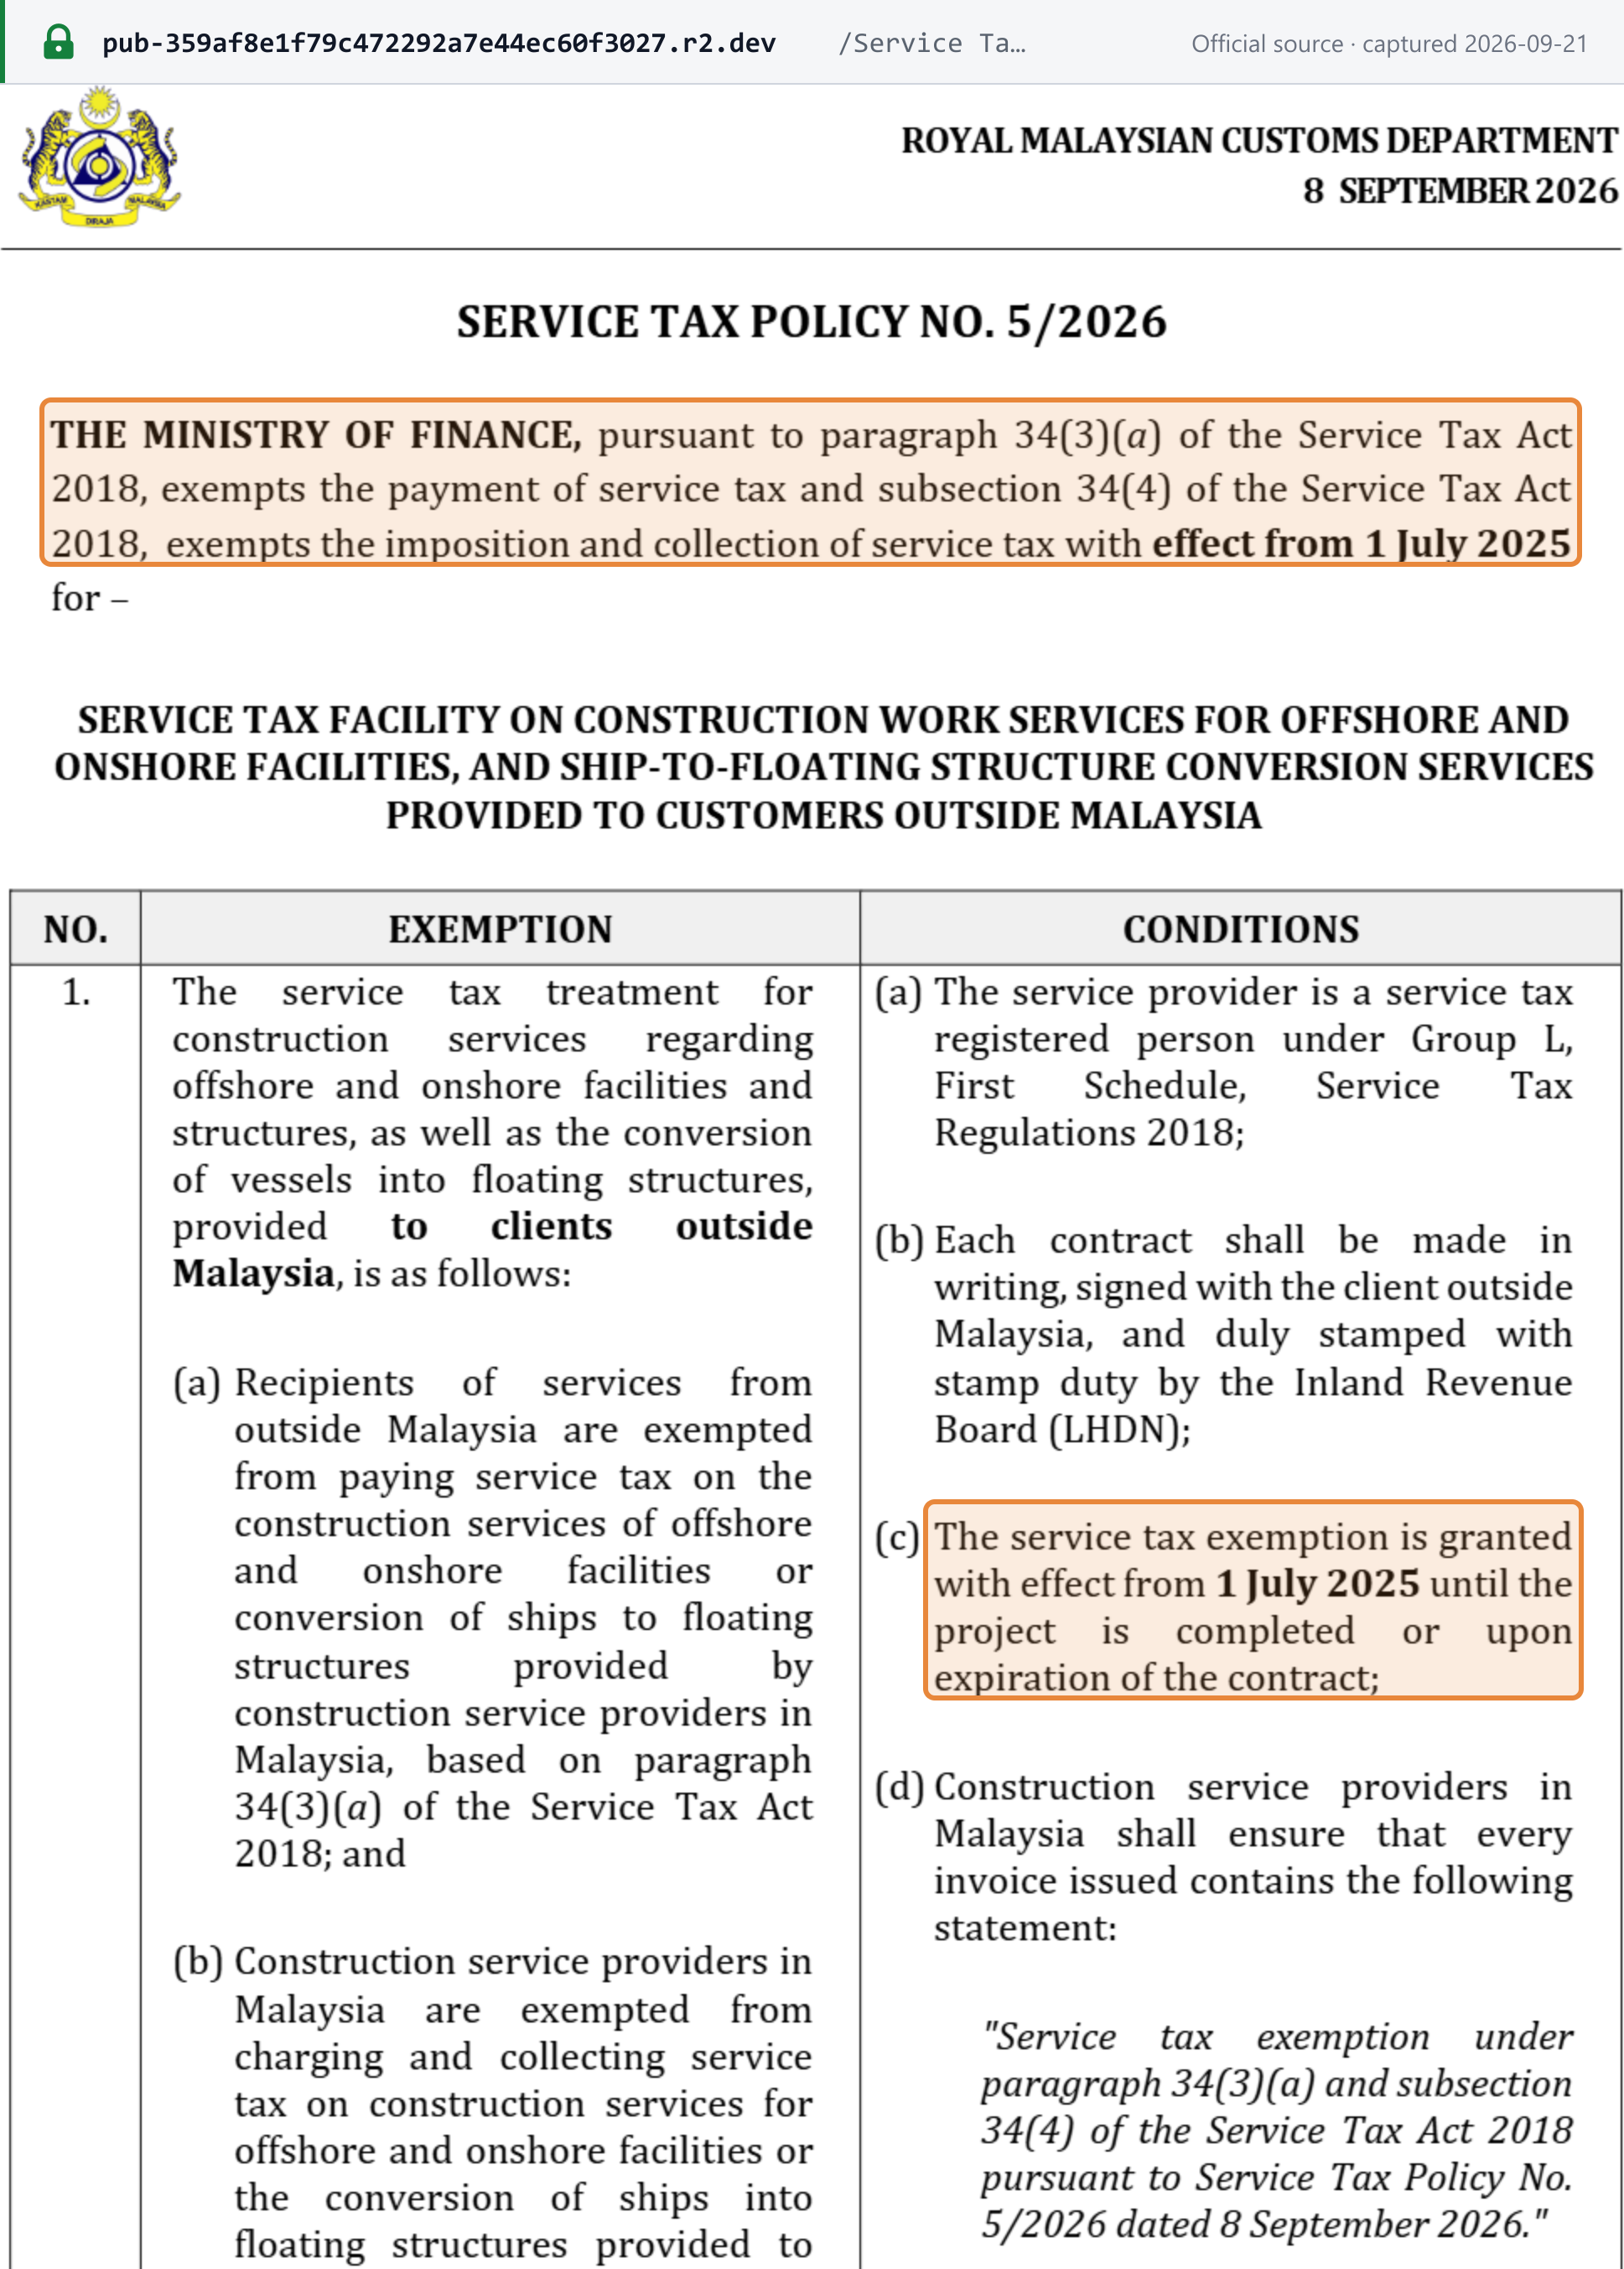 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Service Tax Policy No. 5/2026, Royal Malaysian Customs Department, 8 September 2026 · pub-359af8e1f79c472292a7e44ec60f3027.r2.dev