Sweden proposes making turnover the express main rule for apportioning mixed-use input VAT from 1 January 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Sweden as they stand today, see the Sweden guide →
- Jurisdiction
- Sweden
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- Plan ahead
- Announced
- 11 June 2026
- Effective
- 1 January 2027
- Authority
- Regeringen (Government Offices of Sweden)
- Systems
- ERP, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Swedish businesses with both taxable and exempt activity (mixed activity) that apportion input VAT, including those with building-related costs and certain financial activities.
Review input-VAT allocation keys for mixed (taxable/exempt) activities ahead of 1 January 2027; await the proposition.
ERPTax engineReporting
The Government referred to the Lagrådet (Council on Legislation) on 11 June 2026 a legislative proposal amending the VAT Act (2023:200) on apportionment of input VAT deduction in mixed activities: turnover becomes the express main rule, with exceptions including floor-area apportionment for VAT on goods and services relating to buildings and adjusted turnover for certain financial activities. Proposed to enter into force 1 January 2027; no government proposition to the Riksdag has yet been submitted.
What changed in detail
This is a proposal, not law. On 11 June 2026 the Government referred to the Lagrådet (Council on Legislation) a legislative proposal amending the VAT Act (2023:200) on the apportionment of input VAT deduction in mixed activities, meaning activities with both taxable and exempt transactions.
Turnover becomes the express main rule for the apportionment. The proposal also provides exceptions, including apportionment by floor area for VAT on goods and services relating to buildings, and adjusted turnover for certain financial activities, where certain taxable transactions are wholly or partly excluded from the turnover used.
The proposal is to enter into force on 1 January 2027. No government proposition to the Riksdag has yet been submitted.
What it means
A lagrådsremiss is the step before a government bill, so the text can still change and the 1 January 2027 date is a target. Do not change deduction methods yet.
The practical effect for mixed businesses would be a move to turnover as the default, with floor area for building-related VAT. Businesses that currently use other keys could model both methods to see the effect on deductible VAT.
Financial businesses should look at the adjusted-turnover exception, which changes the turnover figure used.
Proof
Förslagen innebär att det införs en uttrycklig huvudregel om att fördelningen ska göras med utgångspunkt i verksamhetens omsättning.The proposals mean that an express main rule is introduced that the apportionment is to be made on the basis of the turnover of the activity.
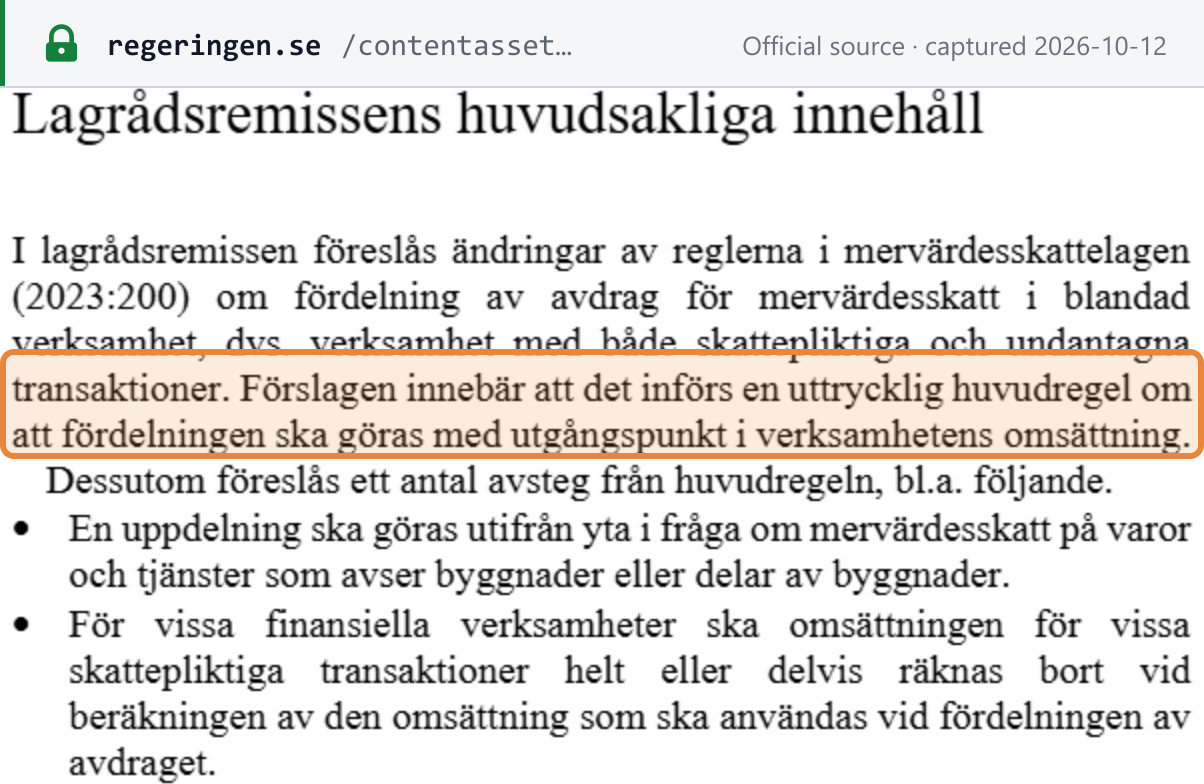 Source snapshot of the official page. Open full size ↗