UAE FTA Directive No. 3 of 2026 on digital-currency conversion is dated 14 July 2026
This page records one dated change. For the rules in United Arab Emirates as they stand today, see the United Arab Emirates guide →
- Jurisdiction
- United Arab Emirates
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 14 July 2026
- Effective
- 14 July 2026
- Instrument
- AE-FTA-DIR-3-2026
- Authority
- Federal Tax Authority (UAE)
- Verified
- Fetched from official source · high confidence
Anyone relying on the issue date of UAE Federal Tax Authority Directive on Tax Transactions No. 3 of 2026 — the directive setting the method for converting consideration received in digital currency into UAE dirhams. The substantive rule is unchanged, so this affects citation and effective-date reasoning rather than VAT treatment. Businesses accepting digital-currency consideration in the UAE should continue applying the conversion method as before.
No action — this corrects the recorded issue date of an existing directive. The substantive rule on converting digital-currency consideration into AED is unchanged.
Correction to ae-fta-directive-3-2026-digital-currency, which recorded the issue date of the UAE Federal Tax Authority's Directive on Tax Transactions No. 3 of 2026 as 17 July 2026. The Directive's own signature block states it was issued on 29 Muharram 1448H, corresponding to 14 July 2026; 17 July is the publication date shown on the tax.gov.ae portal rather than a date in the document. Directives No. 1, No. 4 and No. 5 of 2026 in this feed are all dated from their own signature blocks, so the earlier entry was internally inconsistent. The substance of the Directive — the method of converting the value of digital currencies into UAE dirhams — is unchanged.
What changed in detail
The UAE Federal Tax Authority’s Directive on Tax Transactions No. 3 of 2026 — which sets the method for converting the value of digital currencies into UAE dirhams for VAT purposes — was issued on 14 July 2026. The Directive PDF published on the FTA’s own legislation portal carries a signature block reading “Issued on 29 Muharram 1448H Corresponding to 14 July 2026”.
This supersedes ae-fta-directive-3-2026-digital-currency, which recorded the issue date as 17 July 2026.
The Directive PDF published on the FTA’s own legislation portal carries a signature block reading “Issued on 29 Muharram 1448H Corresponding to 14 July 2026”. The 17 July date is the publication date displayed in the portal’s metadata column, not a date appearing anywhere in the document.
Directives No. 1, No. 4 and No. 5 of 2026 in this feed are all dated from their own signature blocks, so the earlier entry was inconsistent with its siblings.
The substance of the Directive — the method for converting the value of digital currencies into UAE dirhams for VAT purposes — is unchanged.
What it means
The correction matters less for what it changes than for what it reveals about a recurring failure mode: taking a date from the page that hosts a document rather than from the document itself. A portal’s publish date is a fact about a website; an instrument’s issue date is a fact about the law.
This is the second time this specific confusion has been caught in this corpus, which is why the practice is now to read the signature block whenever an authority publishes PDFs behind a metadata table.
No system change follows from this record. It exists so that anyone citing Directive No. 3 cites the date the Directive gives itself.
Proof
Issued on 29 Muharram 1448H Corresponding to 14 July 2026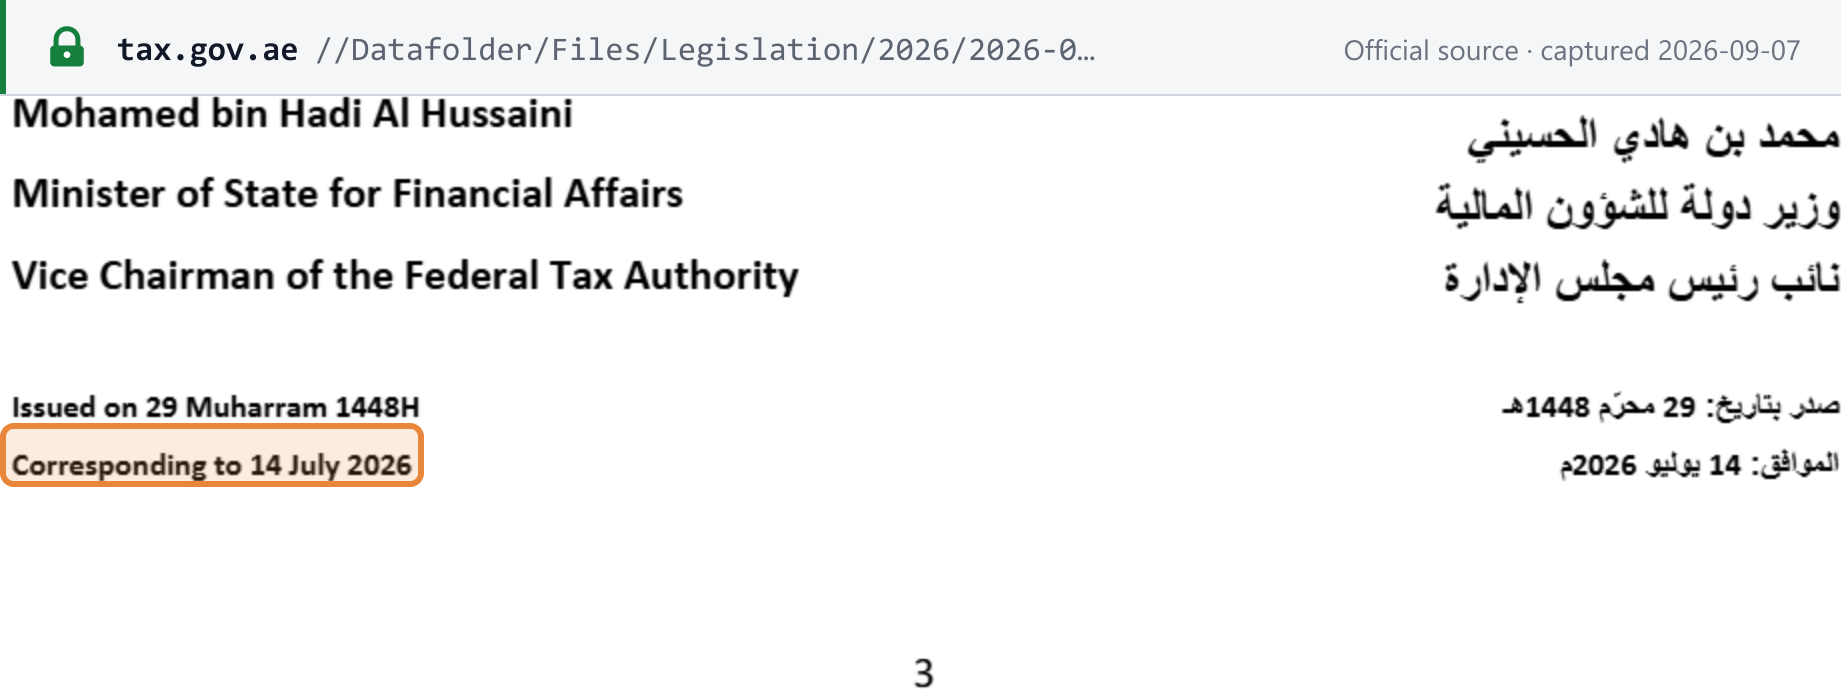 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- The UAE Federal Tax Authority issued Directive on Tax Transactions No. effective 17 July 2026