EU Commission proposes extending Northern Ireland's company-car fuel VAT flat rate to 31 December 2029 - not yet adopted
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in United Kingdom as they stand today, see the United Kingdom guide →
- Jurisdiction
- United Kingdom (Northern Ireland)
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- FYI
- Announced
- 29 September 2026
- Authority
- Council of the European Union
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Businesses in Northern Ireland that provide company cars used privately and account for VAT on the related fuel on a flat-rate basis.
No action - monitoring only; the current NI flat-rate authorisation runs to 31 Dec 2026 pending Council adoption.
Tax engine
On 29 September 2026 the European Commission proposed a Council Implementing Decision (COM(2026) 514 final, 2026/0291(NLE)) amending Implementing Decision (EU) 2021/512 to extend, until 31 December 2029, the UK's authorisation to fix on a flat-rate basis the proportion of VAT on fuel expenditure for company cars used privately in Northern Ireland. The current authorisation expires on 31 December 2026; the UK requested the extension on 25 March 2026. Council adoption requires unanimity and has not yet occurred.
What changed in detail
This is a proposal, not an adopted decision. On 29 September 2026 the European Commission proposed a Council Implementing Decision (COM(2026) 514 final, 2026/0291(NLE)) amending Implementing Decision (EU) 2021/512. The proposed Article 1 would authorise the United Kingdom, until 31 December 2029, to fix on a flat-rate basis, in respect of Northern Ireland, the proportion of VAT relating to expenditure on fuel used for private purposes in business cars.
The current authorisation expires on 31 December 2026. The UK requested the extension on 25 March 2026. The UK asked to continue applying the measure from 1 January 2027; the draft decision itself takes effect on the day of its notification.
Council adoption requires unanimity and has not yet occurred. Until it does, the existing authorisation, which runs to 31 December 2026, is the only one in place.
What it means
Nothing changes for Northern Ireland businesses today. The flat-rate fuel apportionment continues to 31 December 2026 and the proposal, if adopted, would carry it through 2029 without a gap.
The practical risk is timing: if the Council has not acted by the end of 2026, the authorisation lapses. Businesses and payroll or fuel-card systems that use the flat rate should keep a watch on the Council decision rather than assume continuity.
Proof
the United Kingdom is authorised, until 31 December 2029, to fix, in respect of Northern Ireland, on a flat-rate basis, the proportion of VAT relating to expenditure on fuel used for private purposes in business cars.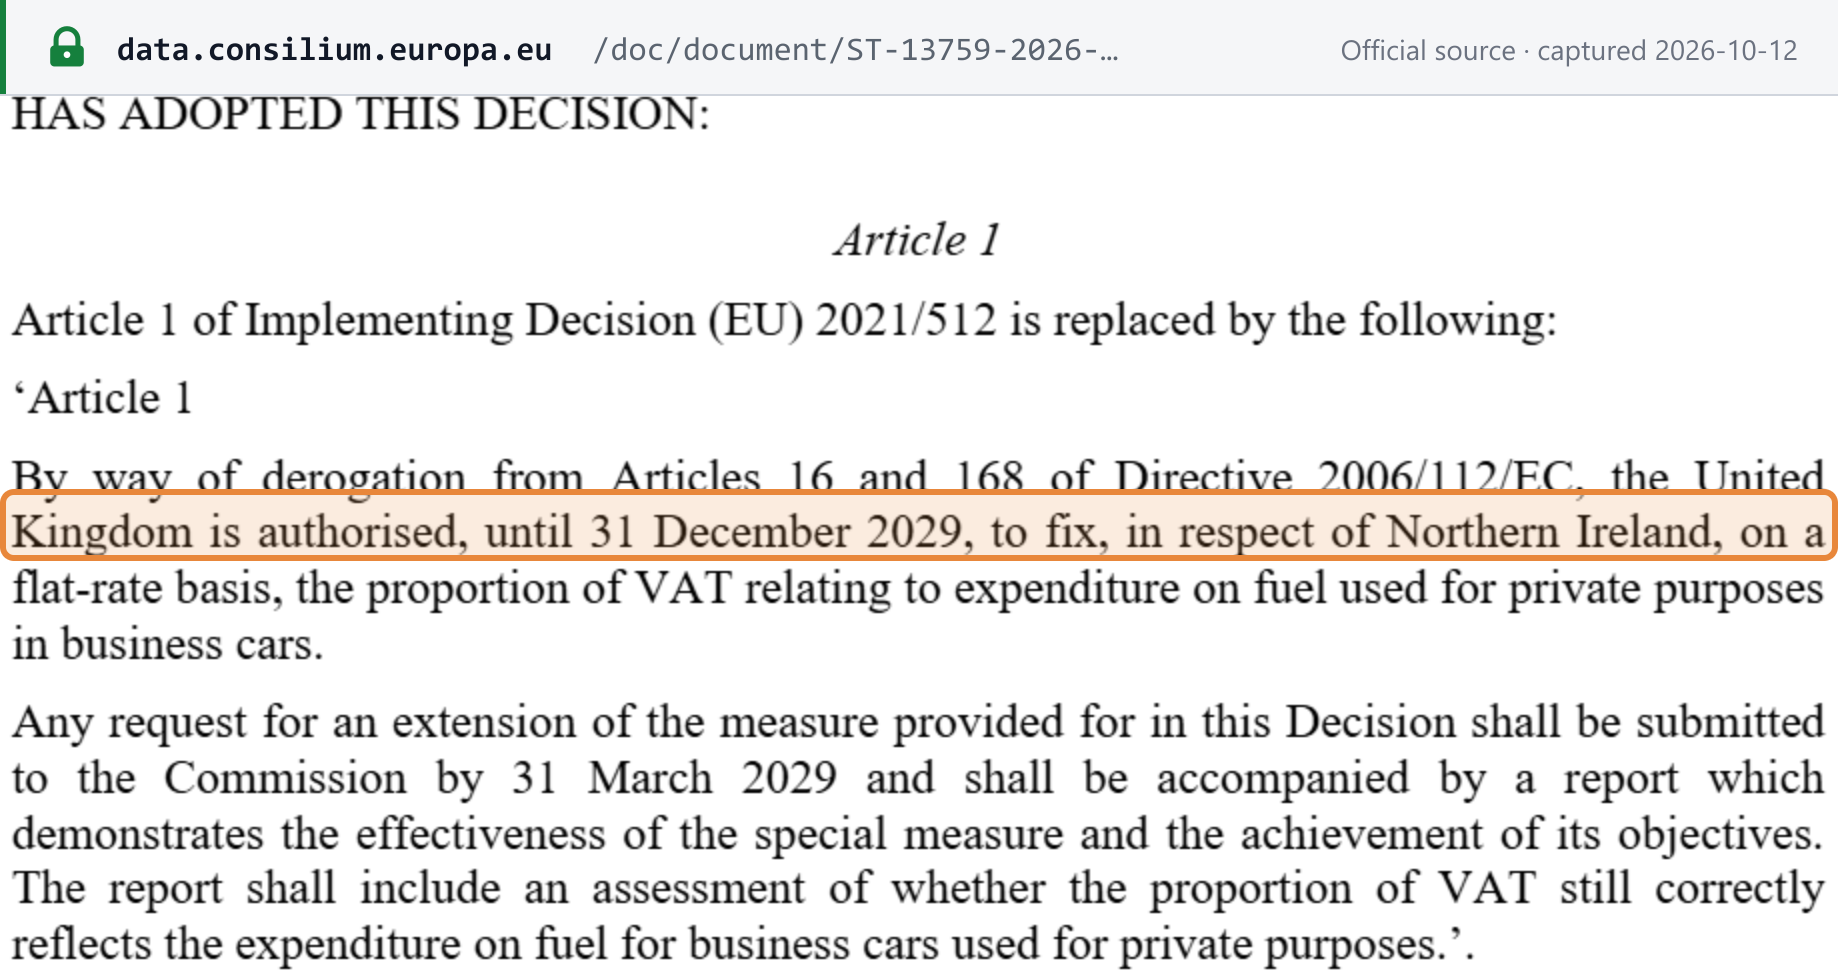 Source snapshot of the official page. Open full size ↗