Tennessee's money transmission sales tax, due 1 January 2027, will not be enforced until litigation ends
This page records one dated change. For the rules in United States as they stand today, see the United States guide →
- Jurisdiction
- United States
- Tax
- Sales tax
- Change type
- Update
- Status
- Enacted
- Impact
- Watch
- Effective
- 1 January 2027
- Authority
- Tennessee Department of Revenue
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Entities licensed under the Tennessee Money Transmission Modernization Act that send money from Tennessee to locations outside the United States.
Do not enable the tax yet; monitor the Davidson County Chancery Court litigation.
Tax engineReporting
Tennessee Public Chapter 1035 (2026) imposes sales tax (USD 10 per transaction plus 2% of the amount over USD 500) on money transmission from Tennessee to locations outside the United States, effective 1 January 2027, for entities licensed under the Tennessee Money Transmission Modernization Act. Notice 26-12 (updated August 2026) states that under an agreed order of the Davidson County Chancery Court the Department will not enforce the law until a final judicial determination, followed by a 45-day grace period if upheld.
What changed in detail
Tennessee Public Chapter 1035 (2026) imposes sales tax on money transmission from Tennessee to locations outside the United States: USD 10 per transaction plus 2% of the amount over USD 500. It applies from 1 January 2027 to entities licensed under the Tennessee Money Transmission Modernization Act.
Department of Revenue Notice 26-12 (updated August 2026) states that, under an agreed order of the Davidson County Chancery Court, the Department will not enforce the law until a final judicial determination. If the law is upheld, a 45-day grace period follows.
What it means
The statute is on the books with a 1 January 2027 date, but the Department’s own notice says it will not collect until the litigation concludes. Do not read the stay as a repeal: if the courts uphold the tax, licensees get 45 days before enforcement begins.
Licensees should keep the transaction data needed to compute the tax, and watch the court case rather than the calendar.
Proof
While the tax described below was originally scheduled to go into effect January 1, 2027, it will not be enforced until the litigation concludes.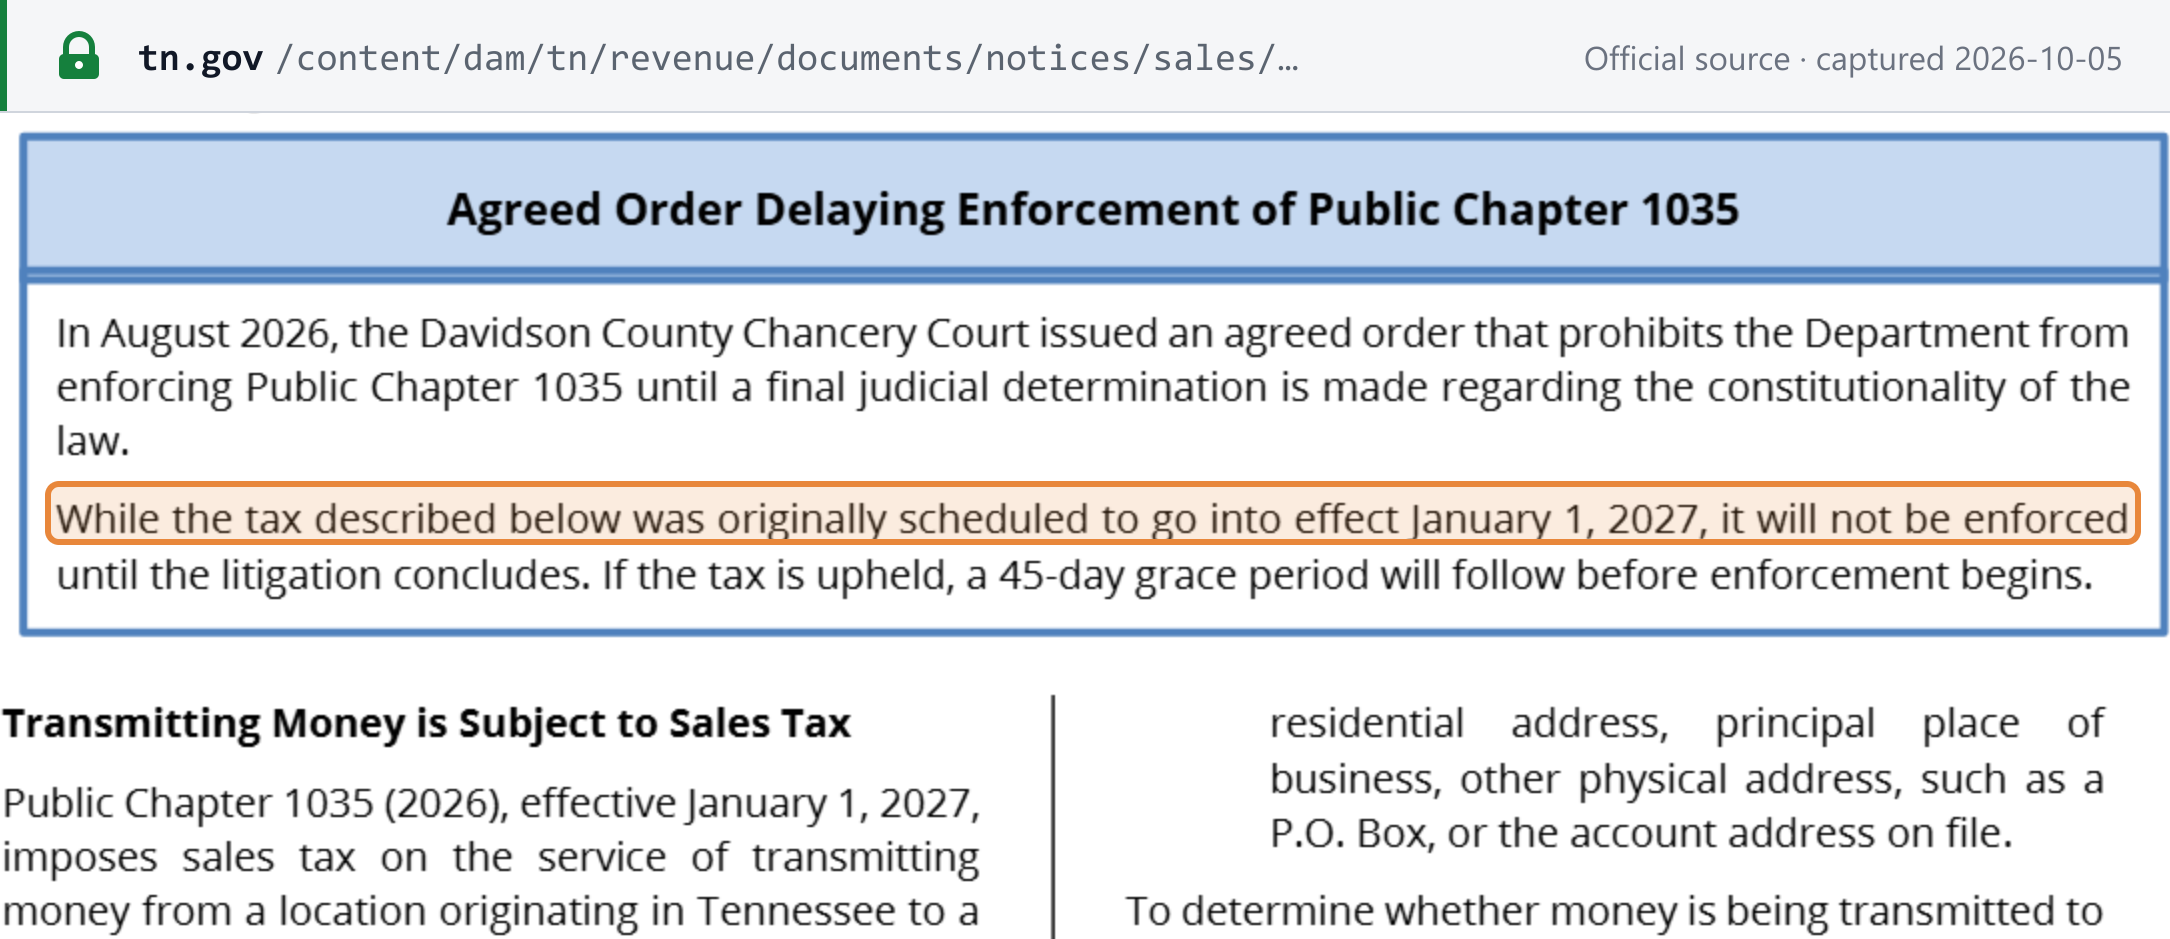 Source snapshot of the official page. Open full size ↗