Vietnam extends the VAT relief on petroleum products to 31 December 2026 under Government Resolution 43/2026/NQ-CP
This page records one dated change. For the rules in Vietnam as they stand today, see the Vietnam guide →
- Jurisdiction
- Vietnam
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Plan ahead
- Announced
- 30 September 2026
- Effective
- 1 October 2026
- Authority
- Chính phủ (Government of Vietnam)
- Systems
- Tax engine, ERP, Invoicing
- Verified
- Fetched from official source · high confidence
Businesses supplying gasoline, oil, petroleum feedstocks and jet fuel in Vietnam, and importers of the goods covered by the extended preferential import duty rates.
Keep the VAT treatment of petroleum supplies per Resolution 19/2026/QH16 through 31 Dec 2026; plan for expiry unless extended again.
Tax engineERPInvoicing
Government Resolution No. 43/2026/NQ-CP (30 September 2026, effective 1 October 2026 to 31 December 2026) extends to 31 December 2026 the application of National Assembly Resolution 19/2026/QH16 as regards environmental protection tax and value added tax on gasoline, oil, petroleum feedstocks and jet fuel, and extends to the same date the preferential import duty rates under Resolution 25/2026/NQ-CP and Decree 72/2026/ND-CP. Excise tax on gasoline follows the Special Consumption Tax Law 66/2025/QH15.
What changed in detail
Vietnam’s Government issued Resolution No. 43/2026/NQ-CP on 30 September 2026, effective from 1 October 2026 to 31 December 2026.
The resolution extends to 31 December 2026 the application of National Assembly Resolution 19/2026/QH16 of 12 April 2026 as regards environmental protection tax and value added tax on gasoline, oil, petroleum feedstocks and jet fuel. It also extends to the same date the preferential import duty rates under Resolution 25/2026/NQ-CP and Decree 72/2026/ND-CP.
Excise tax on gasoline is not changed by the resolution: it follows the Special Consumption Tax Law 66/2025/QH15.
This extends the treatment recorded in vn-resolution-19-fuel-exemption-2026.
What it means
The relief now runs to 31 December 2026, and the resolution itself is time-limited to that date. Petroleum supplies invoiced from 1 October should continue to follow the Resolution 19/2026/QH16 treatment rather than the ordinary rules.
The resolution lets the Government shorten or extend its validity on a proposal from the Ministry of Industry and Trade through the Ministry of Finance (Article 3(3)), so the end date can still move. ERP and invoicing configurations that apply the relief should carry an end date of 31 December 2026 and a review trigger, so the return to the ordinary treatment is a planned change rather than a year-end surprise.
Excise on gasoline is a separate regime and should not be treated as covered by this resolution.
Proof
Kéo dài thời hạn áp dụng Nghị quyết số 19/2026/QH16 ngày 12 tháng 4 năm 2026 của Quốc hội đến hết ngày 31 tháng 12 năm 2026 đối với thuế bảo vệ môi trường và thuế giá trị gia tăng quy định tại Điều 1 và Điều 2 Nghị quyết số 19/2026/QH16.Extend the application period of Resolution No. 19/2026/QH16 of 12 April 2026 of the National Assembly until the end of 31 December 2026 for environmental protection tax and value added tax prescribed in Articles 1 and 2 of Resolution No. 19/2026/QH16.
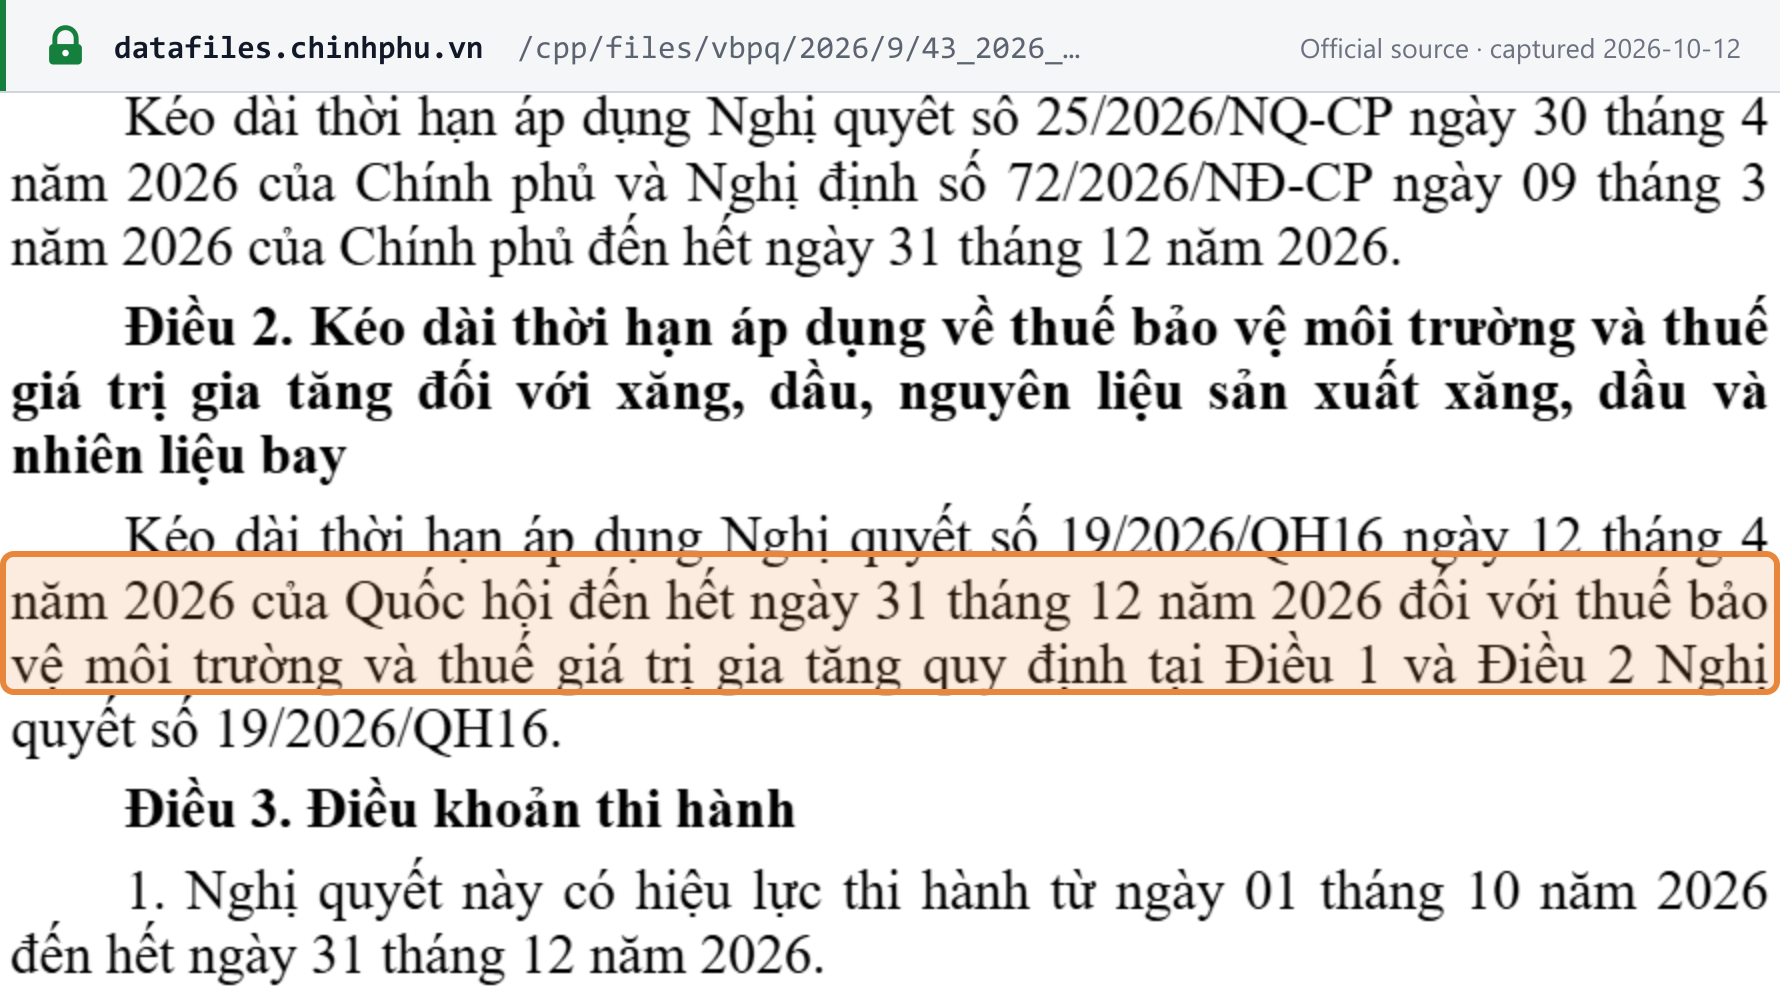 Source snapshot of the official page. Open full size ↗