Spain's Real Decreto-ley 29/2026 makes short-stay furnished lettings subject to 10% VAT from 1 December 2026
This page records one dated change. For the rules in Spain as they stand today, see the Spain guide →
- Jurisdiction
- Spain
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 7 October 2026
- Effective
- 1 December 2026
- Authority
- Boletín Oficial del Estado (BOE)
- Systems
- Tax engine, Invoicing, E-commerce, ERP
- Verified
- Fetched from official source · high confidence
Landlords of furnished apartments or dwellings let with hotel-type services or for no more than 30 nights to the same tenant, and owners of dwellings let as a habitual residence that undergo renovation or repair works.
Configure VAT treatment for Spanish furnished short-stay lettings (30 nights or fewer) and dwelling renovation lettings from 1 December 2026; monitor Congreso convalidation.
Tax engineInvoicingE-commerceERP
Real Decreto-ley 29/2026 of 6 October 2026 (BOE no. 249, 7 October 2026, BOE-A-2026-20823; in force 8 October 2026) amends the VAT Act (Ley 37/1992) with effect from 1 December 2026: furnished apartment or dwelling lettings with hotel-type complementary services, or lasting no more than 30 nights to the same tenant and not the landlord's habitual residence, cease to be exempt under art. 20.Uno.23.e') and are brought under the 10% reduced rate in art. 91.Uno.2.2.; the reduced rate is extended to renovation and repair works on dwellings let as habitual residence whatever the landlord's status; and protected dwellings with permanent or indefinite protection delivered by their promoters join the super-reduced rate list (art. 91.Dos.1.6.). The decree-law must be validated by the Congreso within 30 days of promulgation; it re-enacts the housing package of Real Decreto-ley 26/2026 (29 September 2026), whose derogation the Congreso ordered published on 2 October 2026.
What changed in detail
Real Decreto-ley 29/2026 of 6 October 2026 was published in the BOE no. 249 on 7 October 2026 (BOE-A-2026-20823) and is in force from 8 October 2026. It amends the VAT Act (Ley 37/1992) with effect from 1 December 2026:
- Furnished apartment or dwelling lettings with hotel-type complementary services, or lasting no more than 30 nights to the same tenant and not the landlord’s habitual residence, cease to be exempt under art. 20.Uno.23.e’) and are brought under the 10% reduced rate in art. 91.Uno.2.2.
- The reduced rate is extended to renovation and repair works on dwellings let as habitual residence, whatever the landlord’s status.
- Protected dwellings with permanent or indefinite protection, delivered by their promoters, join the super-reduced rate list (art. 91.Dos.1.6.).
The decree-law must be validated by the Congreso within 30 days of promulgation. It re-enacts the housing package of Real Decreto-ley 26/2026 (29 September 2026), whose derogation the Congreso ordered published on 2 October 2026.
What it means
The change turns a VAT-exempt activity into a taxable one for short-stay landlords. Moving from exemption to the 10% rate generally means VAT must be charged and accounted for on these lettings, and the interaction with input VAT recovery should be reviewed before 1 December 2026.
Validation by the Congreso is still pending, and the previous version of this package was derogated, so the rules could change. Configure the treatment for the December start, but keep it flagged as dependent on convalidation until the vote.
Proof
Los arrendamientos de apartamentos o viviendas amueblados cuando concurran cualquiera de las siguientes circunstancias: – El arrendador se obligue a la prestación de alguno de los servicios complementarios propios de la industria hotelera, tales como los de restaurante, limpieza, lavado de ropa u otros análogos. – Su duración a favor de un mismo arrendatario no supere las 30 noches, excepto si se produce en el apartamento o vivienda arrendada en la que el arrendador tenga su residencia habitual, en cuyo caso estarán exentos.Lettings of furnished apartments or dwellings where any of the following circumstances apply: – The landlord undertakes to provide some of the complementary services typical of the hotel industry, such as restaurant, cleaning, laundry or similar. – The duration for the same tenant does not exceed 30 nights, unless it takes place in the apartment or dwelling that is the landlord's habitual residence, in which case they are exempt.
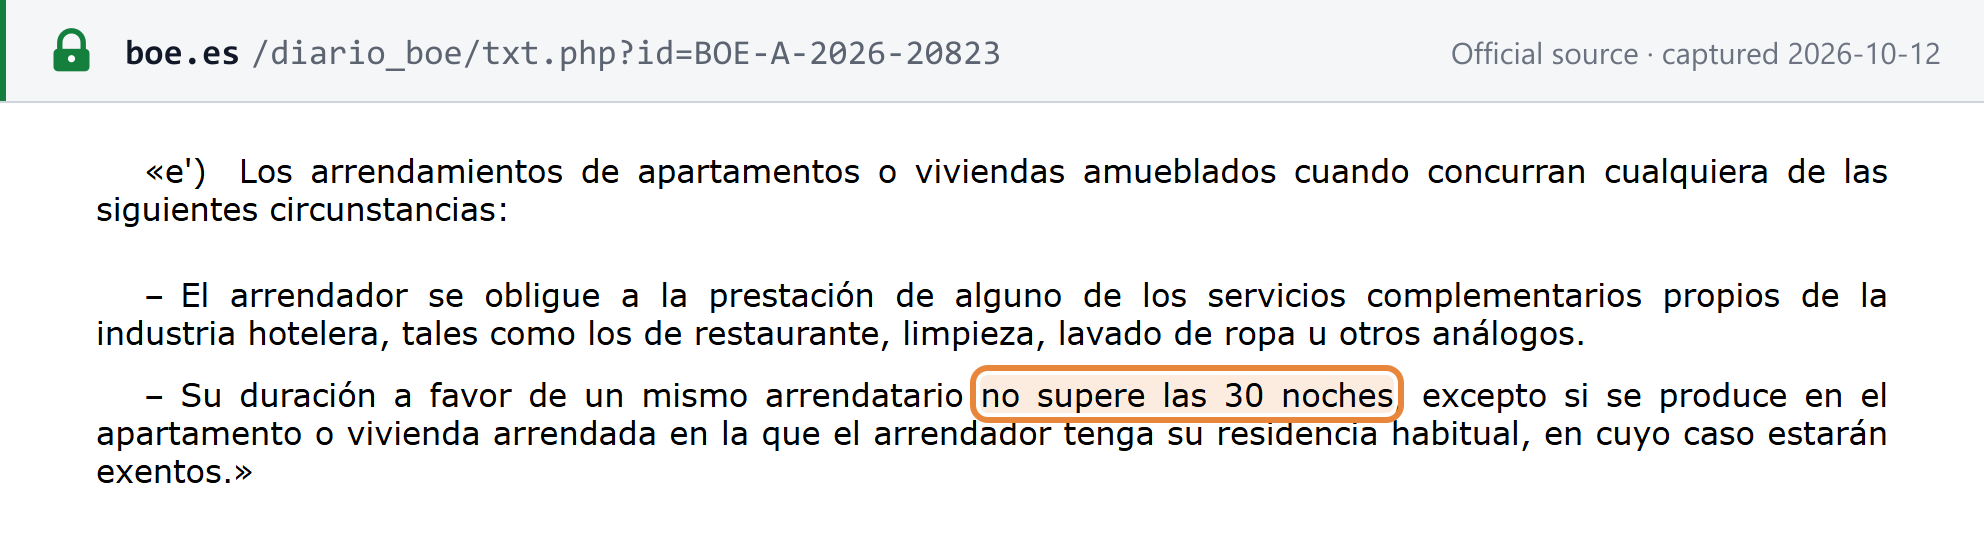 Source snapshot of the official page. Open full size ↗