Spain's B2B e-invoicing starts 6 October 2027 for businesses above EUR 8 million and 6 October 2028 for all others
This page records one dated change. For the rules in Spain as they stand today, see the Spain guide →
- Jurisdiction
- Spain
- Tax
- VAT
- Change type
- E-invoicing
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 5 October 2026
- Effective
- 6 October 2027
- Instrument
- ES-ORDEN-HAC-1028-2026
- Authority
- Boletín Oficial del Estado (BOE)
- Systems
- ERP, Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Spanish businesses and professionals invoicing other businesses: volume of operations above EUR 8 million from 6 October 2027, all others from 6 October 2028.
Plan Spanish B2B e-invoicing (issue, send, receive, status and payment reporting, UBL copy to the AEAT public solution) for 6 October 2027 if volume of operations exceeds EUR 8 million, otherwise 6 October 2028.
ERPInvoicingReporting
Spain published Orden HAC/1028/2026, de 2 de octubre (BOE-A-2026-20587, BOE no. 247 of 5 October 2026), which regulates the AEAT public e-invoicing solution (solución pública de facturación electrónica) under the third final provision of Real Decreto 238/2026 and entered into force on 6 October 2026. Its entry into force starts the periods in the eighth final provision of Ley 18/2022 and in Real Decreto 238/2026. The AEAT states that, counted from 6 October 2026, the B2B obligations apply: from 6 October 2027 to businesses and professionals with a volume of operations above EUR 8 million (issue, send and receive e-invoices, and report invoice status and payments); from 6 October 2028 to all other businesses and professionals (issue, send and receive), with legal persons at or below EUR 8 million also reporting status and payments from that date; and from 6 October 2029 to natural persons and entities under the attribution-of-income regime for status and payment reporting. Businesses not issuing through the public solution must send it a faithful electronic copy of each invoice in UBL syntax at the time of issue. This supersedes es-royal-decree-238-b2b-einvoicing-2026, which stated that the ministerial order had not yet issued.
What changed in detail
Spain published Orden HAC/1028/2026, de 2 de octubre in the BOE on 5 October 2026 (BOE-A-2026-20587, BOE no. 247). The order regulates the AEAT’s public e-invoicing solution (solución pública de facturación electrónica) under the third final provision of Real Decreto 238/2026, and it entered into force on 6 October 2026.
Its entry into force starts the periods in the eighth final provision of Ley 18/2022 and in Real Decreto 238/2026. The AEAT counts the obligations from 6 October 2026:
| From | Who | Obligation |
|---|---|---|
| 6 October 2027 | Businesses and professionals with a volume of operations above EUR 8 million | Issue, send and receive e-invoices; report invoice status and payments |
| 6 October 2028 | All other businesses and professionals | Issue, send and receive e-invoices. Legal persons at or below EUR 8 million also report status and payments |
| 6 October 2029 | Natural persons and entities under the attribution-of-income regime at or below EUR 8 million | Report invoice status and payments |
Where a business does not issue or exchange invoices through the public solution, the platform or system it uses must send the public solution a faithful electronic copy of each invoice, in UBL syntax, at the time of issue. Invoices issued or exchanged through the public solution need no copy. The public solution must be available at least two months before the first obligations apply.
This replaces the position recorded in royal-decree-238-b2b-einvoicing-2026, which said the order had not yet issued.
What it means
The dates are now fixed. The April 2026 draft order planned to enter into force on 1 October 2026, which would have given 1 October 2027 and 1 October 2028; the final dates are five days later. Plans built on the earlier dates still work, but the dates themselves should be corrected.
The EUR 8 million test uses the volume of operations of the preceding calendar year, the same measure used elsewhere in Spanish VAT, not invoiced turnover.
The UBL copy obligation is the part most likely to be missed. It applies even to businesses that exchange Facturae or EDIFACT through a private platform. Confirm that your platform provider will submit the copy for you.
Proof
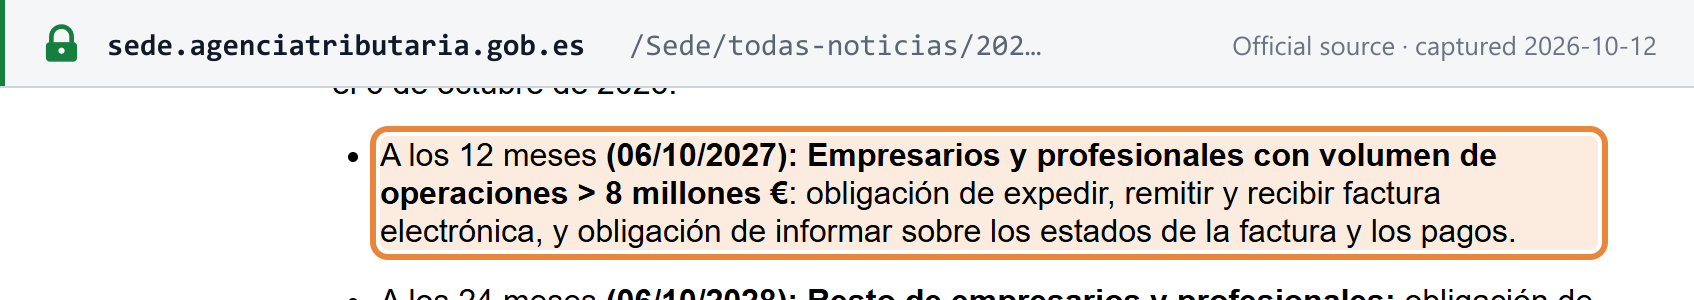
A los 12 meses (06/10/2027): Empresarios y profesionales con volumen de operaciones > 8 millones €: obligación de expedir, remitir y recibir factura electrónica, y obligación de informar sobre los estados de la factura y los pagos.At 12 months (06/10/2027): businesses and professionals with a volume of operations above EUR 8 million: obligation to issue, send and receive electronic invoices, and obligation to report on invoice status and payments.
 Source snapshot of the official page. Open full size ↗
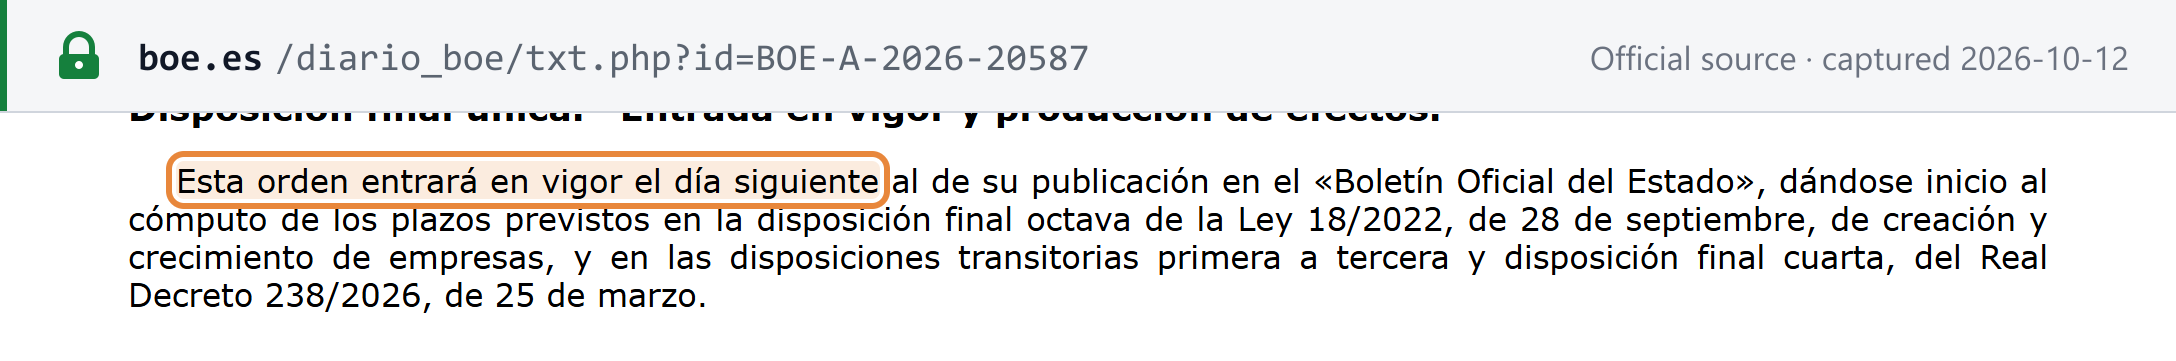
Esta orden entrará en vigor el día siguiente al de su publicación en el «Boletín Oficial del Estado», dándose inicio al cómputo de los plazos previstos en la disposición final octava de la Ley 18/2022, de 28 de septiembre, de creación y crecimiento de empresas, y en las disposiciones transitorias primera a tercera y disposición final cuarta, del Real Decreto 238/2026, de 25 de marzo.This order shall enter into force on the day following its publication in the Official State Gazette, starting the periods provided for in the eighth final provision of Law 18/2022 of 28 September on the creation and growth of companies, and in the first to third transitional provisions and fourth final provision of Royal Decree 238/2026 of 25 March.
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BOE-A-2026-20587 — Orden HAC/1028/2026, de 2 de octubre; BOE núm. 247, de 5 de octubre de 2026, pp. 129349-129390 · www.boe.es