North Carolina gives remote sellers at least 60 days to register after crossing the sales threshold, from 2 July 2026
This page records one dated change. For the rules in United States — North Carolina as they stand today, see the United States — North Carolina guide →
- Jurisdiction
- United States — North Carolina
- Tax
- Sales and use tax
- Change type
- Threshold
- Status
- In force
- Impact
- Plan ahead
- Announced
- 6 August 2026
- Effective
- 2 July 2026
- Authority
- North Carolina Department of Revenue
- Systems
- Tax engine, E-commerce, Reporting
- Verified
- Fetched from official source · high confidence
Remote sellers engaged in business in North Carolina only because they exceed the $100,000 gross sales threshold.
Review NC remote-seller registration trigger logic: collection starts first day of month at least 60 days after crossing threshold.
Tax engineE-commerceReporting
North Carolina Session Law 2026-31, section 3.1, effective 2 July 2026: a remote seller that is engaged in business only because it exceeds the sales thresholds ($100,000 of gross sales sourced to NC) is engaged in business on the first day of the first calendar month beginning at least 60 days after exceeding the threshold, giving at least 60 days to register and begin collecting.
What changed in detail
The North Carolina Department of Revenue issued an important notice on 6 August 2026 on Session Law 2026-31, section 3.1, effective 2 July 2026.
A remote seller that is engaged in business only because it exceeds the sales thresholds ($100,000 of gross sales sourced to North Carolina) is engaged in business on the first day of the first calendar month that begins at least 60 days after it exceeds the threshold. That gives the seller at least 60 days to register and begin collecting and remitting sales and use tax.
The additional time applies only to remote sellers that do not meet any other condition in G.S. 105-164.8(b). The change applies only to retailers that exceed the sales thresholds on or after 2 July 2026; earlier threshold crossings remain subject to the law in effect at the time.
What it means
The collection start date is now the first day of the month that begins at least 60 days after the threshold is crossed, so the lag depends on when in the month the threshold is crossed.
Sellers should record the date the $100,000 threshold was crossed, since that date drives the start of collection. Registration should still be completed before the collection start date.
The relief does not apply to a seller that meets another condition for being engaged in business, so check which condition applies to you before relying on the 60 days.
Proof
Effective July 2, 2026, a Remote Seller that solely exceeds the Sales Thresholds is allowed at least 60 days to register and begin collecting and remitting sales and use tax.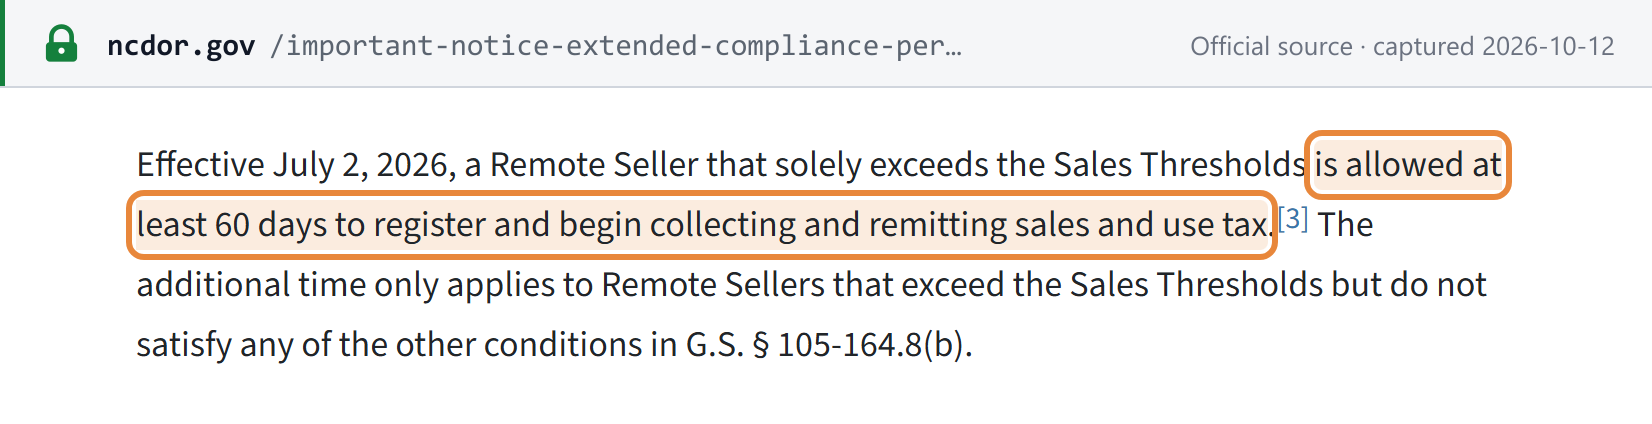 Source snapshot of the official page. Open full size ↗