Washington adds a sales tax on peer-to-peer car sharing from 1 January 2027
This page records one dated change. For the rules in United States as they stand today, see the United States guide →
- Jurisdiction
- United States
- Tax
- Sales and use tax
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Effective
- 1 January 2027
- Authority
- Washington State Department of Revenue
- Systems
- Tax engine, E-commerce, Reporting
- Verified
- Fetched from official source · high confidence
Owners of vehicles shared peer-to-peer in Washington who obtained the vehicle for resale using a reseller permit or exemption certificate.
Peer-to-peer car-sharing platforms: collect an owner declaration/electronic certification on resale or exemption-certificate acquisition and configure the extra 9.9% tax class before 1 January 2027.
Tax engineE-commerceReporting
Section 9 of Engrossed Substitute Senate Bill 6113 (Chapter 250, Laws of 2026, partial veto) amends RCW 82.08.020 to levy, from 1 January 2027, an additional tax on peer-to-peer car sharing transactions equal to the selling price multiplied by the retail car rental tax rate in RCW 82.08.020(2)(a), which is 9.9% from 1 January 2027. It applies only where the vehicle owner obtained the shared vehicle for resale using a reseller permit or an approved exemption certificate under RCW 82.04.470; revenue goes to the multimodal transportation account. RCW 82.08.020 was separately amended by 2026 c 255 s 101, and the code reviser incorporated both amendments.
What changed in detail
Section 9 of Engrossed Substitute Senate Bill 6113 (Chapter 250, Laws of 2026, partial veto) amends RCW 82.08.020. From 1 January 2027 it levies an additional tax on peer-to-peer car sharing transactions equal to the selling price multiplied by the retail car rental tax rate in RCW 82.08.020(2)(a), which is 9.9% from 1 January 2027.
It applies only where the vehicle owner obtained the shared vehicle for resale using a reseller permit or an approved exemption certificate under RCW 82.04.470. Revenue goes to the multimodal transportation account.
RCW 82.08.020 was separately amended by 2026 c 255 s 101, and the code reviser incorporated both amendments.
What it means
The scope is narrow: the extra tax is triggered by how the owner acquired the car, namely for resale under a reseller permit or exemption certificate, not by car sharing as such. Owners and platforms need to know which vehicles were bought that way.
The rate follows the retail car rental rate, so a change to that rate would carry through. The 9.9% figure is the rate stated for 1 January 2027.
Proof
(b)(i) Beginning January 1, 2027, there is levied and collected an additional tax on peer-to-peer car sharing transactions equal to the selling price multiplied by the rate of tax imposed under (a) of this subsection.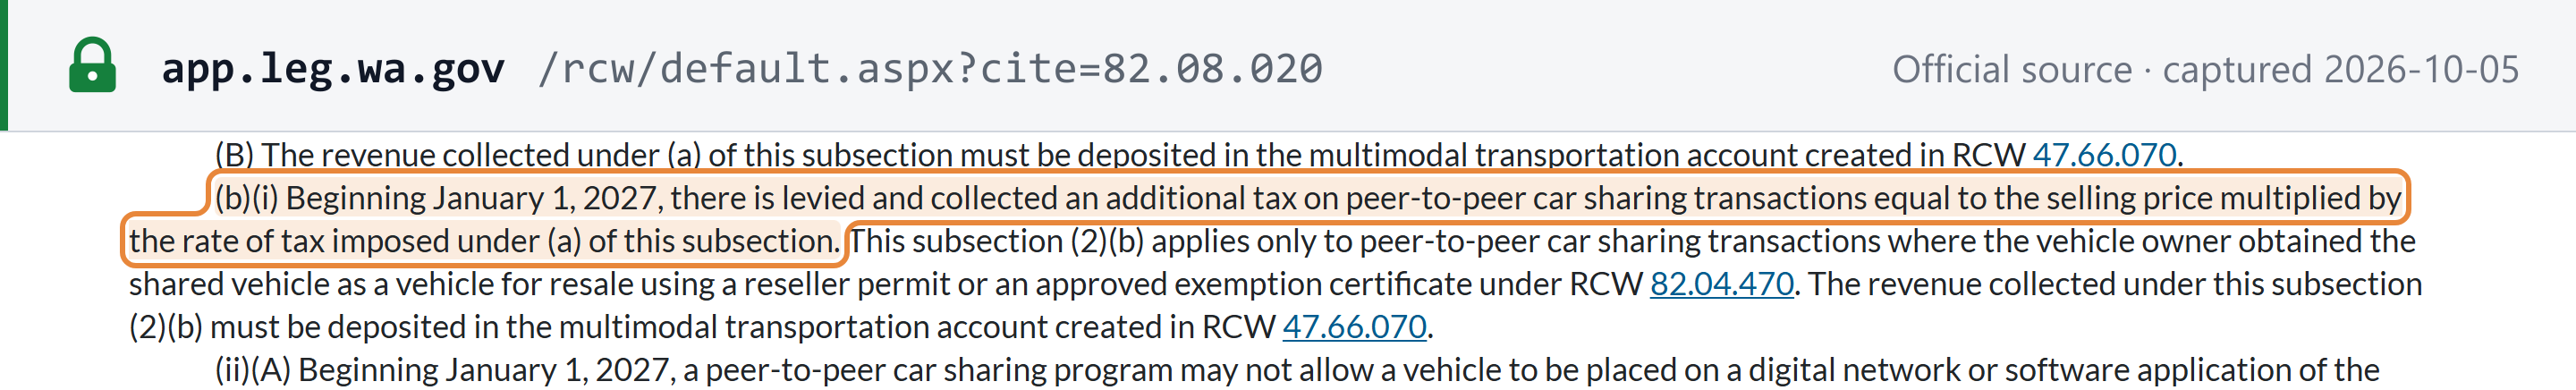 Source snapshot of the official page. Open full size ↗