India's GST Council recommends inverted-duty refunds of ITC on input services from 1 November 2026 and 60-month refunds on capital goods - not yet notified
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in India as they stand today, see the India guide →
- Jurisdiction
- India
- Tax
- GST
- Change type
- Compliance
- Status
- Proposed
- Impact
- Plan ahead
- Announced
- 8 October 2026
- Effective
- 1 November 2026
- Authority
- GST Council / CBIC (Ministry of Finance, Department of Revenue)
- Systems
- ERP, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
GST-registered taxpayers claiming refunds of accumulated input tax credit under the inverted duty structure, and exporters or zero-rated suppliers claiming refunds of ITC on capital goods.
Await CGST amendment/notification; review inverted-duty refund and capital-goods ITC tracking.
ERPTax engineReporting
The 57th GST Council meeting recommended that refund of accumulated ITC on input services in inverted-duty-structure refund claims be available for ITC availed on input services on or after 1 November 2026, and that refund of ITC on capital goods (zero-rated supplies and inverted duty) be spread over 60 months for ITC availed on capital goods on or after 1 April 2027. Recommendation only; requires CGST Act/Rules amendment.
What changed in detail
This is a Council recommendation, not a notified change. The 57th meeting of the GST Council, held on 8 October 2026, recommended amending clause (ii) of the proviso to section 54(3) of the CGST Act, 2017 and the CGST Rules, 2017 on refunds of accumulated input tax credit (ITC).
- Input services (inverted duty structure). Refund of accumulated ITC on input services in inverted-duty refund claims would be available for ITC availed on input services on or after 1 November 2026.
- Capital goods (zero-rated supplies and inverted duty). Refund of ITC on capital goods would be spread over 60 months, and would be available for ITC availed on capital goods on or after 1 April 2027.
The Council’s release says the change is meant to ease working-capital constraints and remove blockage of ITC on input services and capital goods in these cases. It requires an amendment to the CGST Act and Rules before it can take effect.
What it means
Until the amendment is notified, refund claims continue under the current law and the 1 November 2026 and 1 April 2027 dates are not binding. Those dates are tied to when ITC is availed, so they matter for ITC tracking rather than for the date a refund is filed.
The 60-month spread for capital goods means refunds on those assets will arrive in instalments rather than at once. Businesses with inverted-duty or zero-rated claims should check that their ERP can tag ITC by input type and by availment date so they are ready if the rules are notified as recommended.
Proof
shall be available in respect of ITC availed on input services on or after 1st November, 2026.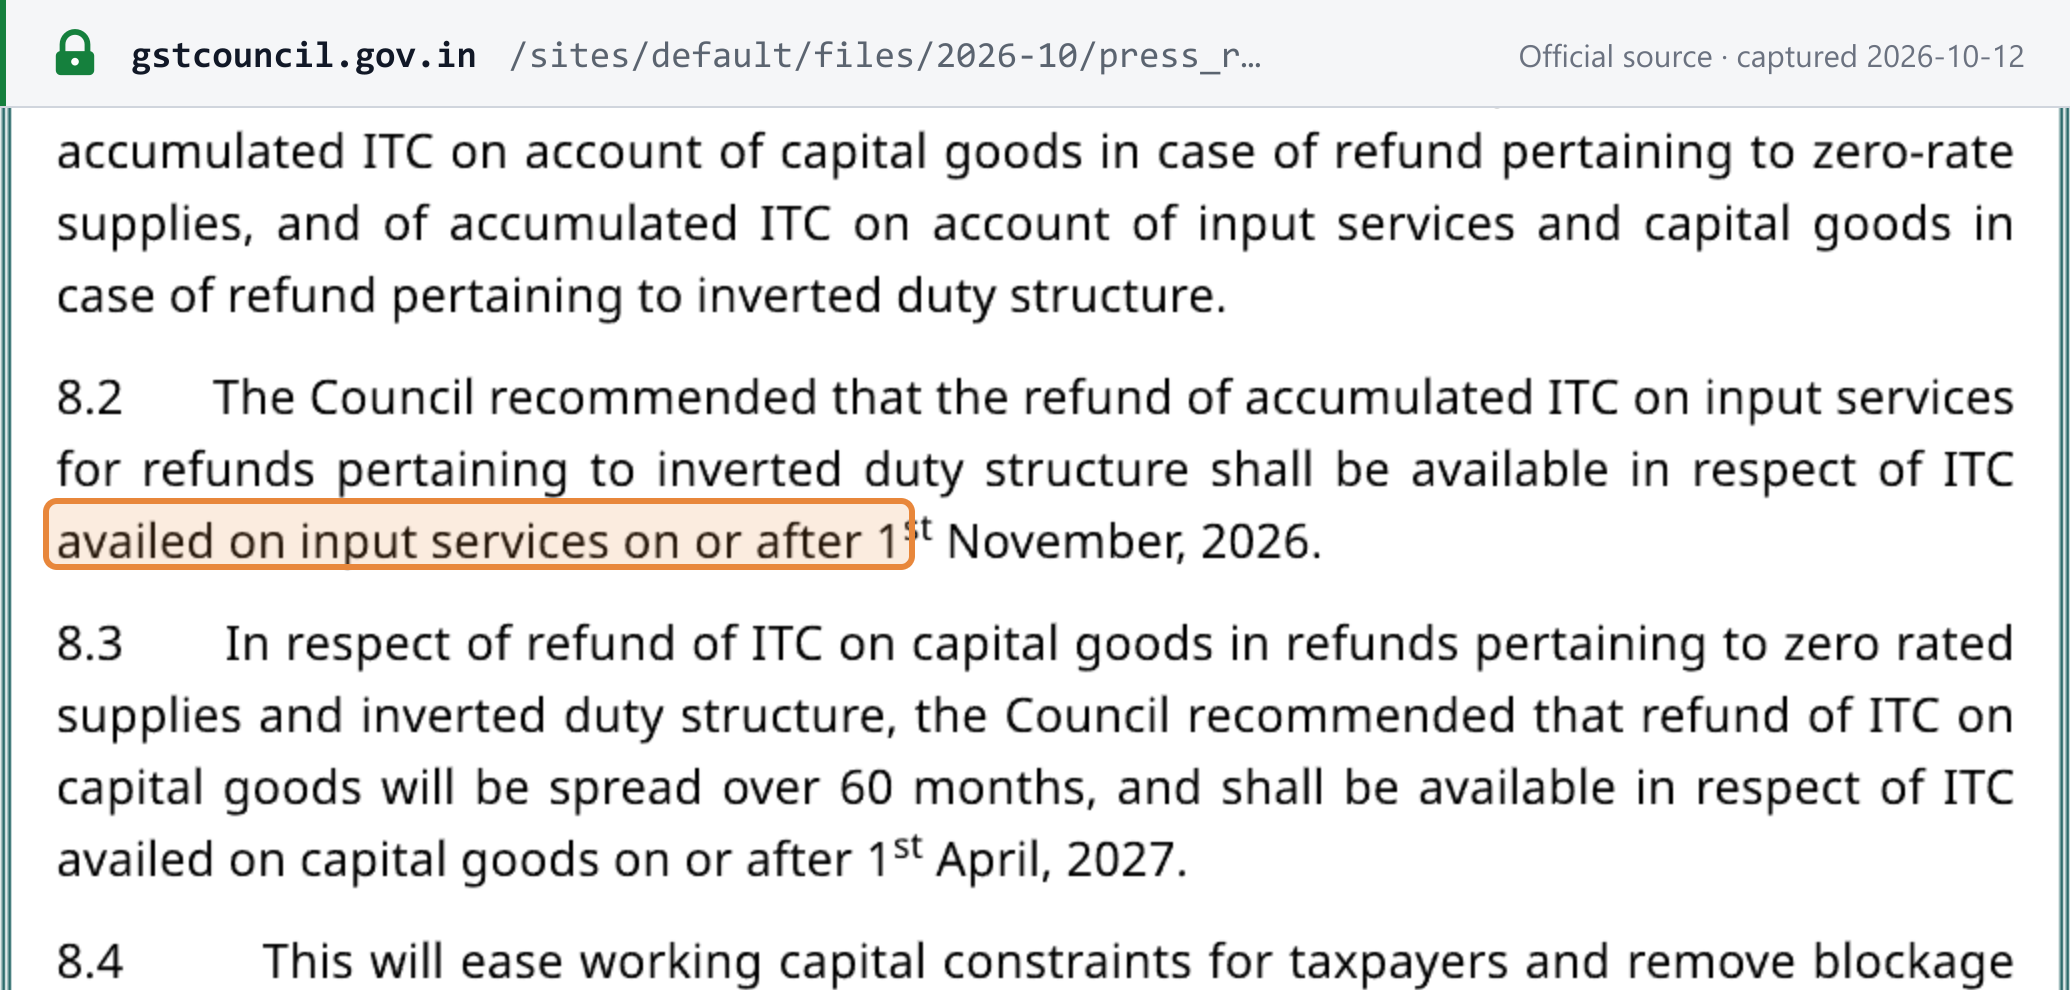 Source snapshot of the official page. Open full size ↗