Norway gives businesses until 1 January 2030 to receive B2B e-invoices; issuing still starts 1 January 2027
This page records one dated change. For the rules in Norway as they stand today, see the Norway guide →
- Jurisdiction
- Norway
- Tax
- VAT
- Change type
- E-invoicing
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 28 September 2026
- Effective
- 1 January 2030
- Instrument
- NO-FOR-2026-09-25-1913
- Authority
- Finansdepartementet / regjeringen.no (Norwegian Ministry of Finance)
- Systems
- ERP, Invoicing
- Verified
- Fetched from official source · high confidence
Norwegian bookkeeping-liable businesses that buy from or sell to other bookkeeping-liable parties.
Plan to issue structured e-invoices to ELMA/Peppol-registered Norwegian bookkeeping-liable buyers from 1 January 2027, and to be able to receive them by 1 January 2030.
ERPInvoicing
Norway's Ministry of Finance (Finansdepartementet) adopted FOR-2026-09-25-1913, a transitional regulation under Part VII no. 2 of lov 19. juni 2026 nr. 39, on 25 September 2026, in force immediately. It provides that the Bookkeeping Act section 10 second paragraph second sentence duty to receive documentation of purchases from other bookkeeping-liable parties in electronic invoice format must be met by 1 January 2030. The duty to issue sales documentation to other bookkeeping-liable parties in electronic invoice format still applies from 1 January 2027 under FOR-2026-06-19-1154. Skatteetaten states that until 1 January 2030 the issuing duty therefore applies in practice only where the bookkeeping-liable buyer can receive e-invoices (registered in ELMA/Peppol). This supersedes no-b2b-einvoice-bookkeeping-act-2026-correction, which stated that both issuing and receiving apply from 1 January 2027.
What changed in detail
Norway’s Ministry of Finance (Finansdepartementet) adopted FOR-2026-09-25-1913 on 25 September 2026. It is a transitional regulation made under Part VII no. 2 of lov 19. juni 2026 nr. 39, the Act that introduced mandatory B2B e-invoicing into the Bookkeeping Act. It was announced in Norsk Lovtidend on 28 September 2026 and took effect immediately.
The regulation has one operative rule. The duty in Bookkeeping Act section 10 second paragraph second sentence, to receive documentation of purchases from other bookkeeping-liable parties in electronic invoice format, must be met by 1 January 2030.
The duty to issue sales documentation to other bookkeeping-liable parties in electronic invoice format is unchanged. Royal resolution FOR-2026-06-19-1154 brings it into force on 1 January 2027.
Skatteetaten’s statement of 30 September 2026 sets out the consequence. Until 1 January 2030, the issuing duty applies in practice only where the bookkeeping-liable buyer can receive e-invoices, meaning it is registered in ELMA/Peppol.
This replaces the position recorded in no-b2b-einvoice-bookkeeping-act-2026-correction, which said both issuing and receiving apply from 1 January 2027.
What it means
On Skatteetaten’s reading, from January 2027 a bookkeeping-liable seller cannot send a PDF to a bookkeeping-liable customer that can receive e-invoices, which in practice means one registered in ELMA. Check each buyer’s ELMA registration before choosing the channel. Until 31 December 2029 the parties may agree on another structured format, such as EDIFACT, instead of EHF / Peppol BIS.
The receive duty itself moves to 2030, but a buyer that is already registered in ELMA should expect its non-exempt suppliers to start sending structured invoices from 2027.
The formats, the narrow NOK 50,000 exemption and the 2028 organisation-number rule come from a separate regulation. See FOR-2026-09-29-1933.
Proof
Plikten etter bokføringsloven § 10 annet ledd annet punktum jf. endringsloven del I, om at dokumentasjon for kjøp av varer og tjenester fra andre bokføringspliktige skal mottas i elektronisk fakturaformat, må oppfylles innen 1. januar 2030.The duty under section 10 second paragraph second sentence of the Bookkeeping Act, cf. Part I of the amending Act, that documentation of purchases of goods and services from other bookkeeping-liable parties shall be received in electronic invoice format, must be met by 1 January 2030.
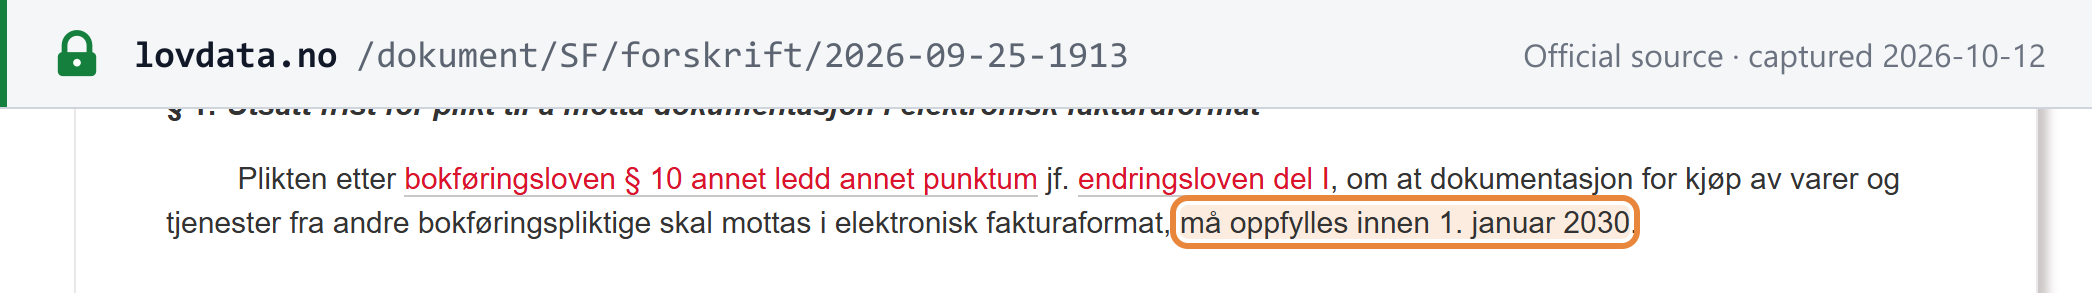 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · FOR-2026-09-25-1913 — Forskrift om overgangsregel til lov 19. juni 2026 nr. 39, fastsatt av Finansdepartementet 25. september 2026, kunngjort 28.09.2026 · lovdata.no
Frem til 1. januar 2030 vil plikten til å utstede elektronisk faktura derfor i praksis bare gjelde når den bokføringspliktige mottakeren har funksjonalitet for å motta slike fakturaer (registrert i ELMA/Peppol).Until 1 January 2030 the duty to issue electronic invoices will therefore in practice apply only where the bookkeeping-liable recipient has the functionality to receive such invoices (registered in ELMA/Peppol).
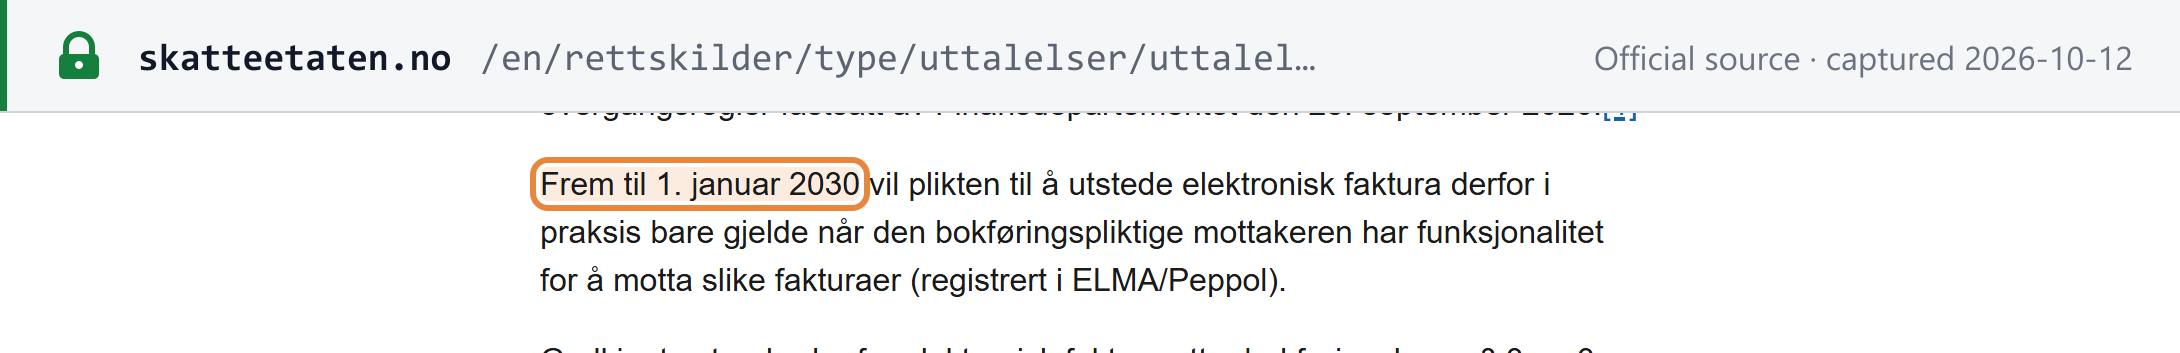 Source snapshot of the official page. Open full size ↗
Sources
- Forskrift om overgangsregel til lov 19. juni 2026 nr. 39 om endringer i bokføringsloven og enkelte andre lover på finansmarkedsområdet (pliktig digital bokføring og e-fakturering mv.) — FOR-2026-09-25-1913
- Forskrifter til lovendringer om digital bokføring og e-fakturering (uttalelse, 30. september 2026)