Norway names EHF and Peppol BIS 3.0 as its B2B e-invoice formats from 1 January 2027, with a narrow NOK 50,000 exemption
This page records one dated change. For the rules in Norway as they stand today, see the Norway guide →
- Jurisdiction
- Norway
- Tax
- VAT
- Change type
- E-invoicing
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 29 September 2026
- Effective
- 1 January 2027
- Instrument
- NO-FOR-2026-09-29-1933
- Authority
- Skatteetaten (Norwegian Tax Administration)
- Systems
- ERP, Invoicing
- Verified
- Fetched from official source · high confidence
Norwegian bookkeeping-liable businesses invoicing other bookkeeping-liable parties. The NOK 50,000 exemption covers only persons with no accounting duty and no VAT-return duty, and not those named in skatteforvaltningsforskriften § 8-2-1(2).
Configure Norwegian B2B invoicing to EHF / Peppol BIS Billing 3.0 (or an agreed structured format until end-2029) by 1 January 2027, and add the buyer organisation number (plus MVA) to invoices to bookkeeping-liable buyers by 1 January 2028.
ERPInvoicing
Skattedirektoratet adopted FOR-2026-09-29-1933 amending the Norwegian bookkeeping regulation (bokføringsforskriften, FOR-2004-12-01-1558) on 29 September 2026, with provisions in force on 29 September 2026, 1 January 2027, 1 January 2028 and 1 January 2030. New section 5-2-9 second paragraph, in force 1 January 2027, names EHF Fakturering, Peppol BIS Billing, EHF Selvfakturering and Peppol BIS Self-Billing, all in version 3.0 or later, as the approved electronic invoice standards; from 1 January 2027 to 31 December 2029 the parties may agree to use another electronic invoice format. New section 1-2 covers bookkeeping-liable persons who file an income tax return and whose turnover does not exceed NOK 50,000 in a calendar year: from 1 January 2027 they are exempt from Bookkeeping Act sections 5 to 9 and 13b, and the duty to issue documentation for sales of goods in electronic invoice format applies to them only where it is issued in an invoicing system with that functionality; from 1 January 2030 they are also exempt from the duty to receive e-invoices. The exemption ends when turnover exceeds NOK 50,000 and does not apply to persons with an accounting duty under the Accounting Act section 1-2, persons obliged to file a VAT return, or other bookkeeping-liable persons named in the Tax Administration Regulation section 8-2-1 second paragraph. Non-trading bankruptcy estates obliged to file VAT returns are exempt from Bookkeeping Act section 5 first paragraph nos. 2 to 7 from 1 January 2027, and from section 7 fourth paragraph and the duty to receive e-invoices from 1 January 2030. From 1 January 2028 sales documents to bookkeeping-liable buyers must state the buyer's organisation number, followed by MVA where the buyer is VAT-registered, and must be sent to the buyer. This supersedes no-b2b-einvoice-bookkeeping-act-2026-correction, which stated that no format, exemption or other implementing regulation had been published.
What changed in detail
Skattedirektoratet adopted FOR-2026-09-29-1933 on 29 September 2026. It amends the bookkeeping regulation (bokføringsforskriften, FOR-2004-12-01-1558), and its provisions take effect in stages on 29 September 2026, 1 January 2027, 1 January 2028 and 1 January 2030.
- Formats (section 5-2-9 second paragraph, from 1 January 2027). The approved e-invoice standards are EHF Fakturering, Peppol BIS Billing, EHF Selvfakturering and Peppol BIS Self-Billing, all in version 3.0 or later. From 1 January 2027 to 31 December 2029, the parties may instead agree to use another electronic invoice format.
- Low-turnover exemption (new section 1-2). It covers bookkeeping-liable persons who file an income tax return and whose turnover does not exceed NOK 50,000 in a calendar year. From 1 January 2027 they are exempt from Bookkeeping Act sections 5 to 9 and 13b, and for sales of goods the duty to issue an e-invoice applies only where the invoice is produced in an invoicing system with that functionality. From 1 January 2030 they are also exempt from the duty to receive e-invoices. The exemption ends from the moment turnover exceeds NOK 50,000. It does not apply to anyone with an accounting duty under the Accounting Act section 1-2, anyone who must file a VAT return, or the other bookkeeping-liable persons named in the Tax Administration Regulation section 8-2-1 second paragraph.
- Bankruptcy estates (section 1-1). Non-trading bankruptcy estates that must file VAT returns are exempt from Bookkeeping Act section 5 first paragraph nos. 2 to 7 from 1 January 2027. From 1 January 2030 they are also exempt from the electronic-accounting-system duty and the duty to receive e-invoices.
- Invoice content (section 5-1-2 and section 5-2-1, from 1 January 2028). A sales document to a bookkeeping-liable buyer must state the buyer’s organisation number. Where the buyer is VAT-registered, the number is followed by “MVA”. The document must also be sent to the buyer.
This replaces the position recorded in no-b2b-einvoice-bookkeeping-act-2026-correction, which said no format or exemption had been set.
What it means
For most businesses the format question is settled: EHF / Peppol BIS Billing 3.0. Anyone already exchanging EDIFACT or another structured format with a trading partner can keep doing so until the end of 2029, but only by agreement with that partner. Skatteetaten states that a PDF invoice does not qualify and cannot be used where the buyer can receive e-invoices.
Do not read the NOK 50,000 figure as a small-business threshold. Anyone with an accounting duty, which takes in limited companies, and anyone obliged to file a VAT return is outside it, whatever the turnover.
The 2028 organisation-number rule is the one most likely to need a data fix. Customer master data that identifies Norwegian business buyers by name and address only will not be enough.
Proof
Godkjente standarder for elektronisk faktura etter bokføringsloven § 3 nr. 3, er EHF Fakturering, Peppol BIS Billing, EHF Selvfakturering og Peppol BIS Self-Billing, alle i versjon 3.0 eller nyere.Approved standards for electronic invoices under section 3 no. 3 of the Bookkeeping Act are EHF Fakturering, Peppol BIS Billing, EHF Selvfakturering and Peppol BIS Self-Billing, all in version 3.0 or later.
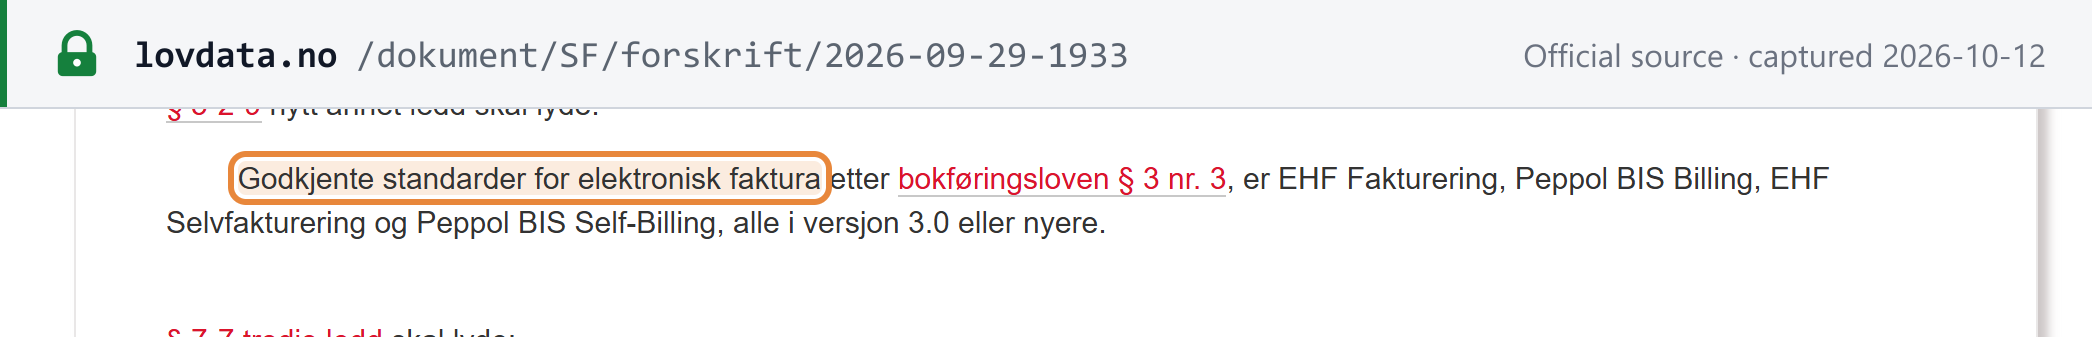 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · FOR-2026-09-29-1933 — Forskrift om endring i bokføringsforskriften, fastsatt av Skattedirektoratet 29. september 2026; endrer FOR-2004-12-01-1558 · lovdata.no