Romania TIN number guide
Personal Identification Number (CNP)
Natural persons in Romania are assigned a Personal Identification Number (CNP) by the Ministry of Internal Affairs, which also functions as a Tax Identification Number (TIN) utilized by the tax administration. It is also known as Cod Numeric Personal.
CNP Format CNP consists of 1 block of 13 digits
Structure: TIN Format [C1, C2, C3, C4, C5, C6, C7, C8, C9, C10, C11, C12, C13] Where C1 to C13 represent characters. Structure: Range C1, C2, C3, C4, C5, C6, C7, C8, C9, C10, C11, C12, C13 All are numeric. Structure: Rules for C1: Within the range 1 to 8:
- 1 is assigned to males born between 1900 and 1999.
- 2 is assigned to females born between 1900 and 1999.
- 3 is for males born between 1800 and 1899.
- 4 is for females born between 1800 and 1899.
- 5 is for males born between 2000 and 2099.
- 6 is for females born between 2000 and 2099.
- 7 is for foreign males with temporary residence in Romania.
- 8 is for foreign females with temporary residence in Romania.
A leading digit of 9 is not a CNP rule: it identifies the separate NIF that ANAF issues to non-resident individuals (see below). [OECD]
C2, C3: Represent the last two digits of the year (00 to 99). C4, C5: Indicate the month (1 to 12). C6, C7: Represent the day of the month (1 to 31, depending on the month and year). C8, C9: County or district code (01 to 47, 51 and 52, 70, or 80 to 83). [OECD] Structure: Sample TIN: 8001011234567
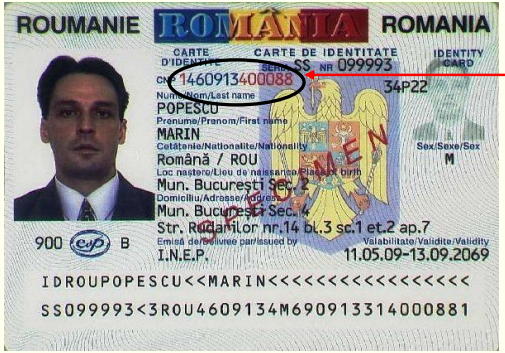 |
| CNP on ID card |
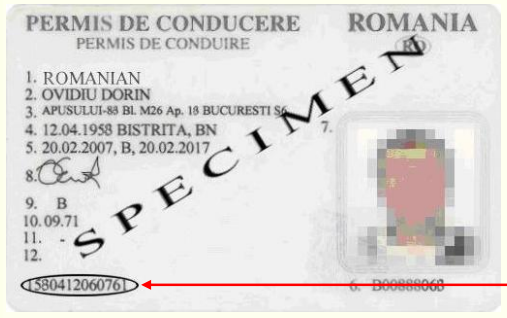 |
| Driving license |
Codul de înregistrare fiscală (CIF)
For legal entities and other non-individual taxpayers, the Romanian tax identification number is the Codul de înregistrare fiscală (CIF), issued by the Tax Administration for tax purposes. Non-resident individuals receive a separate NIF, described below.
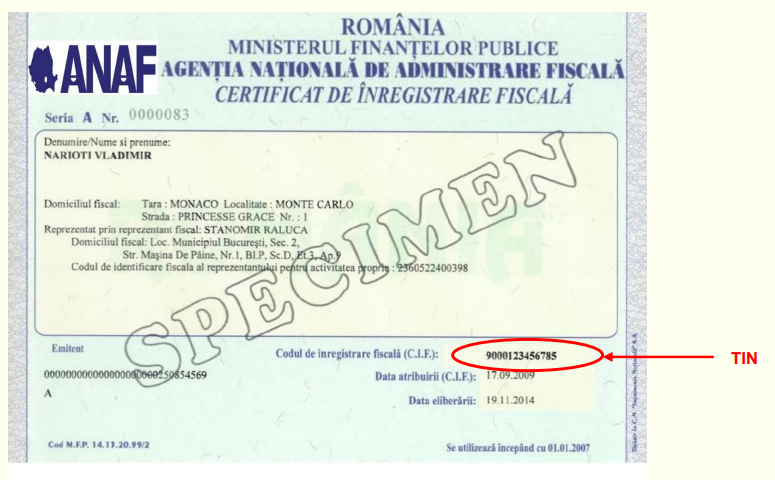 |
| CIF on Certificate for Tax Registration |
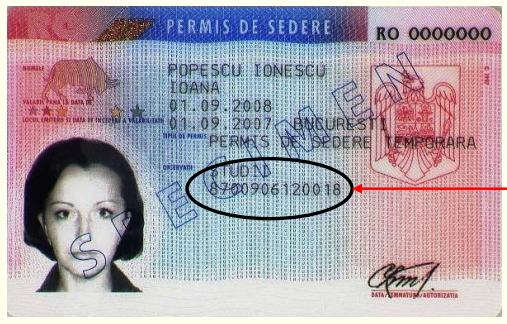 |
| Residence Permit |
Official database CIF search
Numărul de identificare fiscală (NIF) for non-resident individuals
The Tax Administration (ANAF) issues the NIF to non-resident individuals who need a Romanian tax identifier. It is used only for tax purposes, and its first digit is always 9. [OECD]
TIN Format Structure: TIN2 Format [C1, C2, C3, C4, C5, C6, C7, C8, C9, C10, C11, C12, C13] Where C1 to C13 represent characters. Structure: Range C1, C2, C3, C4, C5, C6, C7, C8, C9, C10, C11, C12, C13 All are numeric. Structure: Rules for TIN2: C1: 9 C2: 0 C3: 0 C4: 0 C5 to C13: Each can take a value between 0 to 9. Structure: Sample TIN2: 9000123456789.
Codul unic de identificare (CUI)
Until 2007, the term CUI (Unique Registration Code) was employed, after which the term CIF (Fiscal Registration Code) became prevalent. The distinction lies in the purpose for which this code is solicited. The legal entity providing the tax certificate determines whether the code is designated as CUI or CIF. The Romanian Codul Unic de Înregistrare (CUI) is a single block of digits, optionally preceded by the prefix RO when the company is registered for VAT. Its length varies; no fixed length is published, and Romania's OECD TIN sheet gives none. It is allocated to companies mandated to register with the Romanian Trade Register.
Official database CUI Search
To check a Romanian VAT number, use Lookuptax's Romania VAT number validator. For VAT registration, rates, invoicing and RO e-Factura, see the Romania VAT guide.
Frequently Asked Questions
As a foreigner without Romanian residency, do I get a CNP or a NIF, and what is the difference?
CNP (Cod Numeric Personal) is issued by the Ministry of Internal Affairs only to individuals with the right of residence in Romania — EU/EEA citizens who have registered their residency and non-EU nationals holding a residence permit. Foreigners who have no residency right but need to carry out economic activities in Romania (buying property, earning rental income, conducting business) must instead obtain a NIF (Numărul de Identificare Fiscală) issued by ANAF. The application requires Form 030 submitted in person at an ANAF office or through a notarised proxy. Once you obtain a residency right and a CNP, the NIF becomes redundant — the CNP serves as your tax identifier from that point. [1] [2]
Why does my software validator reject the CUI of a Romanian company that claims to be legitimate?
Approximately 30% of Romanian companies are not registered for VAT and therefore do not have an "RO"-prefixed CIF/VAT number — they only hold a bare CUI (Cod Unic de Înregistrare). Many third-party validation libraries and ERP integrations silently fail on non-VAT CUIs because they only verify against the VIES or the ANAF TVA register, which lists only VAT-registered entities. A valid non-VAT company CUI will return no result from those sources even though the company is legally active. To verify a non-VAT company, use the Ministry of Finance's CUI lookup at mfinante.gov.ro, which covers all Trade Register entries regardless of VAT status. [3] [4]
What penalty applies if a Romanian B2B invoice is not submitted through RO e-Factura from July 2024 onwards?
Under Law 296/2023 as amended by Emergency Ordinance 115/2023, an issuer established in Romania that does not transmit a B2B invoice through RO e-Factura, and a recipient established in Romania that receives and records a B2B invoice outside the system, are each fined an amount equal to 15% of the total invoice value (OUG 120/2021 art. 13^2(1)(a)–(b) and (2)). The fine applies per non-compliant invoice, with no cap. The 15% fines are drafted only for issuers and recipients established in Romania: non-resident entities registered for VAT in Romania are not in the mandatory B2B clearance scope since 1 July 2024, although they may opt into RO e-Factura through the optional register. See the Romania VAT guide for the full e-invoicing timeline. [ANAF] [ANAF]
Does a non-resident company with only a Romanian VAT registration also have to file SAF-T (Form D406)?
Yes. Starting January 1, 2025, non-resident taxpayers holding only a Romanian VAT registration number — with no permanent establishment in Romania — must submit a simplified SAF-T D406 file covering their Romanian sales and purchase invoices. ANAF Order 407/2025 (Official Gazette no. 310/8 April 2025) did not newly extend D406 to this group — the 2021 annex already listed non-resident VAT-registered companies; OPANAF 407/2025 pt 1.1 lit. e made explicit that non-residents registered only for VAT file D406 from the small-taxpayer reference date (1 January 2025). [ANAF] The simplified file excludes general ledger and fixed-asset sections but must include all invoices reported under the Romanian VAT registration. Submission frequency mirrors VAT return frequency (monthly or quarterly). Late filing is fined a flat RON 1,000–5,000, whatever the taxpayer category, and incorrect or incomplete filing RON 500–1,500 (Fiscal Procedure Code art. 337^1). [ANAF] [7] [8]
When does a Romanian micro-enterprise lose its preferential tax rate, and what triggers mandatory exit?
Since 1 January 2026 a single 1% rate applies to micro-enterprise turnover (impozit pe veniturile microîntreprinderilor): "Cota de impozit pe veniturile microîntreprinderilor este de 1%" (Fiscal Code art. 51(1), as amended by OUG 89/2025). The 2025 split — 1% on revenues up to €60,000 and 3% above — no longer applies. [ANAF] The ceiling itself is shrinking: €500,000 through 2024, dropping to €250,000 from 1 January 2025 and then to €100,000 from 1 January 2026. Exit is also triggered mid-year if the company exceeds the applicable ceiling — it switches to standard 16% corporate income tax from the quarter of the breach. Additionally, companies whose shareholders hold more than 25% in more than three other Romanian micro-enterprises cannot use the regime, and companies deriving over 20% of revenue from management or consultancy are excluded entirely. [9] [10]
How Lookuptax can help you in VAT validation?
Lookuptax VAT validation revolutionizes VAT number validation with its robust platform, empowering businesses to seamlessly verify VAT numbers across over 100 countries. Our cutting-edge technology ensures accurate and efficient validation, reducing errors and enhancing compliance.