E-Invoicing in Taiwan — Uniform Invoices, Upload Time Limits and MIG 4.0
| Country | Taiwan |
| Authority | Ministry of Finance (財政部); the MIG is published by its Fiscal Information Agency (財政資訊中心) |
| Platform | MOF E-Invoice Platform (財政部電子發票整合服務平台) |
| Legislation | Value-added and Non-value-added Business Tax Act, Arts 32, 32-1, 48-2; Uniform Invoice Regulations (統一發票使用辦法); E-Invoice Implementation Directions (電子發票實施作業要點) |
Overview
Taiwan's sales document is the uniform invoice (統一發票). A registered business must issue one to the buyer at the time set by the statutory time-limit table attached to the Value-added and Non-value-added Business Tax Act (Art 32). The Act lets the invoice be printed by the government, self-printed with approval, or "issued, transmitted or obtained via the internet or by other electronic means" (Art 32 para 4). [1]
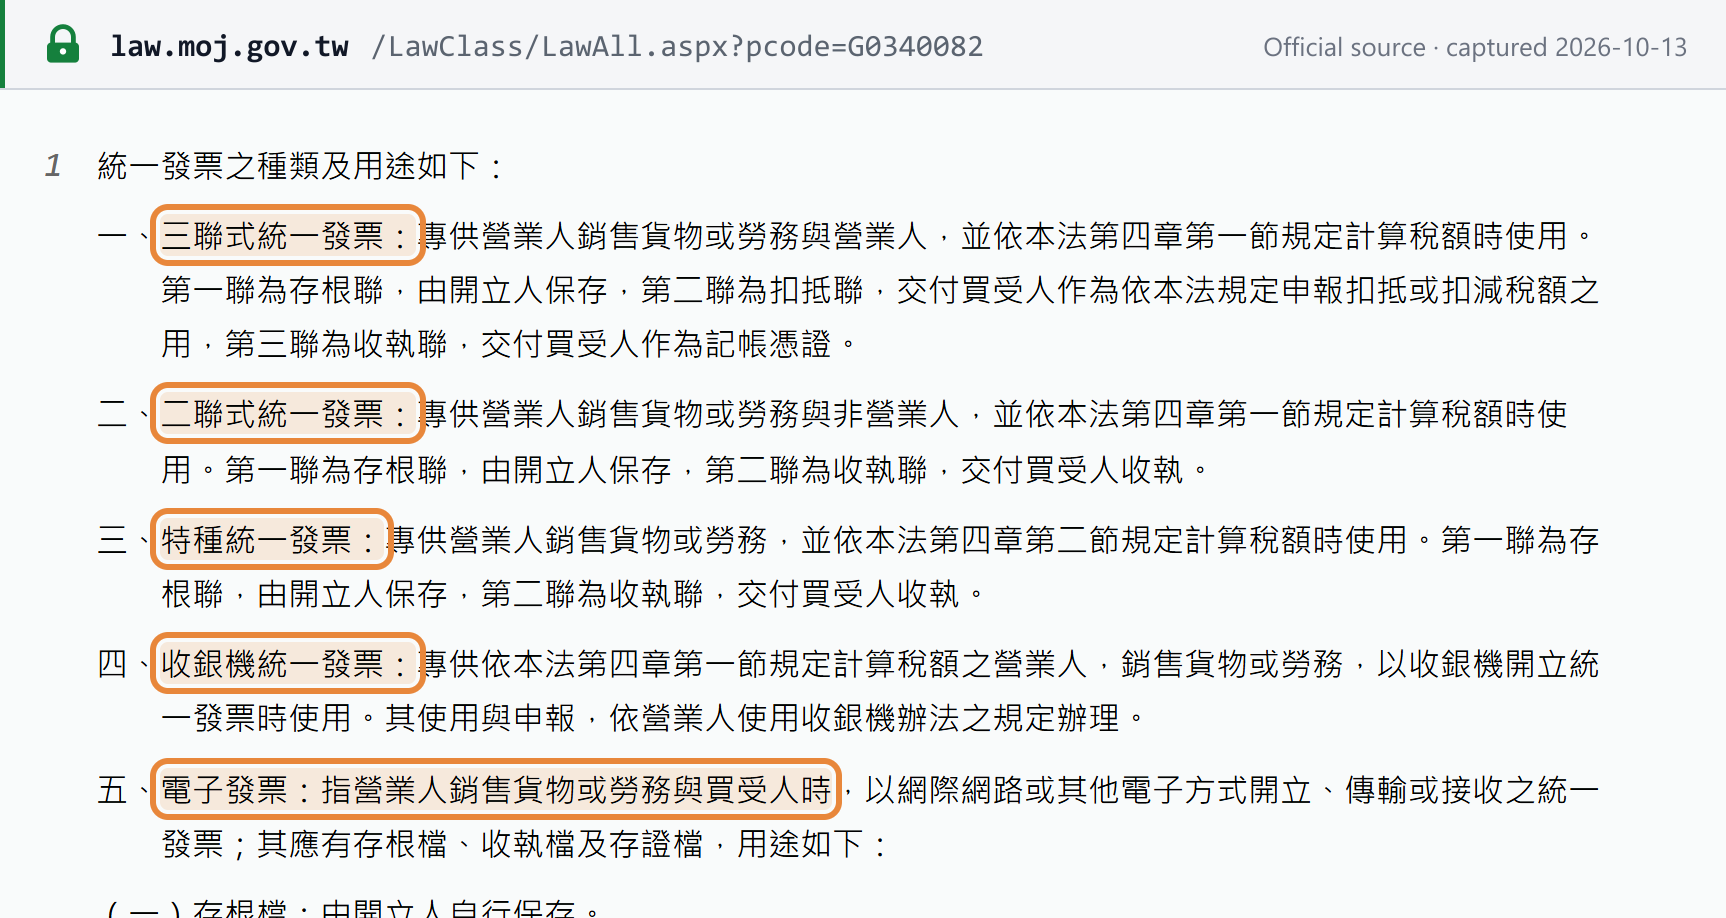
The e-invoice (電子發票) is one of five uniform-invoice types in the Uniform Invoice Regulations (Art 7):
- Triplicate (三聯式) — sales to businesses under the general (VAT) method.
- Duplicate (二聯式) — sales to non-business buyers under the general method.
- Special (特種) — sellers taxed on the non-VAT (gross receipts) track.
- Cash-register (收銀機) — general-method sellers issuing by cash register.
- Electronic invoice (電子發票) — issued, transmitted or received electronically, with a stub file, a receipt file and an evidence (存證) file.
For domestic sellers the law permits e-invoices; no general B2B, B2G or B2C e-invoicing mandate appears in the Business Tax Act, the Uniform Invoice Regulations or the current E-Invoice Implementation Directions. Registered foreign e-service suppliers selling to individuals in Taiwan must issue cloud invoices (see below).
| Taiwan | |
|---|---|
| Model | Post-issuance evidence filing (存證): the seller issues the e-invoice, then files it and the required data on the MOF E-Invoice Platform |
| Filing time limit | 7 days (business buyer) / 2 days (non-business buyer), from the day after issue |
| Format | E-Invoice Message Implementation Guideline (MIG) 4.0, XML; versions 3.2.1 and 3.1.2 retired on 1 January 2026 |
| Connection | The platform itself, the platform's Turnkey software, or a value-added service centre (加值服務中心) |
| Domestic sellers | E-invoice permitted; one of five uniform-invoice types |
| Foreign e-service suppliers (B2C) | Cloud invoices mandatory since 1 January 2019 |
| Authority | Ministry of Finance (MIG published by its Fiscal Information Agency) |
Key terms
- E-Invoice Platform (財政部電子發票整合服務平台). The Ministry of Finance platform at einvoice.nat.gov.tw where e-invoice evidence files are filed, and where buyers can receive invoices.
- MIG (電子發票資料交換標準訊息建置指引). The Message Implementation Guideline — the XML message specification for e-invoice data.
- Carrier (載具). An identifier that a buyer gives the seller so a cloud invoice is attached to them without printing — the MOF common carrier (a mobile barcode), a citizen digital certificate, or a phone, membership or payment-card number approved as a carrier (Art 32-1 para 2).
- Cloud invoice (雲端發票). An e-invoice issued to a buyer who uses an MOF-approved carrier, or donated by the buyer to a charity by donation code, with no paper proof copy printed (Uniform Invoice Regulations Art 7-1).
- Value-added service centre (加值服務中心). An approved provider that issues and transmits e-invoices on a business's behalf.
E-invoice content
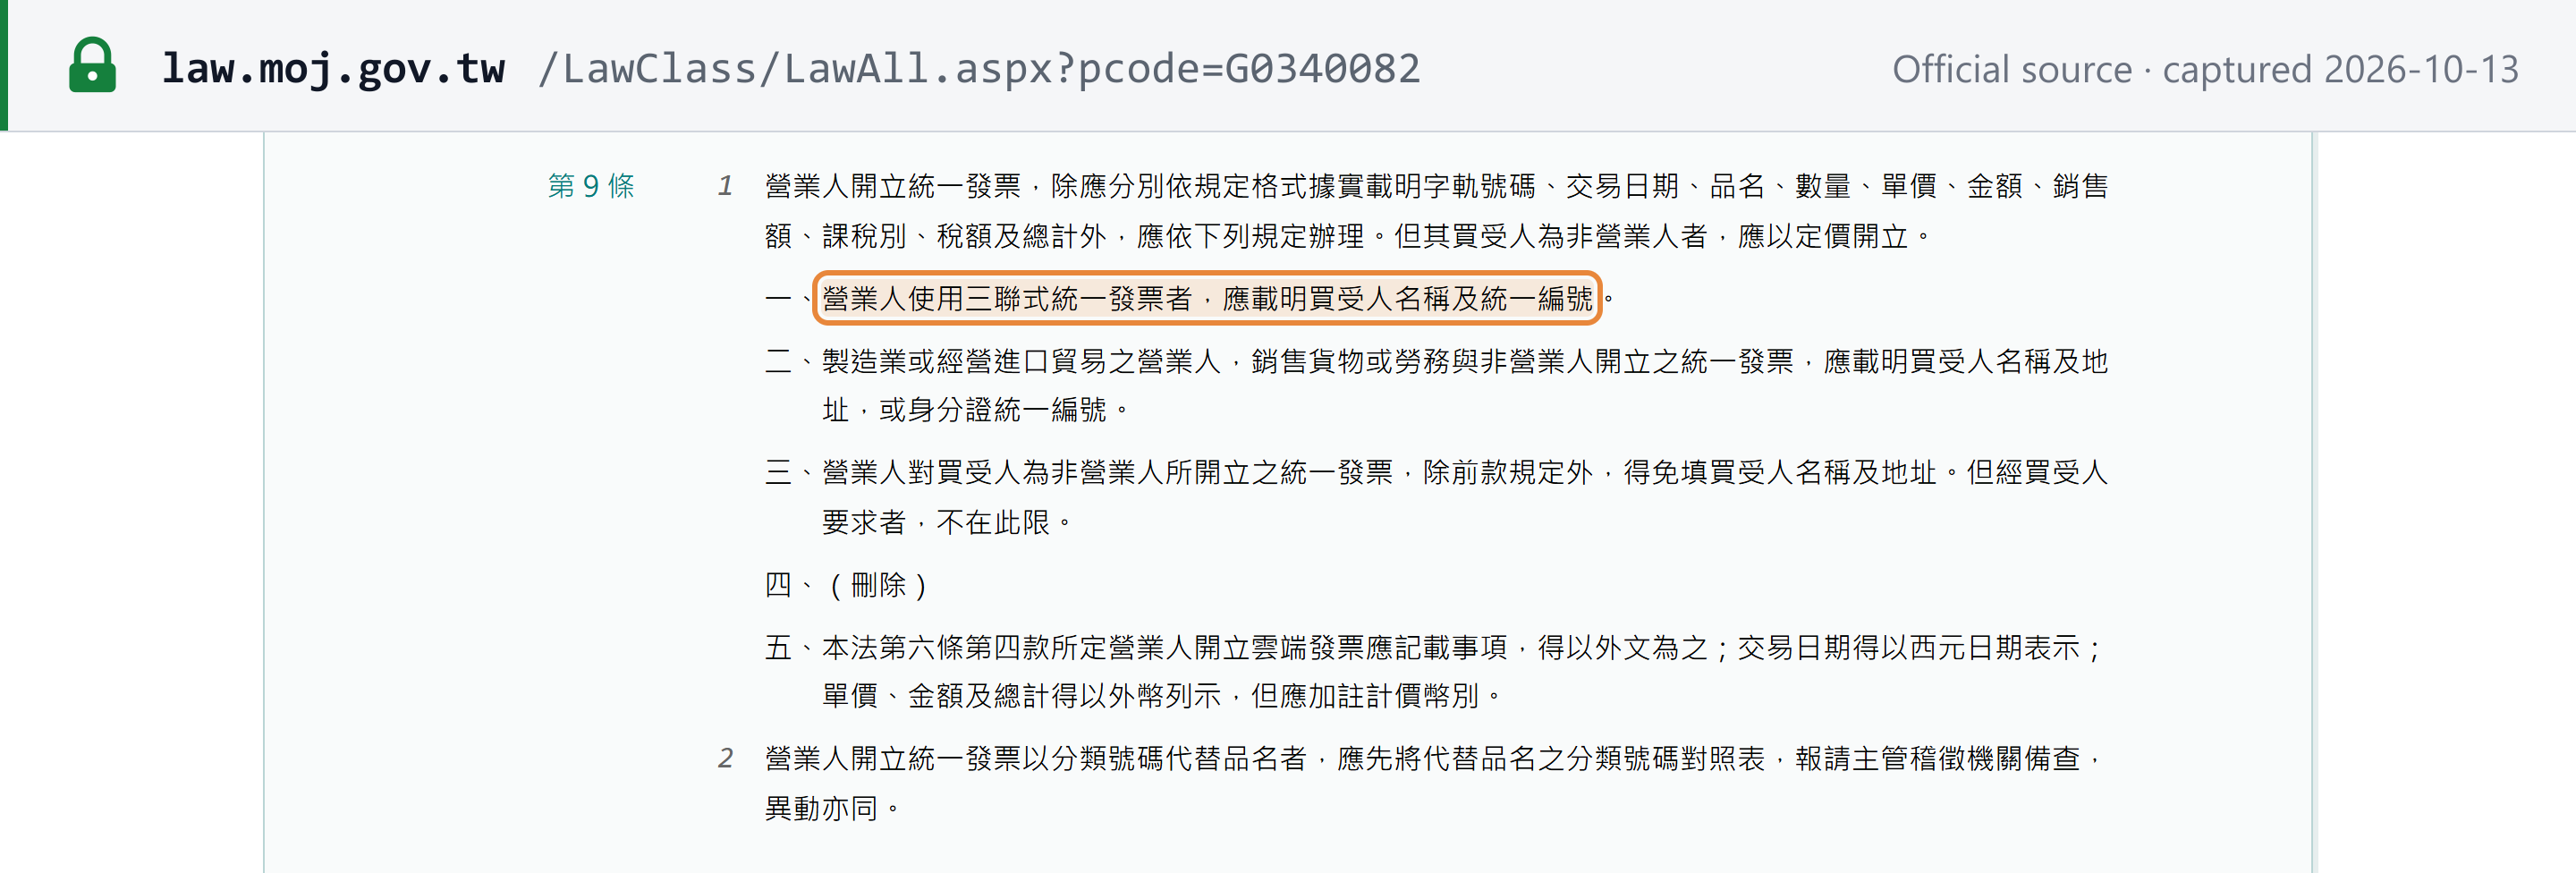
Every uniform invoice, electronic or paper, must state in the prescribed format the track letters and number (字軌號碼), transaction date, item name, quantity, unit price, amount, sales amount, tax category (taxable, zero-rated or exempt), tax amount and total (Uniform Invoice Regulations Art 9). [2]
- Business buyer (triplicate or B2B e-invoice): the buyer's name and BAN (統一編號) must be shown, and the output tax is stated separately from the sales amount (Art 9 subpara 1; Business Tax Act Art 32 para 3).
- Non-business buyer: the invoice is issued at the tax-inclusive list price; the buyer's name and address may be omitted unless the buyer asks — except that manufacturers and importers selling to non-business buyers must state the buyer's name and address, or ID number (Uniform Invoice Regulations Art 9).
- Seller identity: an e-invoice may print the seller's name, BAN and address as text instead of the uniform-invoice seal (Art 8).
- Foreign e-service suppliers: cloud invoices may be in a foreign language, use Western dates and show foreign-currency amounts, if the currency is stated (Art 9 subpara 5).
For the BAN format and check-digit rule, see the Taiwan tax ID guide.
When to issue
The time of issue is set by trade in the Table of the Time Limits for Issuing Documentary Evidence of Sales (營業人開立銷售憑證時限表) attached to the Business Tax Act: [3]
- Sales of goods (trading, manufacturing and similar): at shipment. Payment received before shipment is invoiced when it is received.
- Most services (leasing, warehousing, labour contracting, advertising, transport and similar): when payment is collected.
- Construction: at each instalment due date under the contract.
A business may invoice its sales to other businesses monthly, at month-end, only with the approval of its National Taxation Bureau and if it meets the conditions in Uniform Invoice Regulations Art 15-1. [2]
Filing e-invoices on the platform: time limits
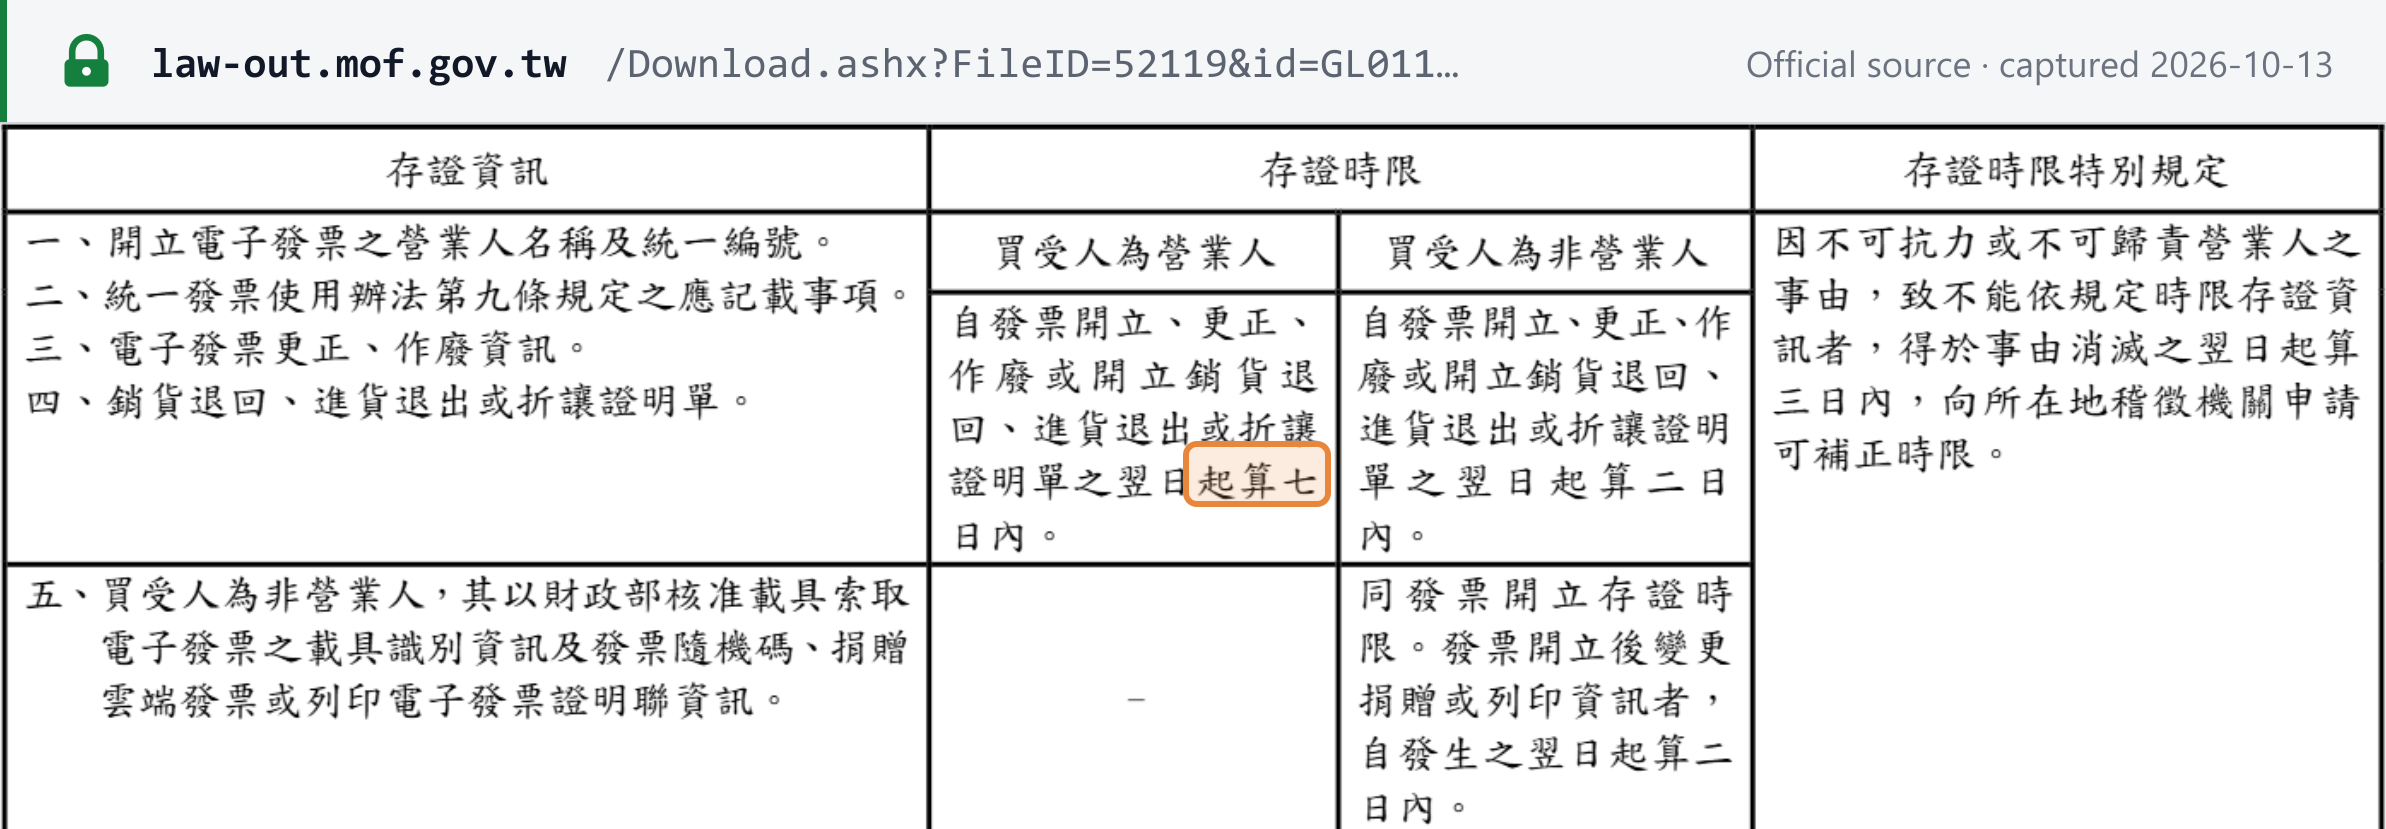
Under MOF Announcement 台財稅字第11304654280號 of 12 December 2024, in force 1 January 2025, a business that issues an e-invoice must file it and the required data on the E-Invoice Platform within these limits, counted from the day after the invoice is issued, corrected or voided (or a sales-return or allowance certificate is issued): [4]
| Buyer | Time limit |
|---|---|
| A business | 7 days |
| Not a business | 2 days |
- Carrier, random-code, donation and print data for non-business buyers follow the same 2-day limit; a later change to the donation or print status is filed within 2 days of the change.
- Unused blank e-invoice numbers are filed within the first 10 days of the next bimonthly period.
- The limit is not extended when its last day falls on a weekend or public holiday. A business prevented by force majeure may apply within 3 days of the obstacle ending for a new time limit.
Format and connection
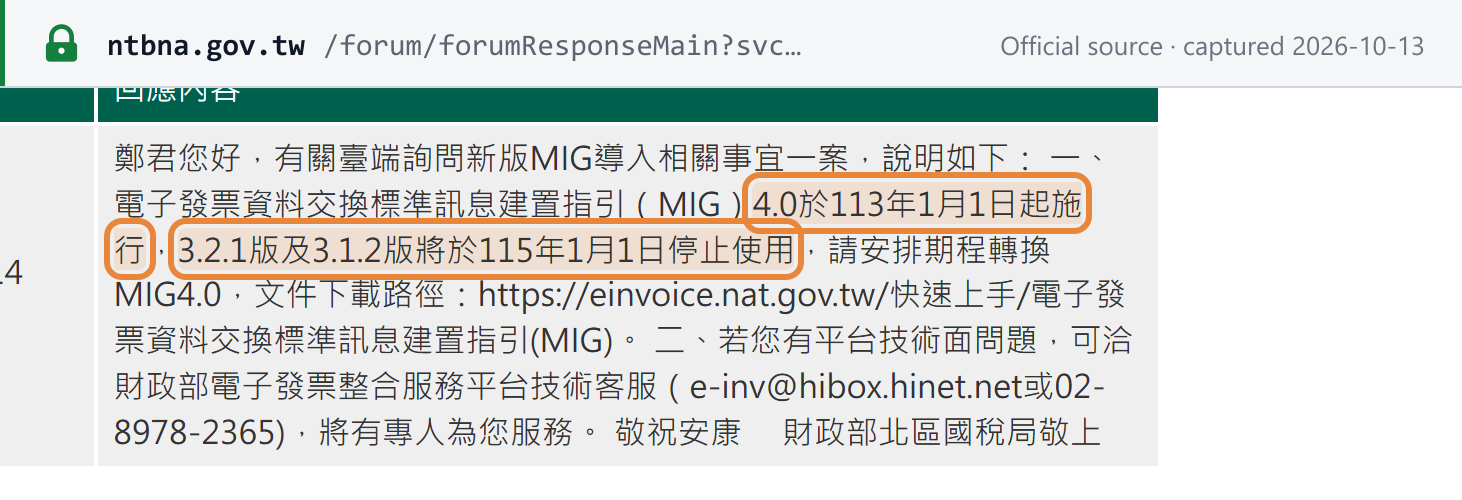
E-invoice data follows the E-Invoice Message Implementation Guideline (MIG), published by the Fiscal Information Agency. MIG 4.0 has applied since 1 January 2024, and MIG versions 3.2.1 and 3.1.2 stopped on 1 January 2026. A MIG 4.1 document dated 29 October 2025 has been published. [5] [6]
A business can issue e-invoices on the platform, through a value-added service centre, or from its own system using the platform's Turnkey software. Its e-invoice system must protect confidentiality, integrity, source authentication and non-repudiation, and must block wrong, duplicate or un-uploaded invoice numbers (E-Invoice Implementation Directions pt 4). [7]
Getting started
- Self-test the e-invoice system before first use (Directions pt 4).
- Apply for e-invoice track numbers. After the self-test, the business estimates its usage per period and applies to its local tax office; once approved, it draws numbers from the platform as needed. Foreign e-service suppliers apply online on the eTax portal and receive an allocation (pt 7). [7]
- Issue in time order and keep the buyer's consent to issue, correct, void or allow an e-invoice for at least 5 years (Uniform Invoice Regulations Art 8; Directions pt 9).
Carriers and B2C cloud invoices
A carrier is used when the buyer asks for the invoice by carrier; the seller then files the buyer's carrier data with the invoice (Business Tax Act Art 32-1). Not printing a paper proof copy is the default (Directions pt 20), and merchants issuing e-invoices may not refuse the MOF common carrier (pt 21). Platforms that sell for other businesses must pass on the buyer's carrier or donation-code data with the transaction data (pt 21 para 2). [7]
Uniform invoices double as lottery tickets: the Ministry of Finance funds the prizes from 3% of annual business-tax revenue, to curb evasion and promote the use of uniform invoices (Business Tax Act Art 58). [1]
Returns and allowances after an e-invoice must be documented by an electronic sales-return or allowance certificate issued by the seller and filed on the platform within the same 7-day / 2-day limits (Uniform Invoice Regulations Art 20-1, from 1 January 2025). [2]
Foreign e-service suppliers: cloud invoices
A foreign business with no fixed place of business in Taiwan that sells electronic services to individuals in Taiwan has had to register for business tax since 1 May 2017 once its annual sales exceed NT$600,000 (NT$480,000 before 7 April 2025). [8]
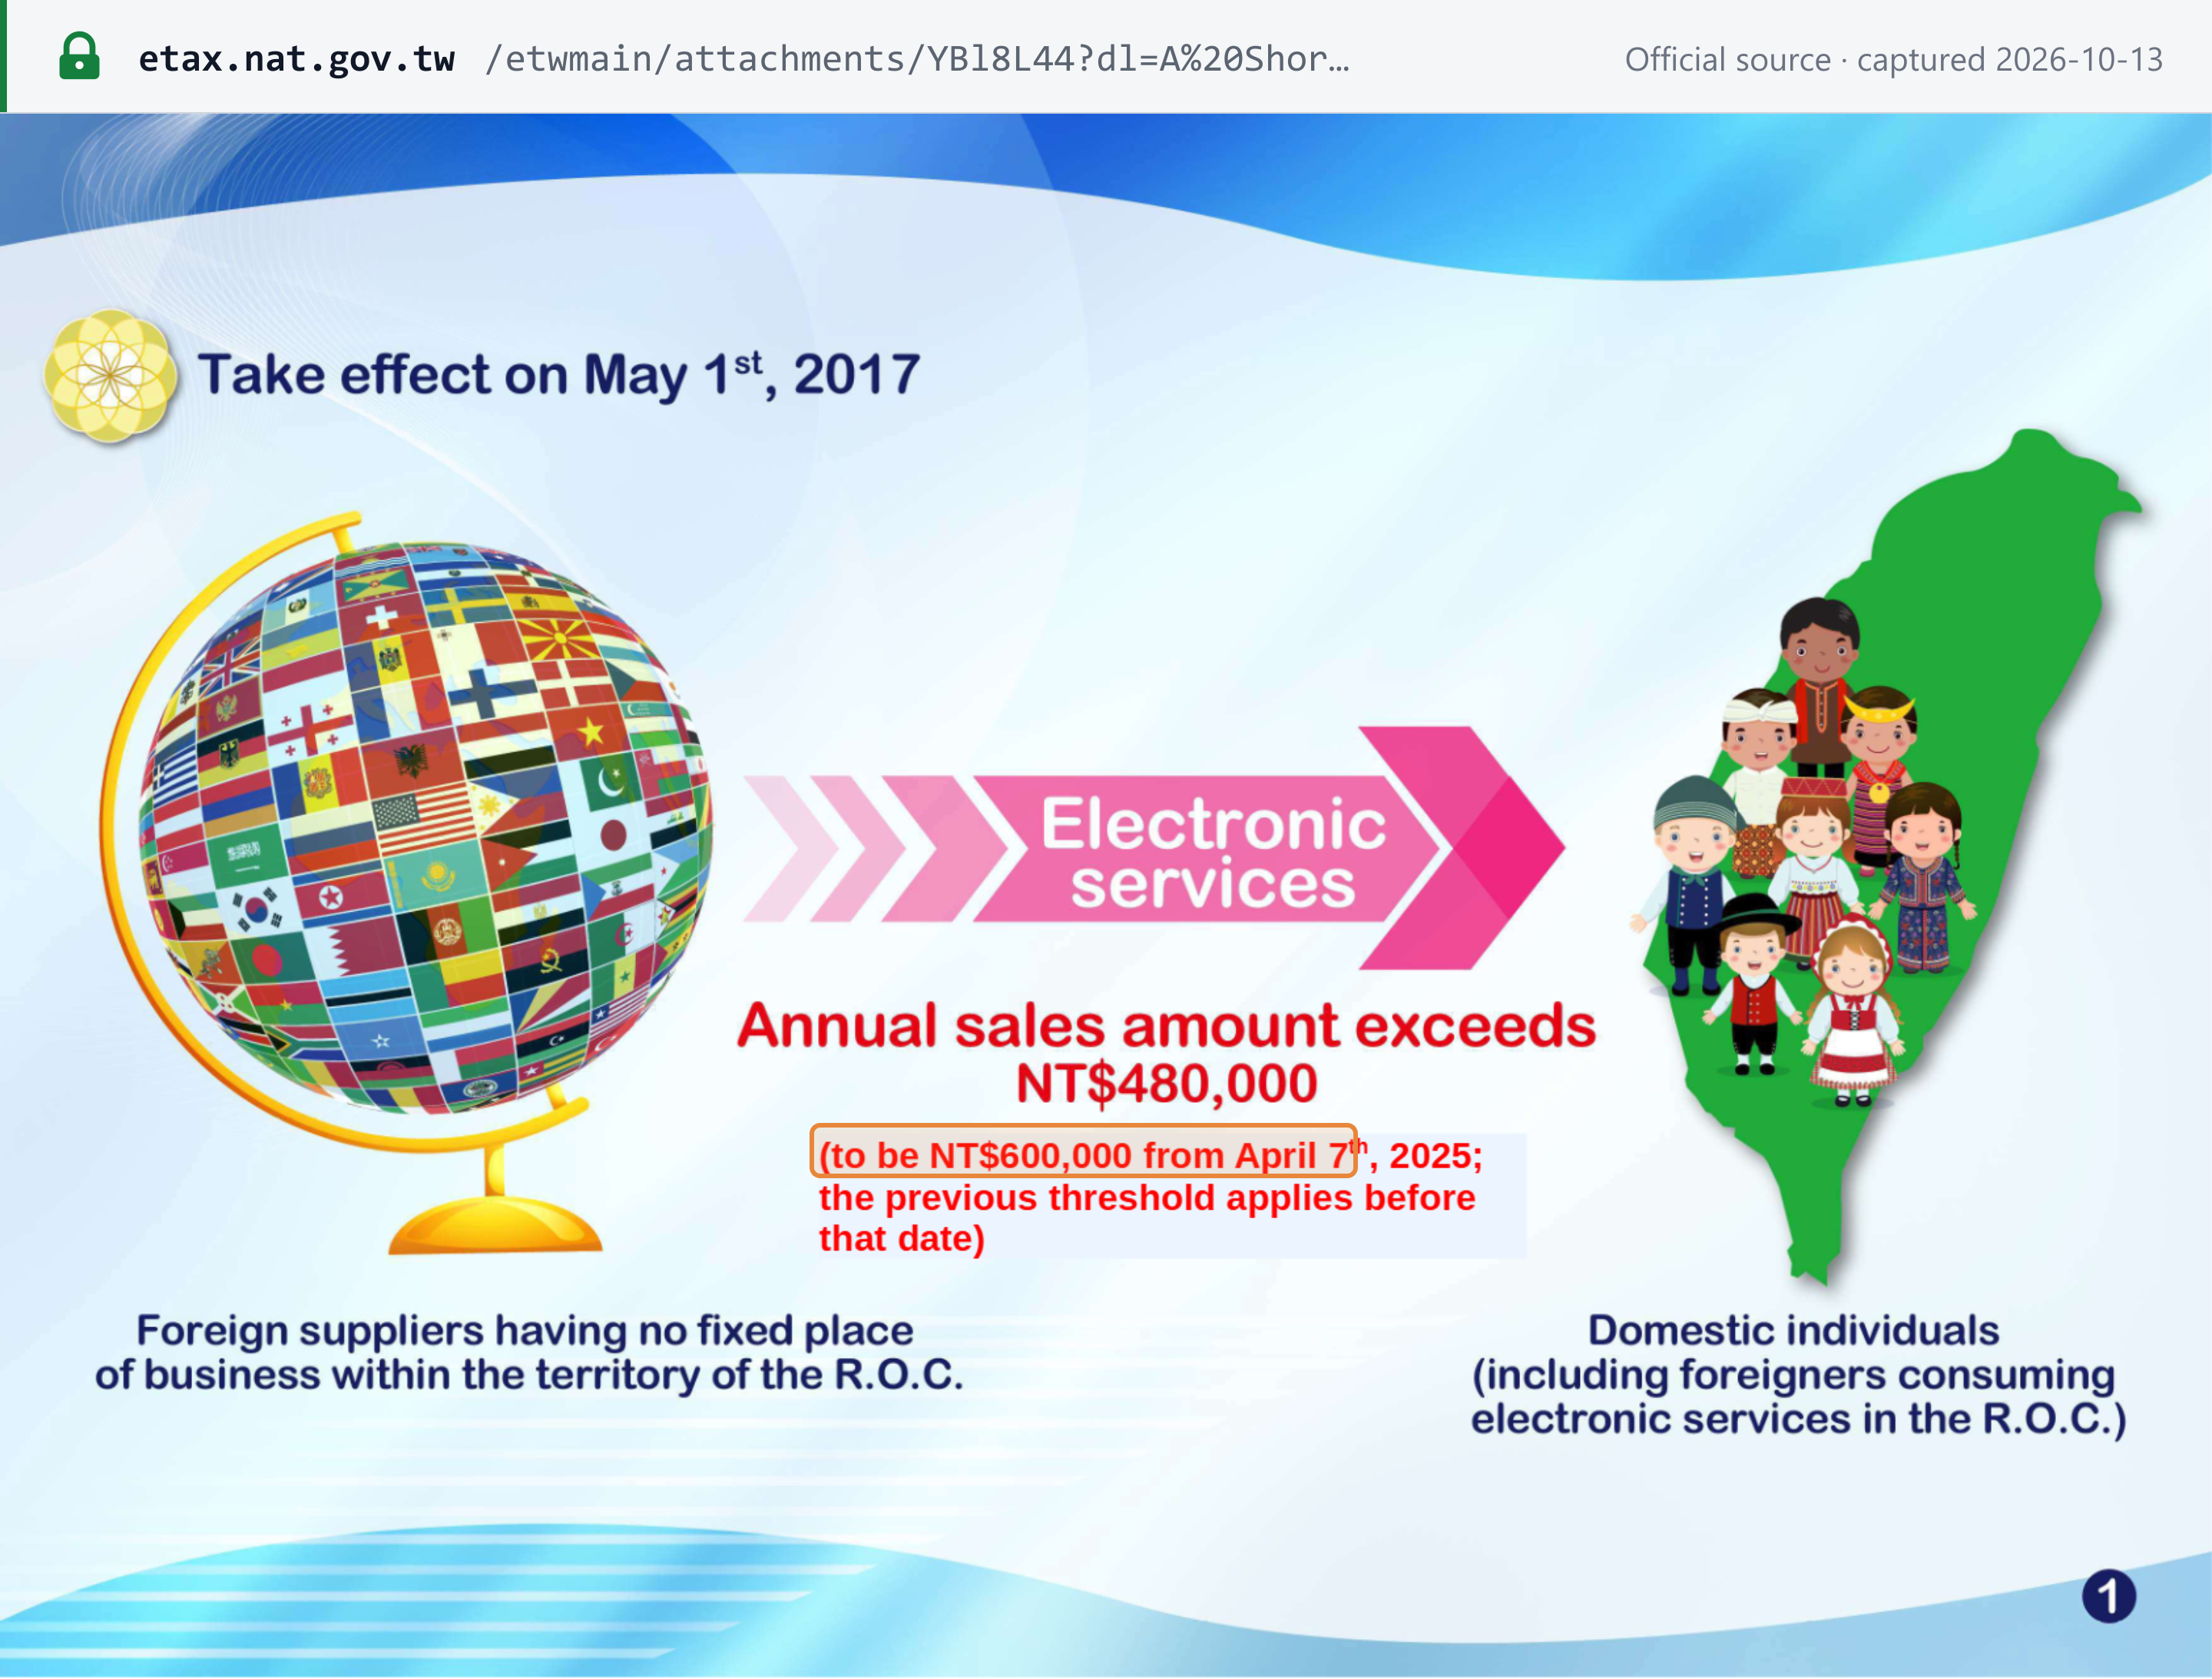
Since 1 January 2019 such a supplier must issue cloud invoices to its buyers (Uniform Invoice Regulations Art 7-1 para 2). From 1 May 2017 to 31 December 2018 it was exempt from issuing invoices and reported its sales directly. It does not have to offer paper proof copies (Directions pt 20). [2] [7] [9]
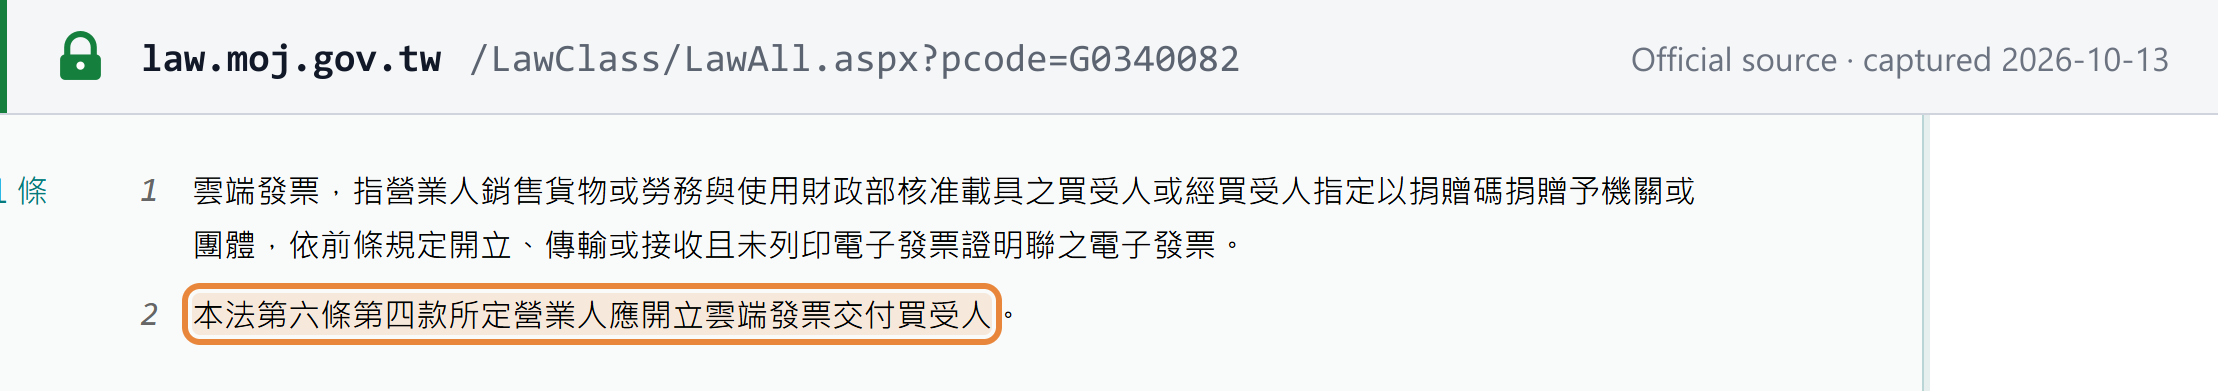
Sales to Taiwanese businesses are not invoiced in this way: the buyer of services from a foreign supplier with no fixed place of business accounts for the tax itself (Business Tax Act Art 36). [1]
Penalties
| Failure | Penalty | Provision |
|---|---|---|
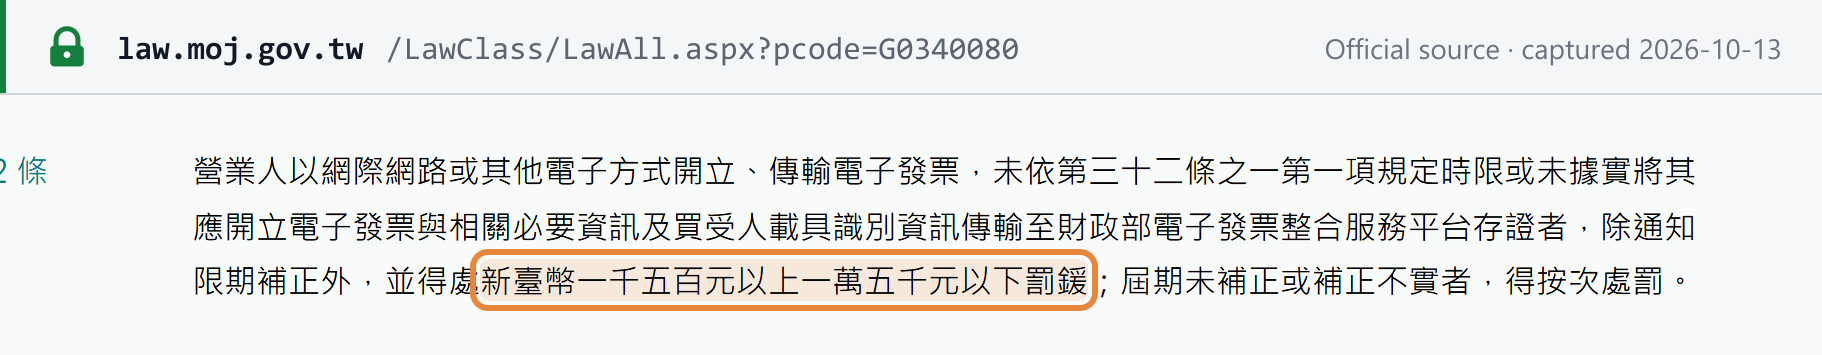
| Late or inaccurate filing of e-invoice data on the platform (from 1 January 2025) | NT$1,500–15,000, alongside a notice to correct; repeatable if not corrected by the deadline | Business Tax Act Art 48-2 |
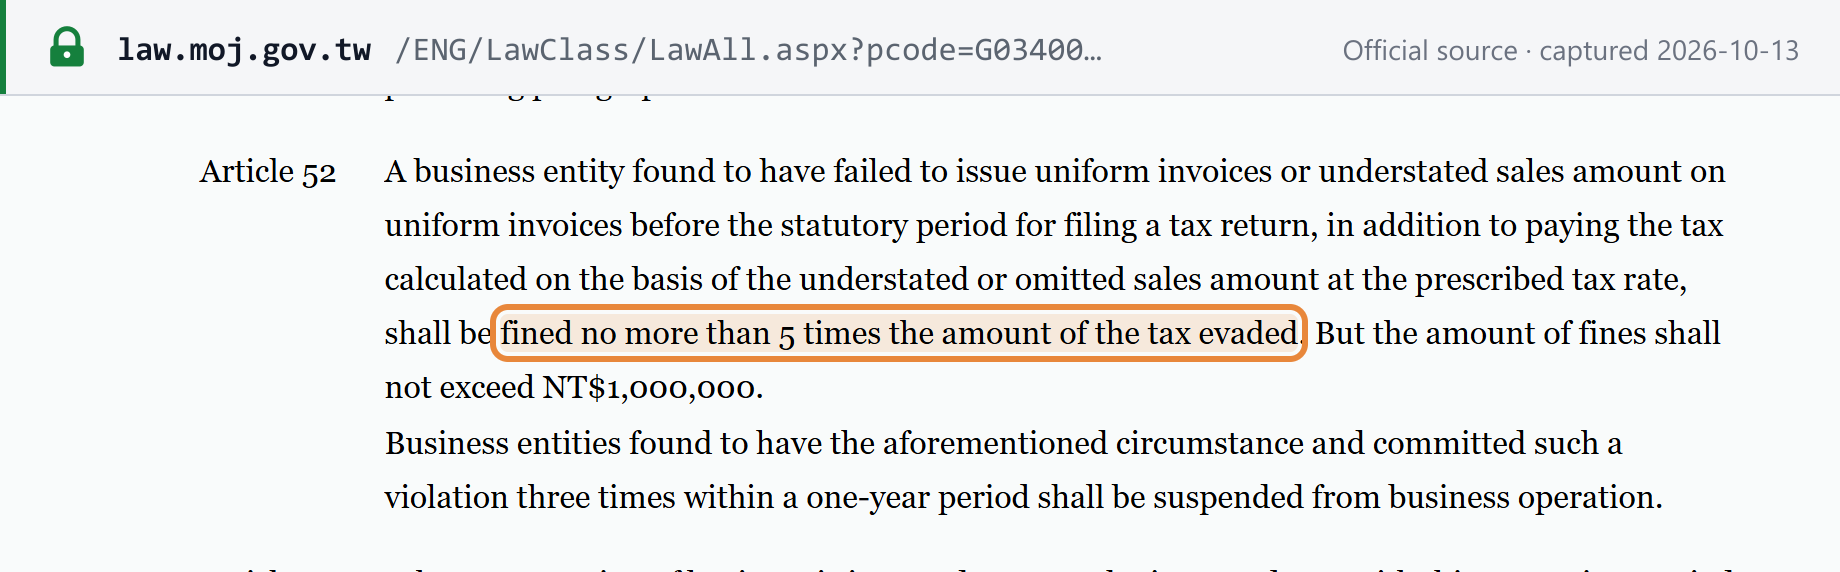
| Failing to issue a uniform invoice, or understating it | The tax plus a fine of up to 5 times the tax evaded, capped at NT$1,000,000; suspension after 3 findings in a year | Art 52 |
| Missing or wrong invoice particulars | 1% of the sales amount (NT$1,500–15,000); from the second offence for the buyer's name, address or BAN, 2% (NT$3,000–30,000) | Art 48 |
| Not using uniform invoices when required | NT$3,000–30,000, repeatable | Art 47 |
Frequently Asked Questions
Does a foreign company selling digital services to consumers in Taiwan have to issue Taiwan e-invoices?
Yes, once it is registered. Since 1 May 2017, a foreign business with no fixed place of business in Taiwan that sells electronic services to individuals in Taiwan must register for business tax when its annual sales exceed NT$600,000 (NT$480,000 before 7 April 2025). Since 1 January 2019 it must issue cloud invoices to those buyers; from 1 May 2017 to 31 December 2018 it was exempt from issuing invoices. Its cloud invoices may be in a foreign language, use Western dates and show foreign-currency amounts if the currency is stated. Taiwanese business buyers of services from a foreign supplier with no fixed place of business account for the tax themselves under Article 36 of the Business Tax Act.
Sources: MOF short version for cross-border electronic services; Uniform Invoice Regulations; cross-border e-commerce Q&A.
Must every invoice in Taiwan be issued through the e-invoice platform?
No. The Uniform Invoice Regulations list five types of uniform invoice: triplicate, duplicate, special, cash-register and electronic. The electronic invoice is one of them, and paper and cash-register invoices remain lawful for domestic sellers. When a business does issue an e-invoice, it must file the e-invoice data on the Ministry of Finance E-Invoice Platform within the prescribed time limits. Registered foreign e-service suppliers selling to individuals must issue cloud invoices.
Source: Uniform Invoice Regulations, Arts 7 and 7-1.
When must a Taiwan e-invoice be issued and uploaded, and what are the penalties?
The time of issue follows the statutory time-limit table attached to the Business Tax Act: for sales of goods, at shipment (or earlier, when payment is received before shipment); for most services, when payment is collected. Once issued, the e-invoice must be filed on the MOF E-Invoice Platform within 7 days where the buyer is a business and within 2 days where the buyer is not, counted from the day after issue, correction or voiding, with no extension for weekends or holidays. Late or inaccurate filing is fined NT$1,500 to NT$15,000 per case, repeatable (Article 48-2, since 1 January 2025). Failing to issue a uniform invoice is fined up to 5 times the tax evaded, capped at NT$1,000,000 (Article 52). Wrong or missing invoice particulars are fined 1% of the sales amount (NT$1,500 to NT$15,000), or 2% (NT$3,000 to NT$30,000) for repeated errors in the buyer's name, address or BAN (Article 48).
Sources: time-limit table; MOF Announcement GL011540; Business Tax Act.
Related resources
- Taiwan tax ID guide
- E-invoicing status and networks by country
- CTC e-invoicing models: clearance, reporting and interchange
- VAT on digital services by non-resident suppliers
Important websites
| Purpose | Website |
|---|---|
| E-invoice issuing, receiving, carriers and MIG downloads | MOF E-Invoice Platform |
| Registration, filing and payment for foreign e-service suppliers | eTax cross-border zone (English) |
| Laws (Business Tax Act, Uniform Invoice Regulations) | Laws & Regulations Database |
| MOF rules and announcements | MOF regulations system |
References
- Value-added and Non-value-added Business Tax Act (English; amended 28 May 2025)
- Uniform Invoice Regulations 統一發票使用辦法 (amended 12 December 2024, in force 1 January 2025)
- The Table of the Time Limits for Issuing Documentary Evidence of Sales (English)
- MOF Announcement 台財稅字第11304654280號 — e-invoice evidence-filing information and time limits (12 December 2024)
- National Taxation Bureau of the Northern Area — reply on MIG 4.0 (14 May 2024)
- E-Invoice Message Implementation Guideline, version 4.1 (Fiscal Information Agency, 29 October 2025)
- E-Invoice Implementation Directions 電子發票實施作業要點 (amended 22 April 2026)
- MOF — A Short Version for the New Provisions of Business Tax (VAT) on Cross-Border Electronic Services
- MOF eTax — Q&A on business tax for cross-border e-commerce (境外電商營業稅課稅新制疑義解答)