E-invoicing in Portugal -eSPap
| Country | Portugal |
| Status - B2G | Mandatory in public procurement. Issuing: large companies since 1 January 2021; SMEs, micro-enterprises and public entities acting as suppliers exempt until 31 December 2026, obliged from 1 January 2027. Receiving: contracting authorities since 18 April 2019 / 18 April 2020 |
| Status - B2B | Voluntary (no mandate; intra-EU B2B under ViDA from 1 July 2030) |
| Status - B2C | No mandate |
| Formats | EN 16931 via CIUS-PT, in UBL 2.1 (B2G) |
| Authority | Entidade de Serviços Partilhados da Administração Pública (eSPap) for B2G; Autoridade Tributária e Aduaneira (AT) for the tax-law invoicing rules |
| Network name | FE-AP (Fatura Eletrónica na Administração Pública), coordinated by eSPap; not Peppol-mandated |
| Legislation | B2G: Decreto-Lei n.º 111-B/2017 (Código dos Contratos Públicos art. 299.º-B; dates in its art. 9.º), Decreto-Lei n.º 123/2018, Lei n.º 73-A/2025 art. 260.º n.º 2. Tax law: Decreto-Lei n.º 28/2019 arts. 4.º, 7.º, 12.º and 35.º, Portaria n.º 195/2020, Lei n.º 73-A/2025 art. 95.º n.º 3 |
Portugal has no clearance (CTC) e-invoicing system and no B2B e-invoicing mandate. Three separate duties apply, and most confusion about Portuguese e-invoicing comes from merging them:
- Structured e-invoicing to public entities (B2G), under public-procurement law: EN 16931 e-invoices in the Portuguese CIUS-PT, mandatory for large companies today and for SMEs from 1 January 2027.
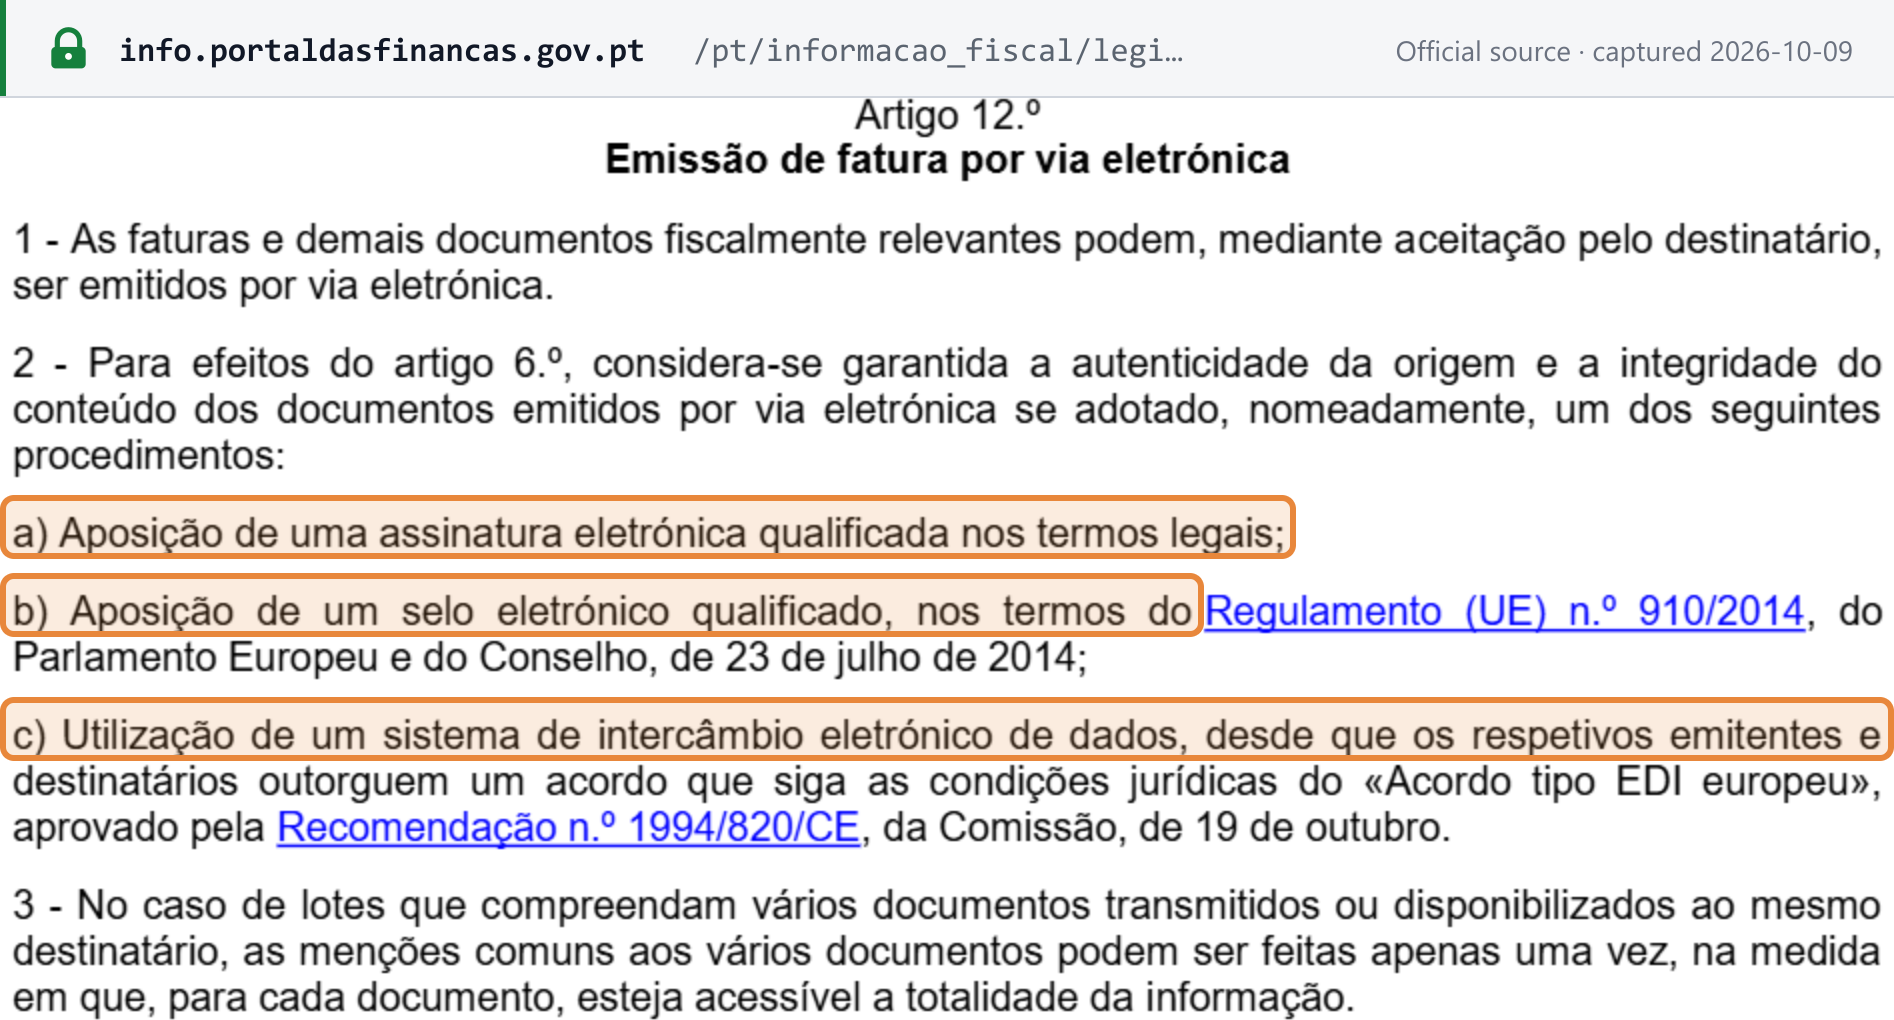
- What counts as an "electronic invoice" under VAT law: an invoice sent electronically with a qualified electronic signature, a qualified electronic seal or EDI, with plain PDF invoices deemed electronic invoices until 31 December 2026.
- Reporting invoice data to the tax authority (AT) by day 5 of the following month. This is reporting, not e-invoicing, and it applies to every issuer.
Mandate status and timeline
The B2G obligation turns on the size of the supplier, not on the value of the contract. Contracting authorities had to be able to receive e-invoices first; suppliers then had to issue them, large companies first.
| Who | What becomes mandatory | Date | Status | Legal instrument |
|---|---|---|---|---|
| The State (direct administration) and public institutes | Receive and process e-invoices | 18 April 2019 | Passed | Decreto-Lei n.º 123/2018, amending Decreto-Lei n.º 111-B/2017 |
| All other contracting entities (including Autonomous Regions, municipalities, independent administrative bodies, Banco de Portugal, public foundations and associations) | Receive and process e-invoices | 18 April 2020 | Passed | Decreto-Lei n.º 123/2018 |
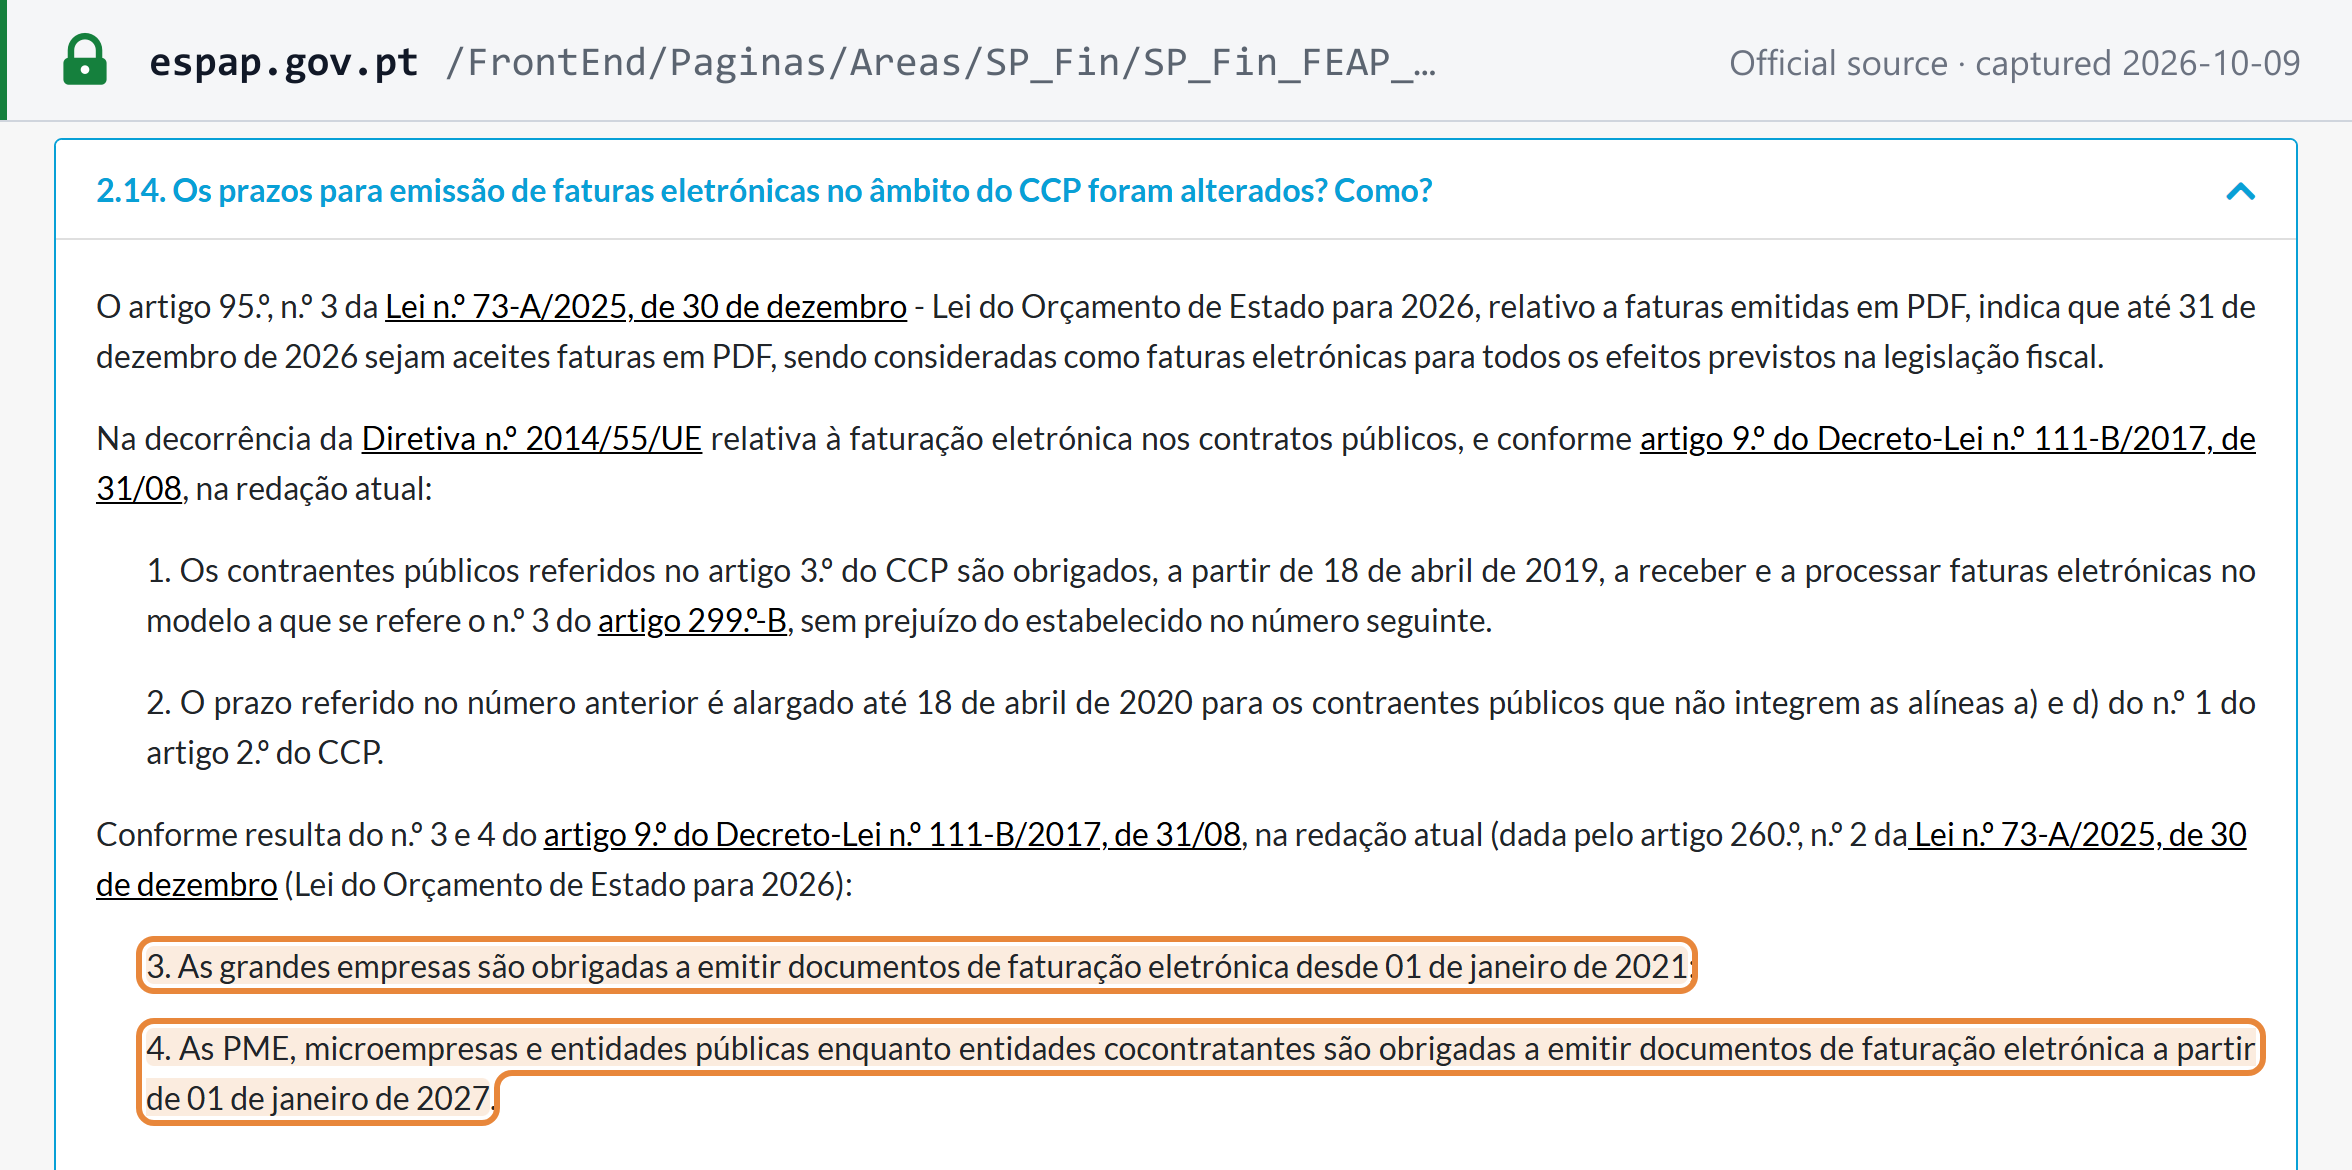
| Large companies supplying under public contracts | Issue EN 16931 e-invoices (CIUS-PT) | 1 January 2021 | Passed | Decreto-Lei n.º 111-B/2017 art. 9.º, as amended |
| Micro, small and medium enterprises, and public entities acting as suppliers | Issue EN 16931 e-invoices (CIUS-PT); exempt until 31 December 2026 | 1 January 2027 | Upcoming | Lei n.º 73-A/2025 art. 260.º n.º 2, prorogating Decreto-Lei n.º 111-B/2017 art. 9.º n.º 4 |
Sources: Decreto-Lei n.º 123/2018 [1]; Lei n.º 73-A/2025 [2]; eSPap, FAQ Fatura Eletrónica (large companies "desde 01 de janeiro de 2021"; SMEs and micro-enterprises "a partir de 01 de janeiro de 2027").
 Source snapshot captured 2026-10-09 — original
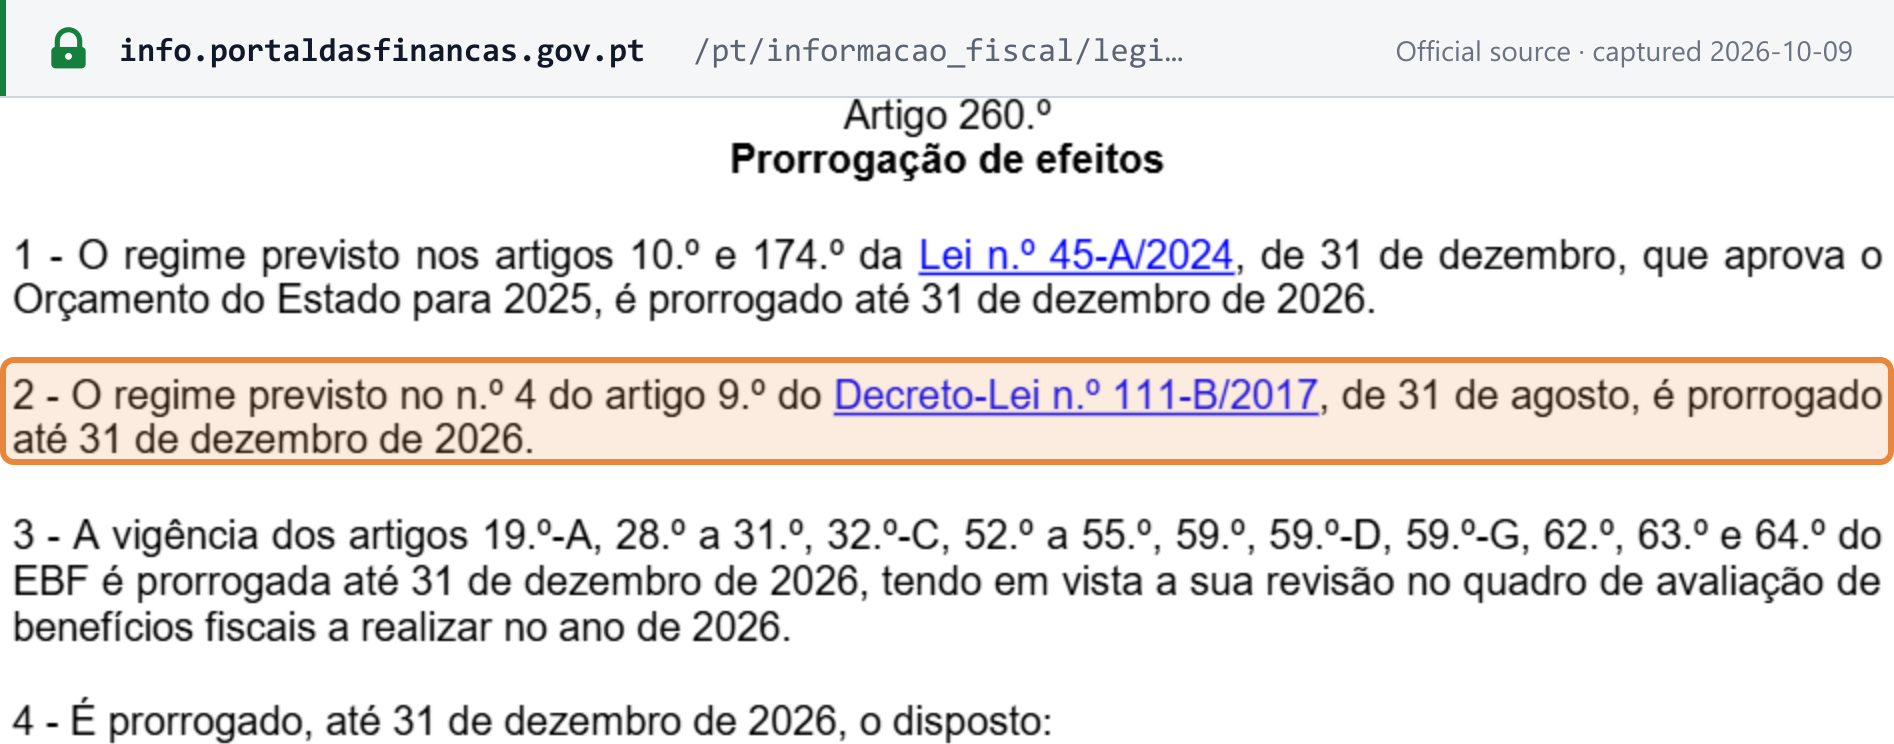
Postponements. Decreto-Lei n.º 123/2018 originally gave SMEs and public entities acting as suppliers until 31 December 2020. That exemption has been extended repeatedly since 2020. The current extension is the 2026 State Budget: "O regime previsto no n.º 4 do artigo 9.º do Decreto-Lei n.º 111-B/2017, de 31 de agosto, é prorrogado até 31 de dezembro de 2026." (Lei n.º 73-A/2025, art. 260.º n.º 2) [2] Because the end date has been moved repeatedly, by decree-law and most recently in the State Budget law, check the 2027 State Budget law before planning against 1 January 2027.
 Source snapshot captured 2026-10-09 — original
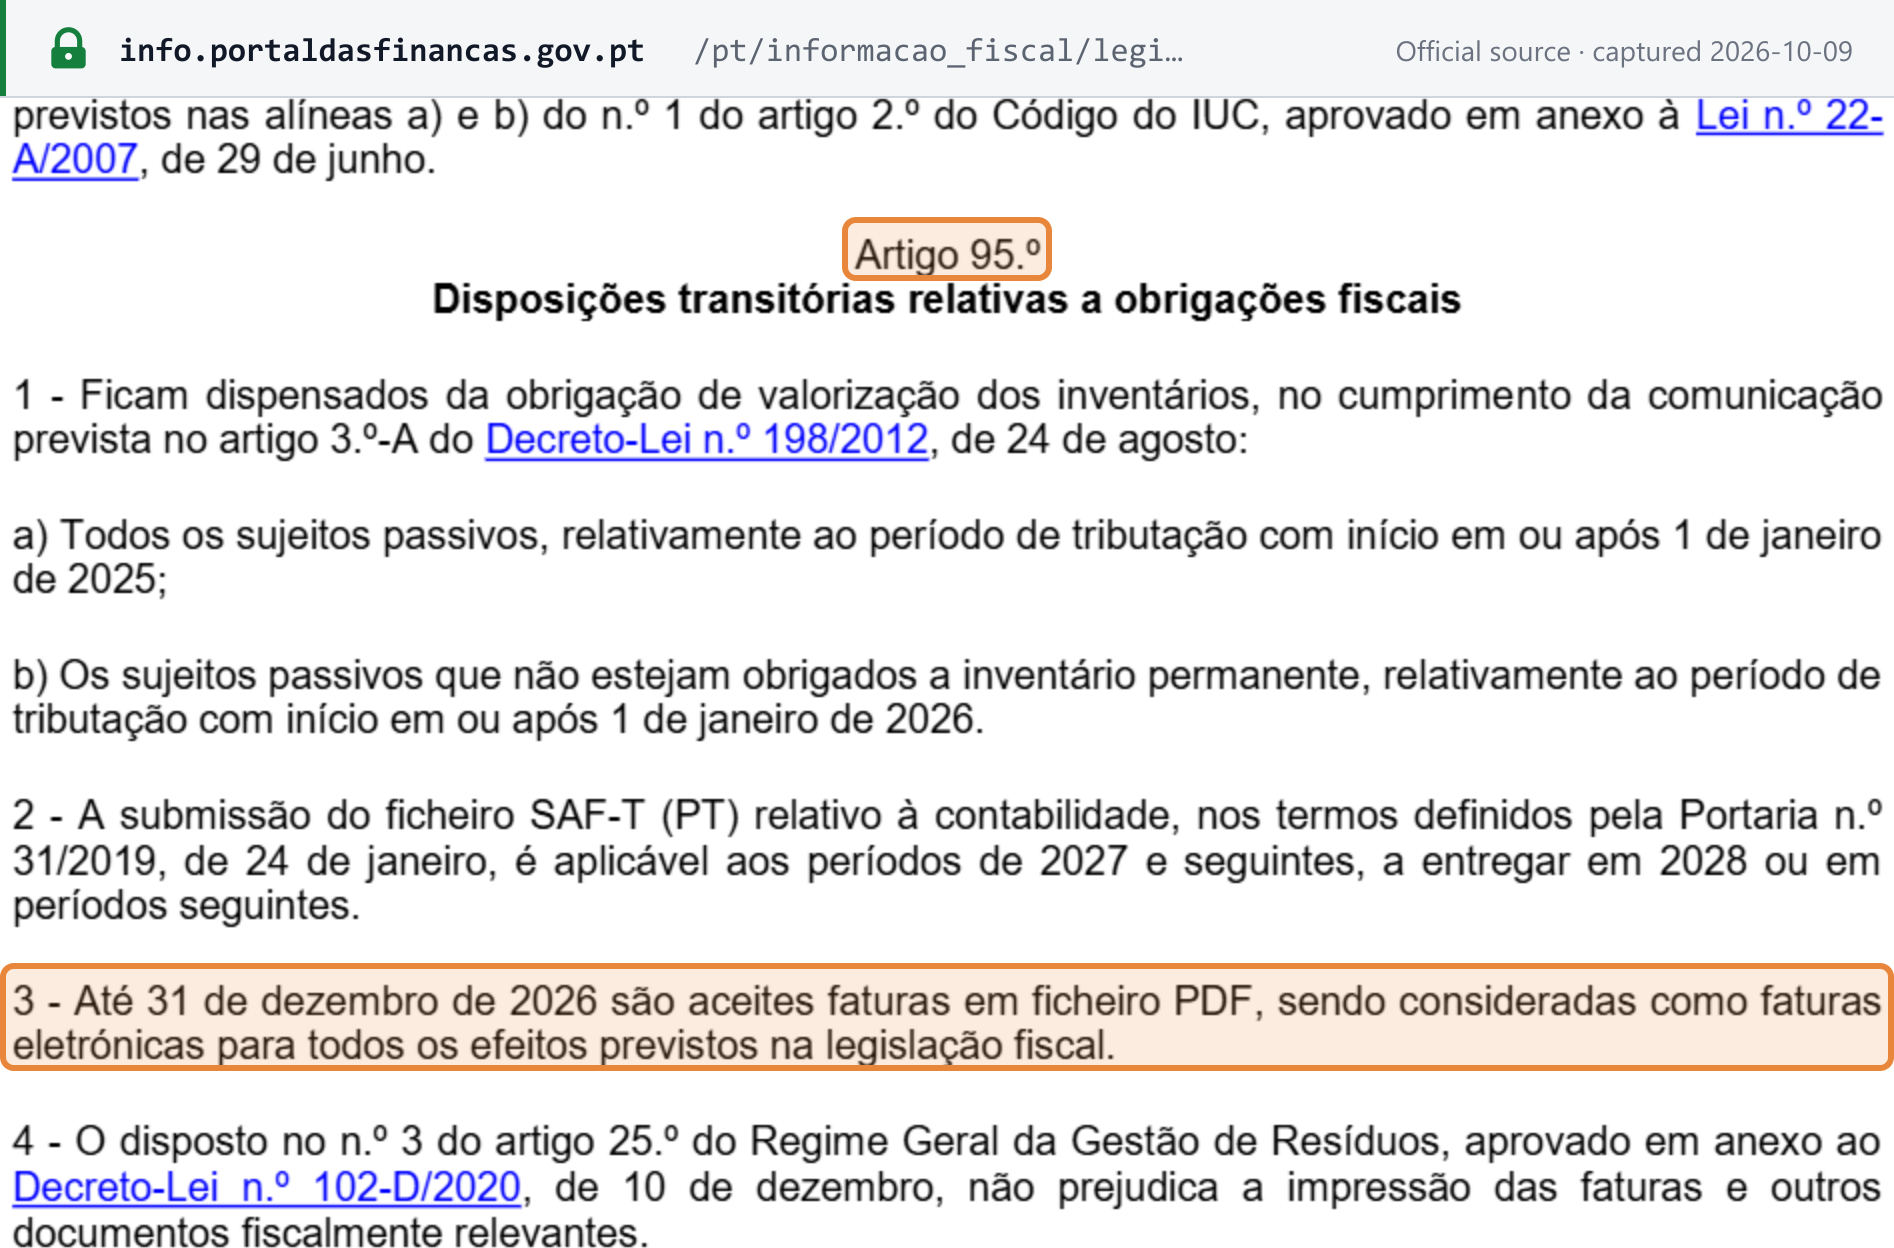
PDF invoices under VAT law. Separately from public procurement, the 2026 State Budget provides: "Até 31 de dezembro de 2026 são aceites faturas em ficheiro PDF, sendo consideradas como faturas eletrónicas para todos os efeitos previstos na legislação fiscal." Until 31 December 2026, PDF invoices are accepted and treated as electronic invoices for all purposes of tax law (Lei n.º 73-A/2025, art. 95.º n.º 3). [2] This deemed status has been extended repeatedly, first by despachos of the Secretary of State for Tax Affairs (to 30 June 2022, then to 31 December 2023) and most recently in the State Budget law. Under current law, from 1 January 2027 an emailed PDF without a qualified electronic signature, a qualified electronic seal or EDI no longer has it.
 Source snapshot captured 2026-10-09 — original
Legal basis
Public procurement (B2G)
- Decreto-Lei n.º 111-B/2017 (31 August 2017) transposed Directive 2014/55/EU by inserting article 299.º-B into the Código dos Contratos Públicos: invoices in public contracts must be electronic and comply with EN 16931. Its article 9.º holds the phase-in dates.
- Decreto-Lei n.º 123/2018 (28 December 2018) set the receiving dates above and gave eSPap the coordination of the rollout. [1]
- Lei n.º 73-A/2025 (State Budget 2026), article 260.º n.º 2: SME, micro-enterprise and public-entity suppliers exempt until 31 December 2026. [2]
Tax law (all invoices)
- Decreto-Lei n.º 28/2019: article 4.º n.º 1 (who must use AT-certified software), article 7.º (ATCUD) and article 12.º (invoices issued by electronic means). [3]
- Portaria n.º 195/2020 (13 August 2020): communication of invoice series to the AT and the technical rules for the ATCUD and the QR code.
- Lei n.º 73-A/2025, article 95.º n.º 3: PDF invoices deemed electronic invoices until 31 December 2026. [2]
- Decreto-Lei n.º 198/2012, article 3.º n.º 2, as amended by Lei n.º 12/2022: invoice-data communication by day 5 of the following month. [4]
Public Sector E-Invoicing Mandate
Portugal’s mandate for e-invoicing in public procurement comes from Directive 2014/55/EU on electronic invoicing in public contracts, transposed by Decreto-Lei n.º 111-B/2017. Which suppliers must issue e-invoices depends on their size: large companies since 1 January 2021, and micro, small and medium enterprises and public entities acting as suppliers from 1 January 2027.
eSPap (Entidade de Serviços Partilhados da Administração Pública) coordinates the rollout. Its FE-AP service (Fatura Eletrónica na Administração Pública) is the public administration's e-invoicing service. [7]
Suppliers that are obliged must issue structured e-invoices in XML aligned with the European standard (EN 16931), in the Portuguese CIUS-PT. Contracting authorities have had to receive them since 18 April 2019 (the State and public institutes) and 18 April 2020 (all other contracting entities).
The aim is to automate and streamline the entire invoice-to-pay process for public procurement. Electronic invoices received through FE-AP can interface with the government’s financial management systems. This is expected to reduce processing costs, improve transparency, and speed up payment cycles.
Private Sector E-Invoicing
For transactions between private companies (B2B) and from businesses to consumers (B2C), structured e-invoicing in Portugal is voluntary. No Portuguese law found as of 8 October 2026 mandates it or sets a date for it, and no bill to that effect was found. Businesses exchange invoices in whatever format they agree, subject to the tax-law rules on certified software, ATCUD, QR code, data reporting and the PDF rule above.
The only dated structured B2B requirement in view is EU-wide. Under the ViDA package (Directive (EU) 2025/516), intra-EU B2B supplies will need EN 16931 e-invoices from 1 July 2030, and since 14 April 2025 member states may mandate domestic e-invoicing without a derogation. [5] See the ViDA guide.
Reporting Invoice Data to the AT
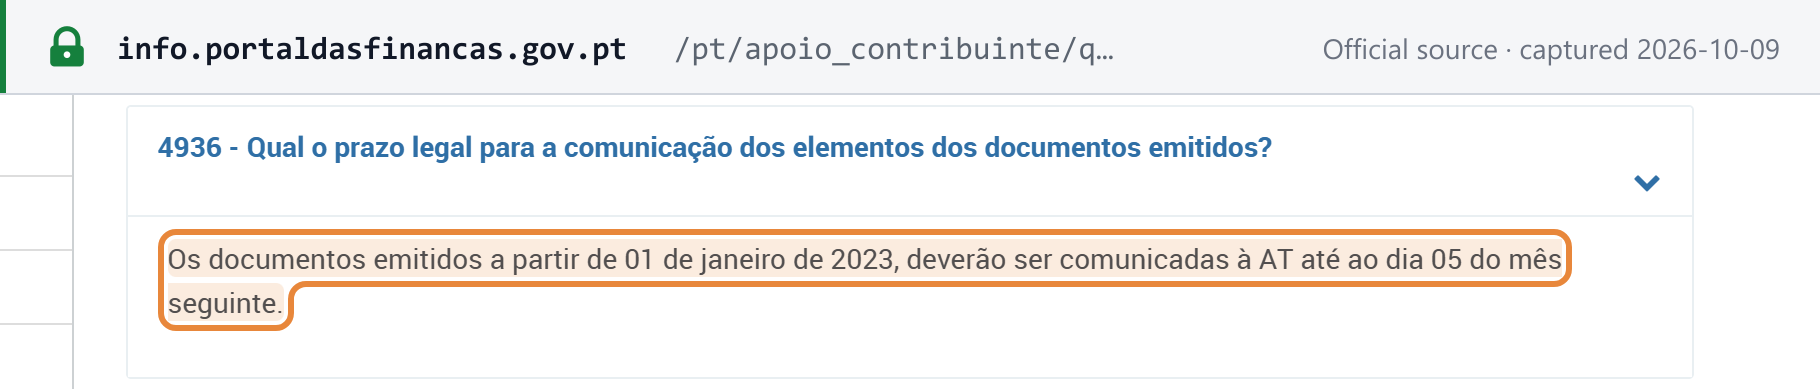
Separately from how you issue an invoice, the data on it has to reach the tax authority. Invoice issuers covered by Decreto-Lei n.º 198/2012 must communicate the elements of the invoices they issue to the Autoridade Tributária e Aduaneira by day 5 of the month following issue.
That deadline has applied since 1 January 2023 (for invoices issued in 2023, Despacho SEAF n.º 8/2022-XXIII allowed communication up to day 8 of the following month without surcharges or penalties [9]). Guidance still quoting the 20th or the 12th describes a rule that has been replaced. The governing text is Decreto-Lei n.º 198/2012 artigo 3.º n.º 2, as amended by Lei n.º 12/2022, and the AT restates it in FAQ 4936. [6] The data can be sent as a SAF-T (PT) file, through a webservice, or by entry on the Portal das Finanças.
 Source snapshot captured 2026-10-09 — original
This monthly invoice-data communication is a different obligation from the accounting SAF-T (PT) file, which is submitted annually with the IES and which, under current law (the 2026 Budget), applies to periods from 2027, filed in 2028. The two are routinely conflated; only the monthly one is a recurring e-invoicing deadline. Portugal's other recurring indirect-tax dates are in the Portugal compliance calendar.
E-Invoicing Formats and Platforms
Public procurement. B2G e-invoices must follow EN 16931 through the Portuguese CIUS-PT, in UBL 2.1; eSPap lists its UN/CEFACT CII binding of CIUS-PT as still under construction. eSPap publishes the CIUS-PT specification and coordinates the rollout; FE-AP is the public administration's e-invoicing service. The official sources reviewed do not make Peppol the mandated network. A PDF is not an EN 16931 e-invoice, so a supplier already obliged to e-invoice a public entity must send CIUS-PT XML.
Tax law (every invoice). Portugal does not clear invoices before issue: it is a post-audit model with periodic invoice-data reporting (see CTC e-invoicing models). Under Decreto-Lei n.º 28/2019 article 12.º, invoices may be issued by electronic means, subject to the customer's acceptance, provided the authenticity of their origin and the integrity of their content are guaranteed. Those requirements are presumed met when the issuer uses a qualified electronic signature, a qualified electronic seal, or EDI. [3] A plain PDF uses none of the three; it counts as an electronic invoice only under the transitional rule that runs to 31 December 2026.
 Source snapshot captured 2026-10-09 — original
Integrity mechanics.
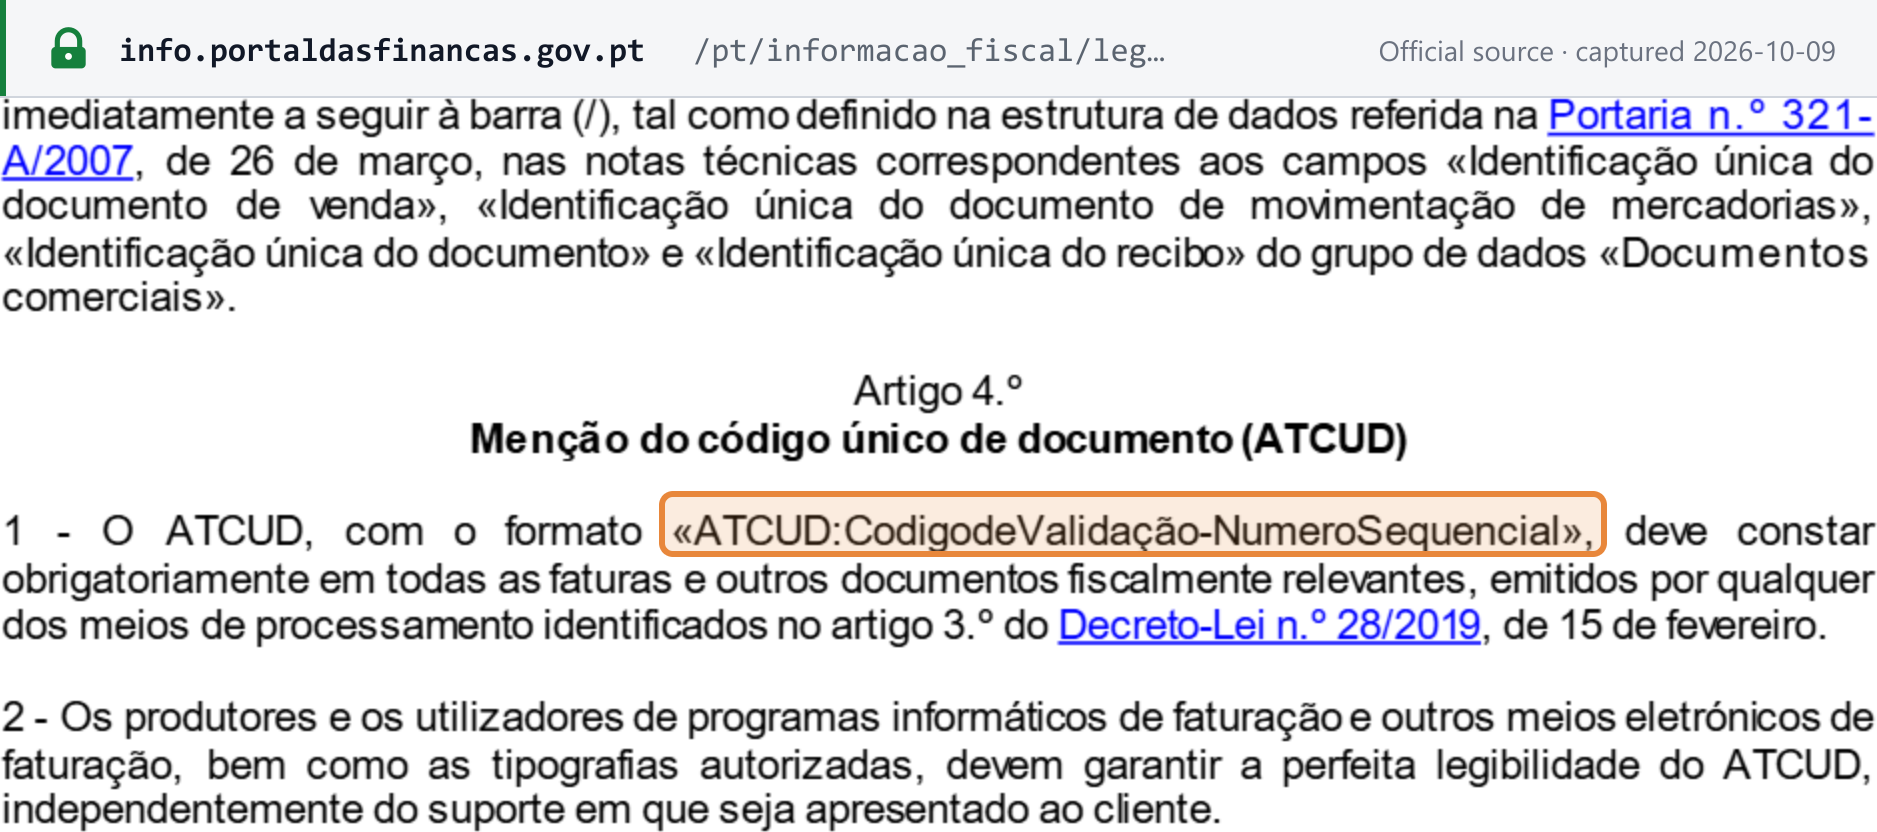
- ATCUD (mandatory since 1 January 2023). Each invoice series must be communicated to the AT
before use; the AT assigns a validation code, and the ATCUD on each document combines that code
with the document's sequential number (
ATCUD:<validation code>-<sequence number>), under Portaria n.º 195/2020.
 Source snapshot captured 2026-10-09 — original
- QR code (mandatory since 1 January 2022) on documents from AT-certified billing software.
- Both are regulated by Portaria n.º 195/2020.
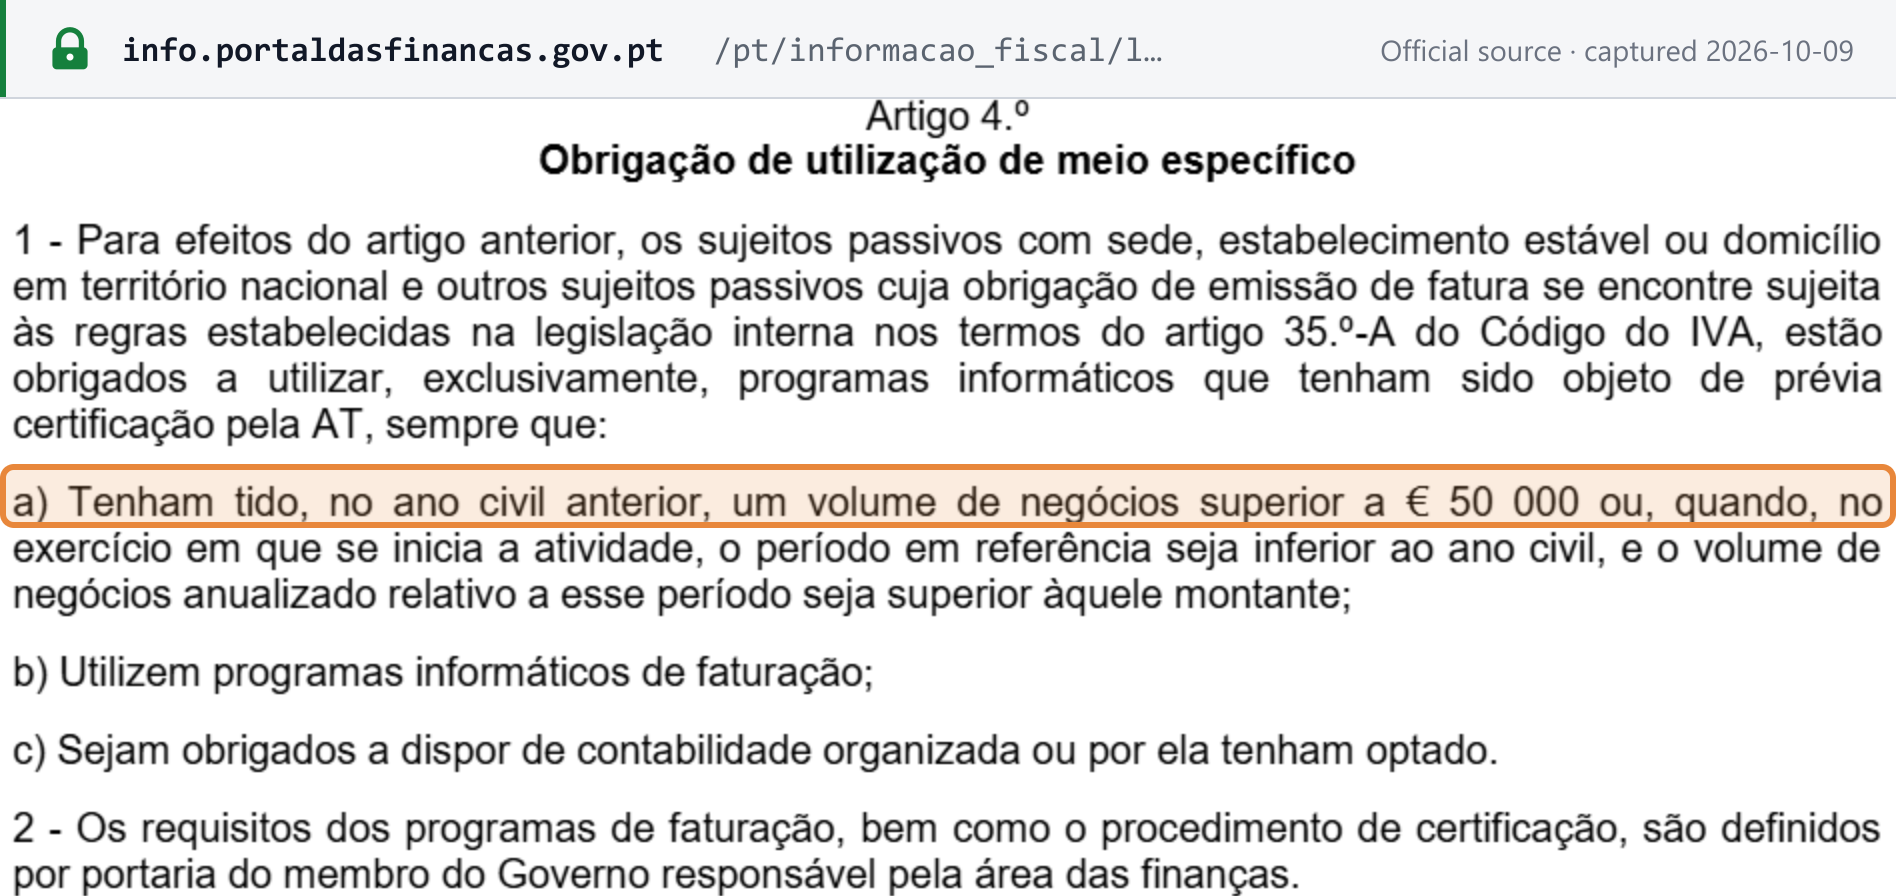
- AT-certified invoicing software is required for VAT taxpayers with turnover above EUR 50,000 in the previous year, for those who use computer programs to invoice, and for those who have or opt for organised accounting (Decreto-Lei n.º 28/2019, article 4.º n.º 1). [3]
 Source snapshot captured 2026-10-09 — original
Issuing and Receiving E-Invoices
Suppliers send structured CIUS-PT XML invoices to public entities that use eSPap's FE-AP service, by web service or AS2. eSPap validates each document against the CIUS-PT rules before forwarding it to the buyer. Over web services the document must carry a qualified electronic signature or qualified electronic seal; over AS2 a document signature is optional because the channel itself is signed. [7]
Suppliers can check the processing status of a document they sent using the RequestId returned on submission. [8]
For B2B and B2C invoices, issuers and receivers exchange invoices in formats and methods mutually agreed upon, such as EDI, email, web uploads etc. However, businesses are likely to transition to structured e-invoicing over time, especially if it gets mandated.
E-Invoice Processing and Integration
FE-AP automates much of the invoice receipt, registration and routing process for government entities. Invoice data can be fed into the entity’s financial system, avoiding manual re-entry.
However, proper integration still needs to be implemented by each public entity to update payables in accounting, post against appropriate cost centers, reconcile invoices and perform three-way matching with purchase orders.
Private companies face similar integration challenges to incorporate inbound e-invoices into their financial systems and ERPs seamlessly. Adoption of automated workflows for handling and approval of e-invoices can significantly optimize the order-to-pay cycle.
Asynchronous document exchange flow
- The issuer's system (ERP) sends a legal document (invoice, credit note or debit note) and immediately receives (synchronously) a RequestId.
- If the document is processed successfully (quality control with no errors reported), eSPap sends it to the receiving system through the established communication channel.
- At any time, the issuer's system can query eSPap with the RequestId from the submission response (step 1) to obtain the result of processing.
- The receiving system sends status messages as it processes and validates the document.
- The issuer's system periodically asks eSPap whether there are status messages; the query returns the unread messages for a given NIF.
- The issuer's system retrieves each status message sent by the customer's system.
- Once it has read a status message correctly, the issuer's system marks it as read in eSPap's system.
Source: eSPap, guide to transmitting electronic documents to FE-AP (CIUS-PT), version 1.6.0. [8]
Benefits and Challenges of E-Invoicing
The transition to e-invoicing brings significant benefits but also some change management challenges:
Key Benefits:
- Cost reduction from eliminating paper and manual processing
- Faster settlement of invoices and improved cash flow
- Increased accuracy of data for accounting and tax reporting
- Enhanced visibility into invoice processing status
- Better archival and analytics on invoice data
- Seamless integration with national reporting systems
Key Challenges:
- Change management and user training on new processes
- Upgrading existing finance systems and integration work needed
- Dependency on reliability of central e-invoicing platform
- Adapting workflows to handle exceptions like rejections
- Getting buy-in and transitioning suppliers currently issuing paper invoices
- Cybersecurity risks from increasing digital attack surfaces
Overall, the gains for government, private entities, and the national economy from transitioning to automated e-invoicing at scale justify the temporary disruptions and costs involved.
Recommendations for Smooth Transition
Both private and public sector organizations in Portugal should take the following steps for a successful transition to e-invoicing:
- Do a comprehensive review of existing invoice workflows and data needs – identify changes required to extract and provide all information required for structured e-invoicing.
- Assess software systems and determine upgrades, integrations, and new solutions needed – including accounting software, ERPs, procurement systems, etc.
- Consult with major existing suppliers and key customers on their e-invoicing readiness and capabilities.
- Provide technical specifications and testing facilities early on to involve suppliers in the transition.
- Validate that all electronic invoice formats and transmission methods comply with legal requirements.
- Train accounts payable and procurement teams on new e-invoicing procedures and exception management.
- Implement robust cybersecurity controls to prevent unauthorized access to invoice data during transmission or storage.
- Start transition by onboarding larger suppliers first followed by smaller suppliers – conduct pilot tests before full-scale rollout.
- Plan for contingencies and business continuity procedures in case of disruptions to availability of e-invoicing platforms.
Frequently Asked Questions
Details
We are an SME supplying a Portuguese public entity. Do we already have to send structured e-invoices?
Not yet, under current law. Micro, small and medium enterprises, and public entities acting as suppliers, may keep invoicing public contracting entities without structured e-invoices until 31 December 2026: Lei n.º 73-A/2025 (State Budget 2026), article 260.º n.º 2, prorogues the transitional regime in article 9.º n.º 4 of Decreto-Lei n.º 111-B/2017 to that date. eSPap states that they must issue e-invoices from 1 January 2027. Large companies have had to issue them since 1 January 2021. The obligation turns on the supplier's size, not on the value of the contract.Details
Is an emailed PDF invoice a valid electronic invoice in Portugal?
For VAT purposes, yes, until 31 December 2026. Lei n.º 73-A/2025, article 95.º n.º 3, accepts invoices in PDF files and treats them as electronic invoices for all purposes of tax law until that date. Outside that transitional rule, Decreto-Lei n.º 28/2019, article 12.º, presumes the authenticity and integrity of an electronic invoice when the issuer uses a qualified electronic signature, a qualified electronic seal or EDI, and a plain PDF uses none of the three. Public procurement is a separate rule: a PDF is not an EN 16931 e-invoice, so a supplier already obliged to e-invoice a public entity must send CIUS-PT XML.Details
Is B2B e-invoicing mandatory in Portugal?
No. As of 8 October 2026 no Portuguese law mandates structured e-invoicing between businesses or to consumers, and parties exchange invoices in a format they agree. Those invoices still follow the tax-law rules: AT-certified software where required, an ATCUD and a QR code on the document, and communication of the invoice data to the AT by day 5 of the following month. The only dated structured B2B requirement in view is EU-wide: under Directive (EU) 2025/516 (ViDA), intra-EU B2B supplies need EN 16931 e-invoices from 1 July 2030.Details
Does sending our SAF-T (PT) file to the AT count as e-invoicing?
No. Communicating invoice data to the AT is a reporting duty, not a way of delivering the invoice to the customer. Invoice issuers covered by Decreto-Lei n.º 198/2012 must communicate the elements of the invoices they issue by day 5 of the month following issue, a deadline in force since 1 January 2023 (Decreto-Lei n.º 198/2012 artigo 3.º n.º 2, as amended by Lei n.º 12/2022; AT FAQ 4936). The data can go by SAF-T (PT) file, by webservice or by entry on the Portal das Finanças. The annual accounting SAF-T (PT) is a different obligation again, which, under current law, applies from the 2027 periods, filed in 2028.Details
What do the ATCUD and the QR code require, and since when?
Both are mandatory and both are regulated by Portaria n.º 195/2020. The QR code has been required since 1 January 2022 and the ATCUD since 1 January 2023. Before using an invoice series, the issuer must communicate it to the AT, which assigns a validation code for that series (Portaria n.º 195/2020). The ATCUD printed on each document combines that validation code with the document's sequential number in the series, in the form ATCUD:validation code-sequence number.Details
Who has to use AT-certified invoicing software?
VAT taxpayers who had turnover above EUR 50,000 in the previous year, who use computer programs to invoice, or who have or opt for organised accounting must invoice through software certified by the AT (Decreto-Lei n.º 28/2019, article 4.º n.º 1).Related resources
- Portugal VAT country guide
- E-invoicing status and networks worldwide
- SAF-T reporting explained
- ViDA — VAT in the Digital Age
- E-invoicing in Spain — FACe