An Explainer Guide to E-invoicing in Norway
| Country | Norway |
| Status - B2G | Mandatory |
| Status - B2B | Voluntary until 31 December 2026; e-invoices must be issued and received between bookkeeping-liable parties from 1 January 2027 (Bookkeeping Act § 10, as amended by LOV-2026-06-19-39); implementing regulations pending |
| Status - B2C | NA |
| Formats | EHF 3.0, Peppol BIS |
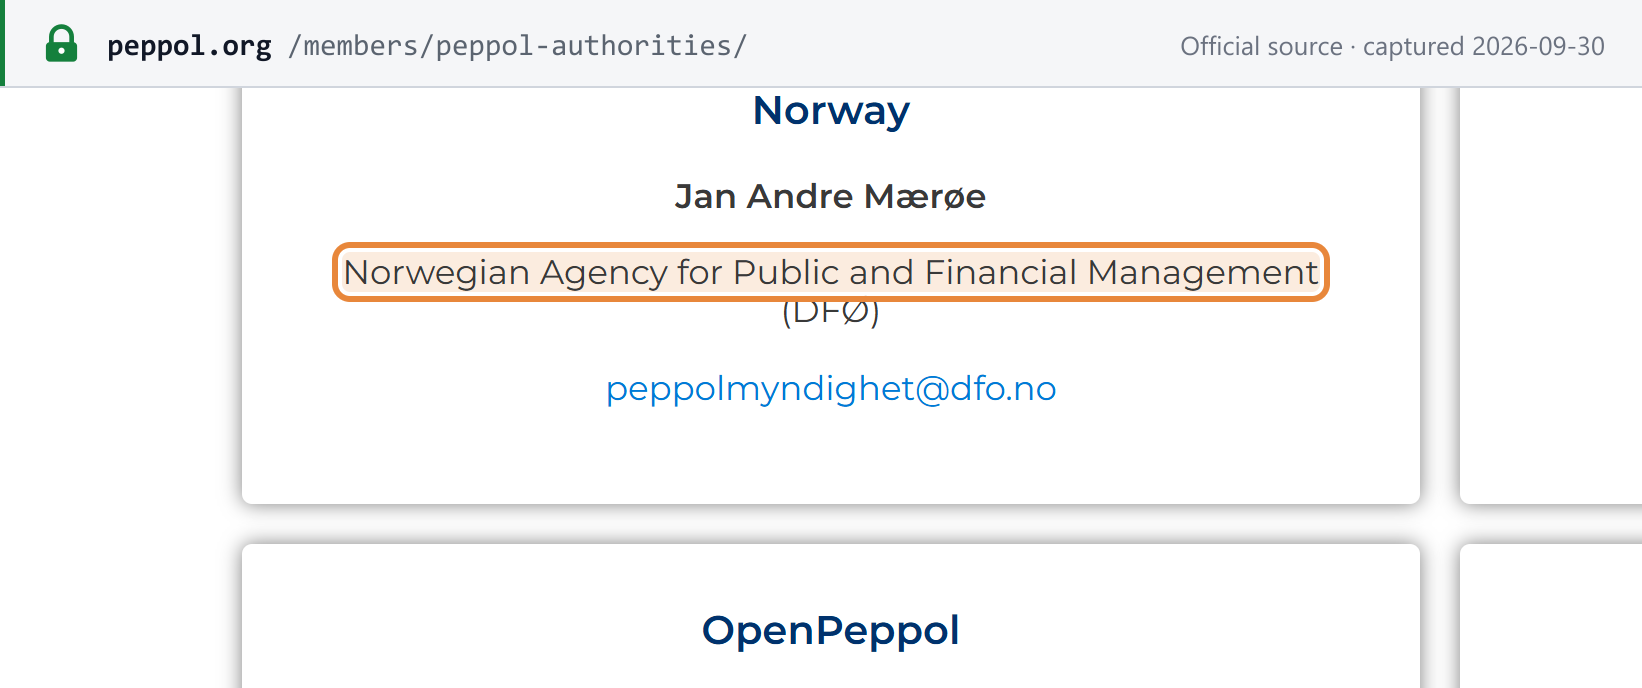
| Authority | Norwegian Agency for Public and Financial Management (DFØ) — Peppol Authority |
| Network name | Peppol |
| Legislation | B2G: FOR-2019-04-01-444 (e-invoicing in public procurement). B2B: Bookkeeping Act (LOV-2004-11-19-73) § 10, as amended by LOV-2026-06-19-39 |
Overview
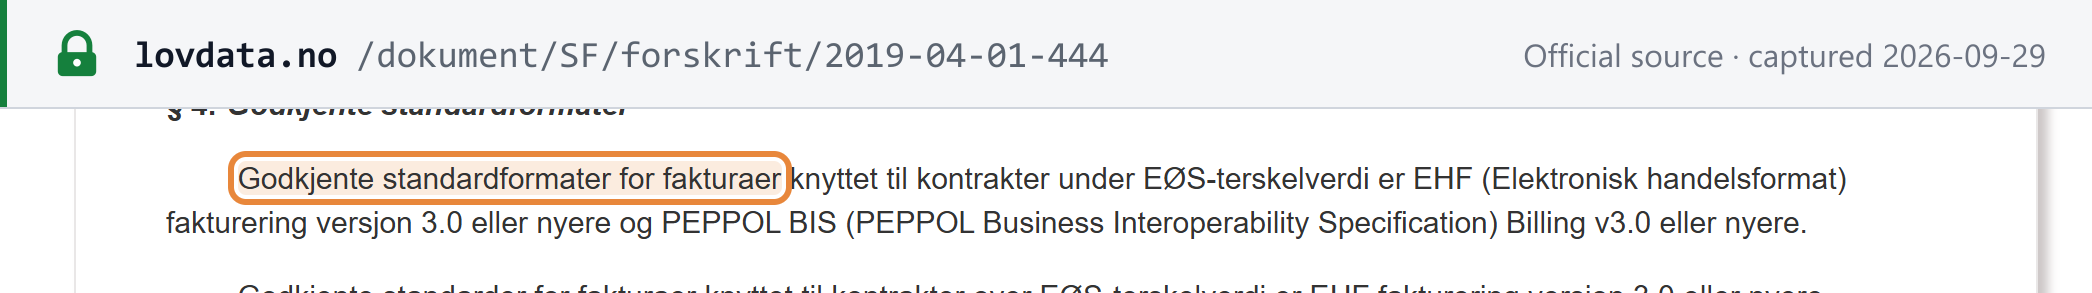
B2G. Under the Regulation on electronic invoicing in public procurement (FOR-2019-04-01-444), in force on 2 April 2019, every contracting authority under the Public Procurement Act — not only central government — must require e-invoices in an approved standard format, must be able to receive them through the Peppol network, and may withhold payment until a compliant e-invoice arrives. The approved formats below the EEA thresholds are EHF Billing 3.0 or later and Peppol BIS Billing 3.0 or later; DFØ says foreign suppliers use Peppol BIS Billing 3.0. [4] [5]
Network and authority. The network is Peppol; Norwegian receivers are listed in the ELMA receiver register, where a business's access point registers it. Norway's Peppol Authority is the Norwegian Agency for Public and Financial Management (DFØ). [1] [5]
B2B. Until 31 December 2026, B2B e-invoicing is voluntary and there is no clearance or real-time reporting system: Skatteetaten receives accounting data in SAF-T format only on request during a control. From 1 January 2027, sales documentation to other bookkeeping-liable parties must be issued, and purchase documentation from them received, in electronic invoice format (Bookkeeping Act section 10, as amended by lov 19. juni 2026 nr. 39); bookkeeping in an electronic accounting system follows on 1 January 2030. See the FAQ below for what the enacted text does and does not say. For VAT, registration and invoice-content rules, see the Norway VAT (MVA) guide. [2] [3]
Frequently Asked Questions
EHF vs Peppol BIS — which format should I use for Norwegian public entities?
EHF 3.0 and Peppol BIS Billing 3.0 are essentially the same format — EHF 3.0 adopted the Peppol BIS standard (EN 16931). Use EHF Billing 3.0 or Peppol BIS Billing 3.0 via a Peppol Access Point when invoicing any Norwegian contracting authority; FOR-2019-04-01-444 approves version 3.0 or later. The Norwegian Peppol Authority is DFØ, the Norwegian Agency for Public and Financial Management. [1]
My invoice to a Norwegian government buyer was rejected — what are the most common errors?
Common Peppol BIS rejection issues for Norwegian public entities: (1) Missing organization number — 9-digit Foretaksregisteret number (scheme 0192) in AccountingSupplierParty; (2) VAT number format — Norwegian VAT = org number + "MVA" suffix (e.g. 123456785MVA on paper; with the ISO prefix, NO123456785MVA, in a Peppol invoice under EN 16931 rule BR-CO-09); (3) Missing payment due date; (4) Missing or invalid tax category code — Peppol BIS Billing 3.0 allows only the UNCL5305 codes AE, B, E, G, K, L, M, O, S and Z. Norway's 25%, 15% and 12% rates all use S (standard rated) with the rate stated; Z is zero-rated and E exempt. There is no separate code for a reduced rate. Validate against a Peppol validator before submitting. [6]
Is B2B e-invoicing in Norway going to become mandatory?
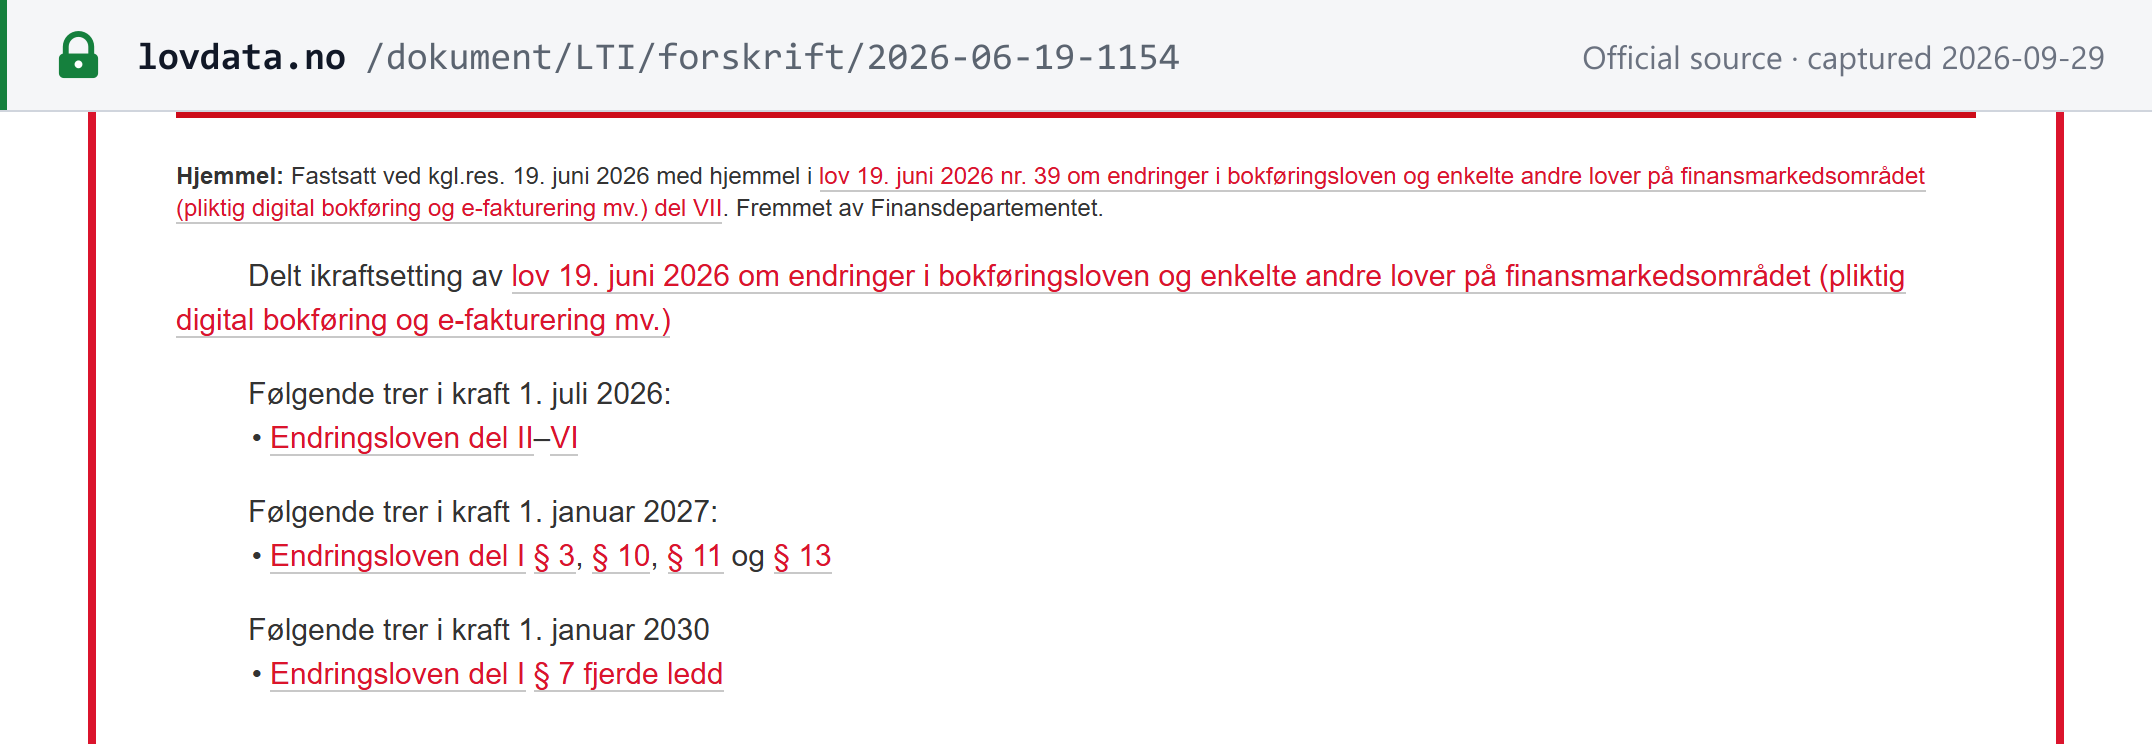
Yes — it has been enacted. Lov 19. juni 2026 nr. 39 amended section 10 of the Bookkeeping Act so that sales documentation to other bookkeeping-liable parties must be issued in electronic invoice format, and purchase documentation from them must be received in that format. Royal resolution FOR-2026-06-19-1154 brings section 10 — with the new e-invoice definition and the rule that e-invoices are kept in their original format — into force on 1 January 2027. The separate duty to keep the books in an electronic accounting system (section 7 fourth paragraph) follows on 1 January 2030. The Act defines an e-invoice as a sales document in a structured electronic format suitable for automated processing, and names no specific format. It lets the Ministry set format requirements, exemptions and transitional rules by regulation; no such regulation had been published as of 30 September 2026. Until then, B2B e-invoicing is voluntary. [2] [3]
Recent changes
- 2026-06-19 — Lov 19. juni 2026 nr. 39 amended the Bookkeeping Act; royal resolution FOR-2026-06-19-1154 brings sections 3, 10, 11 and 13 of the amending Act into force on 1 January 2027, so both issuing and receiving e-invoices between bookkeeping-liable parties apply from that date; only the electronic-accounting-system duty in section 7 fourth paragraph waits until 1 January 2030. The Act names no format and has no turnover-based exemption; format requirements and exemptions are left to regulations or individual decisions under section 10 fourth paragraph. (Lovdata) — see event
For more details on the Peppol network, see our Peppol Guide. For Norwegian VAT rates, registration and invoice content, see the Norway VAT (MVA) guide; to check a Norwegian VAT number, use the Norway MVA number validator. For the dated history of Norwegian tax changes, see Norway tax changes on Lookuptax.