Serbia TIN number guide
Jedinstveni Maticni Broj Gradana (JMBG)
Jedinstveni Matični Broj Građana (JMBG) is a unique master citizen number used for identification of citizens in Serbia.
Format:
- 13-digit numeric code
- First 7 digits - Date of birth in DDMMYYY format
- Next 2 digits - Geographic region code indicating place of birth
- Next 2 digits:
- 1-4 indicating sex (odd for male, even for female)
- Sequential serial number for people born on the same date and place
- Last 2 digits - Computer check digits
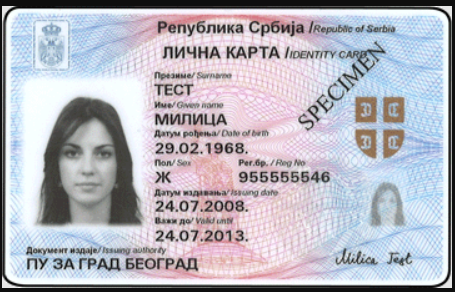 | 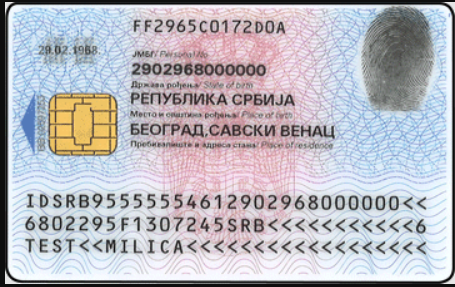 |
| JMBG card Front side | JMBG card back side |
Poreski Identifikacioni Broj (PIB)
- It is a 9-digit tax identification number used to identify businesses and other legal entities for tax purposes
- Assigned by the Tax Administration upon company registration
- First 8 digits are randomly generated
- 9th digit is a check digit calculated based on the first 8 numbers
How Lookuptax can help you in VAT validation?
Lookuptax VAT validation revolutionizes VAT number validation with its robust platform, empowering businesses to seamlessly verify VAT numbers across over 100 countries. Our cutting-edge technology ensures accurate and efficient validation, reducing errors and enhancing compliance.
Frequently Asked Questions
Does a foreign company need to register for PDV (VAT) before its first sale to a Serbian customer, even without a local entity?
It depends on who the customer is. A foreign company that supplies only Serbian VAT payers (or the public bodies listed in Article 9(1) of the VAT Law) does not have to appoint a tax representative or register: the Serbian customer is the tax debtor and accounts for the VAT under the reverse charge (VAT Law Articles 10 and 10a(2)). A foreign company making any other taxable supplies in Serbia, such as electronically supplied services to consumers, must appoint a tax representative and register for VAT whatever its turnover in the previous 12 months, so there is no threshold for it (Article 10a(1)). Businesses established in Serbia register once their total turnover in the previous 12 months exceeds RSD 8,000,000. [1] [2] See the Serbia VAT guide.
My Serbian client is withholding 20% from my invoice — when does that rate jump to 25%?
Serbia applies a standard 20% withholding tax (WHT) on payments to non-residents for royalties and certain services, such as market research, consulting, accounting and legal fees. The rate rises to 25% when the non-resident recipient is located in a jurisdiction with a preferential tax system, on a list set by the Minister of Finance (Corporate Income Tax Law, Article 40). [1]
Does a foreign business operating through a tax representative in Serbia have to issue invoices through the SEF e-invoicing portal?
Yes. Under the Law on Electronic Invoicing, a foreign person's VAT tax representative in Serbia must issue e-invoices through Serbia's Sistem elektronskih faktura (SEF) for transactions with the private and public sectors; the Law names no issuing duty for a foreign supplier without a tax representative. Between VAT payers, e-invoices are issued and received through SEF in UBL 2.1 XML to the Serbian EN 16931 standard, and an e-invoice is an authentic document only if sent through SEF. Breaching the issuing duty carries a fine of RSD 200,000 to 2,000,000 for a legal entity, RSD 50,000 to 500,000 for an entrepreneur and RSD 50,000 to 150,000 for the responsible person. [1] See the Serbia e-invoicing guide.